US immigrants in 2013:
13% of the population
16% of the workforce
33% of small business ownershttp://t.co/UyJjvClvw2 pic.twitter.com/WdiaBCVLLC— Nick Timiraos (@NickTimiraos) January 14, 2015
Time to be completely shallow: stars without make up
10 Jan 2015 Leave a comment
in economics of information, economics of media and culture, entrepreneurship, human capital
The two rules of success
10 Jan 2015 Leave a comment
in economics of information, entrepreneurship
Two rules for success http://t.co/qeRC8iKuyX—
Learning (@FactsGuide) December 27, 2014
Science Doesn’t Need Public Funding
09 Jan 2015 Leave a comment
in applied price theory, applied welfare economics, comparative institutional analysis, economic history, economics of education, entrepreneurship, rentseeking Tags: economics of science, innovation, R&D

For home appliances, the ‘good old days’ are now: they’re cheaper, better and more energy efficient than ever before » AEI
07 Jan 2015 Leave a comment
in energy economics, entrepreneurship Tags: directed technical change

Michelle Malkin | My trip to the pot shop
04 Jan 2015 Leave a comment
in applied welfare economics, economics of regulation, entrepreneurship, health economics, liberalism Tags: decriminalisation of marijuana, drug decriminalisation, medical marijuana


Creative destruction: the product life cycle versus the revenue life cycle
24 Dec 2014 Leave a comment

The SkyCity bailout: it is common for private sector mega-projects to fail
24 Dec 2014 3 Comments
in entrepreneurship, politics - New Zealand, rentseeking, survivor principle Tags: casino regulation, corporate welfare, SkyCity

SkyCity is sniffing around the New Zealand government for a $130 million bailout. The initial project estimate was $402 million for a convention centre and enlarged casino.

SkyCity was very clear when the convention centre deal was announced that it would be at no cost to either taxpayers or Auckland ratepayers. That is a clear assumption of the entrepreneurial risks – both the upside of high profits and the downside of cost overruns and losses.
The literature on mega-projects suggests that large engineering projects frequently fail to achieve their intended financial and operating objectives. Nine out of ten mega-projects have cost-over runs:
- Miller and Lessard (2000) studied 60 large engineering projects with an average size of $1 billion. Almost 40% of the projects performed very badly and were abandoned totally or restructured after a financial crisis.
- Merrow et al. (1988) found that four of the 47 megaprojects they studied came in on budget – the average cost overrun was 88%. Of the 36 projects that had sufficient data, 26 failed to achieve their profit objectives.
- Flyvbjerg et al. (2003) analyzed 258 large transport projects (toll roads, bridges, railroads, etc.). Cost overruns of 50% to 100% and revenue shortfalls of 20% to 70% were common.
Table 1 below gives more details on cost overruns in rail, bridge and road engineering projects overseas. Cost overruns averaging 27.6% were found with rail having much larger cost overruns than road or bridge construction.
Table 1: Inaccuracy of transport mega-project estimates
| Project type | Number of projects | Average cost escalation |
| Rail | 58 | 44.7% |
| Bridge | 33 | 33.8% |
| Road | 167 | 20.4% |
| All projects | 258 | 27.6% |
Source: Flyvbjerg et al (2003).
Cost over-runs are not the preserve of the public sector. Merrow (2011) found that over half of large-scale engineering and construction projects – off-shore oil platforms, chemical plants, metals processing, dams, and similar projects – had poor results: Billions of dollars in total overruns, long delays in design and construction, and poor operability and revenue shortfalls once completed.
Alchian (1950) illustrated the unreliability of cost estimation with the range of bids made in tendering processes. When contractors bid for the same project, they routinely disagree over its likely cost by margins of 20 percent. The contractors are predicting their own costs, about which they are knowledgeable, and they have an incentive to be truthful to win the initial tender. Initial cost estimates by engineers have margins of error of 25 percent (Alchian 1950).
Central to capitalism is the notion of profit and loss. Entrepreneurial endeavours that anticipated the matort well make a profit. The rest fall by the wayside.
SkyCity is a private investment that should stand or fall on the same criteria as any other business venture in New Zealand.
What should be asked by the taxpayer in all these business subsidies is what the value for money for their tax dollars is?
What is the problem that has been solved other than common garden business failure? Can this problem be solved by market process on its own at its own pace subject to hard budget constraints, competition in the market place, the threat of innovation at home and abroad, and continuous updating of the knowledge available to the entrepreneurial decision-makers by changes in prices and profits and losses. As Friedman said:
The strongest argument for free enterprise is that it prevents anybody from having too much power.
Whether that person is a government official, a trade union official, or a business executive, it forces them to put up or shut up.
They either have to deliver the goods, produce something that people are willing to pay for, are willing to buy, or else they have to go into a different business.
Losses and bankruptcies are fundamental to the success of the market economy. Losses are a clear signal that need to restructure, cut costs or go out of business. The paraphrase Mao, ‘Bankrupt one, educate a thousand’.
Corporate welfare, such as a bailout to SkyCity and at such an early stage in the investment postpones these difficult choices. As George Stigler explained:
One great invention of a private enterprise system is bankruptcy, an institution for putting an eventual stop to costly failure.
No such institution has yet been conceived of in the political process, and an unsuccessful policy has no inherent termination.
Indeed, political rewards are more closely proportioned to failure than to success, for failure demonstrates the need for larger appropriations and more power.
The fact that the government regulates part of SkyCity’s business because it is a casino is no case for a bailout. The purpose of casino regulation is to constrain the size of that industry, not help it grow.

Real business cycles, the declining clarity of information and learning by waiting
22 Dec 2014 Leave a comment
in business cycles, entrepreneurship, job search and matching, macroeconomics Tags: real business cycles
Willems and van Wijnbergen (2013) identified reduced clarity in information about business cycle fluctuations as a factor that is the lengthening the lag in the response of employment to output changes in recent US recessions.
Willems and van Wijnbergen (2013) – ungated – found that the trough in employment in the 1991 and 2001 recessions was much later than the troughs for earlier US recessions.
- There was a stronger immediate reduction in employment in pre-1990 US recessions and a faster recovery, so the 1991 and 2001 recessions were initially job-preserving – the rate at which workers were laid off was less than in prior recessions.
- Employment in the 1991 and 2001 recessions continued to fall for another year after the trough in output.
- The job-preserving recessions in 1991 and 2001 were then followed by this delayed recovery in employment growth.
- There is a lengthening labour adjustment lag that slows the loss of jobs at the start of recessions and delays the renewal of recruitment at the end of recessions.
Willems and van Wijnbergen (2013) attributed this combination of job-preserving recessions and delayed employment recoveries in 1991 and 2001 to the interaction of rising labour adjustment costs and a reduction in the clarity of entrepreneurial information about the business cycle.
The rising labour adjustment costs arose from the capital losses to employers of laying off employees who are increasingly rich in firm-specific human capital. The risks of laying off and investing precipitously have increased in recent decades because output growth subsequent to the great moderation in real output growth volatility is less predictable.
The US economy experienced a 50% reduction in volatility for many leading macroeconomic variables as well as low inflation since the early to mid-1980s. Similar declines in the real volatility and inflation rates occurred at about the same time in other industrial countries.
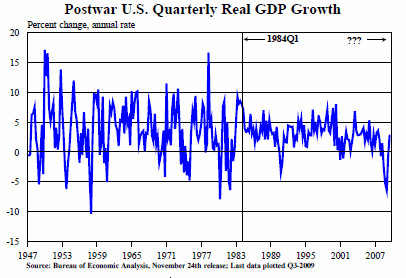
Prior to the mid-1980s, US real output growth was more variable, but this variation was more predictable. Frequent recessions were soon followed by recoveries. Since the early to mid-1980s in the US, major variations in real GDP growth have come increasingly as genuine surprises – 1983–2007 was one long boom punctuated by two mild recessions in 1991 and 2001.
The delay in the official dating of the peaks and troughs in business cycles in the US has increased from an average of 7½ months before 1990 to about 15 months in the post-1990 period (Willems and van Wijnbergen 2013).

With recessions more of a surprise – and the scope and depth of the panic of 2008 is an example of such a surprise in New Zealand and abroad – the value of waiting for better market information has increased.

Less certain information makes it more profitable than before for entrepreneurs to invest in waiting before laying off increasingly human capital-rich employees, making new investments and undertaking fresh recruitment. The impact of the business cycle on employment will be more muted.
Modern recessions can be initially job-preserving – layoffs are postponed for longer because the rising cost of laying off experienced labour is higher and because of the increased value of waiting to see. Recoveries in employment can be more sluggish as investors wait to be sure about the latest trends. These employers can use the employees they hoarded in larger numbers in the downswing to fill orders in the early days of the upswing in business:
We have presented evidence that the lag with which labour input reacts to structural economic shocks went up in the 1980s, thereby bringing jobless recoveries and recessions that were relatively job preserving to the US economy.
Using a real option model, this lagged response is shown to be optimal in a setting where labour input is costly to adjust and where employers are uncertain about the persistence of shocks that drive the business cycle
What’s the difference between inflation and counterfeiting? The Portuguese banknote caper
21 Dec 2014 Leave a comment
in economics of crime, entrepreneurship, monetary economics Tags: Counterfeiting, fraud, swindles
Robert Barro recounts in his macroeconomics textbook a marvellous example where swindlers induced a British manufacturer of bank notes to print and deliver to them 3 million pounds’ worth of Portuguese escudos, which was equivalent to about 1% of Portugal’s nominal GDP in 1926.
This company, Waterlow and Sons Ltd. of London, also printed the legitimate notes for the Bank of Portugal. These bogus notes were,at first pass, indistinguishable from the real thing (except that the serial numbers were duplicates of those from a previous series of legitimate notes).

It was impossible to differentiate between the original and most of the duplicate banknotes because they were printed by the same printer using the same plates. 135,318 of the duplicate notes could be identified as part of the swindle because they were printed on plates not used for any other Portuguese banknotes. These bogus notes printed with the new plates could be differentiated from older legitimate banknotes because of a few marks that could be identified by an expert using a magnifying glass.
Central to the scam was taking advantage of the practice of the privately owned Bank of Portugal of secretly printing banknotes and neither recorded such transactions in the books, nor informing the government of the increase in the number of circulating banknotes.
(At the time, the Bank of England was also privately owned and only in 1921 had it obtained a monopoly on the issue banknotes in England and Wales. The Bank of Scotland still prints Scottish banknotes that are not legal tender in England. Three northern Irish banks still print banknotes that are legal tender in Northern Ireland. The entire northern Irish currency was withdrawn from circulation after a major bank robbery by the IRA a few years ago and replaced with new notes).
After the scheme unravelled, the Bank of Portugal made good on the fraudulent notes by exchanging them for newly printed, valid notes. The fraud may have contributed to the military coup, some six months later.
In the interim, by illegally increasing the monetary base and investing heavily in currency, land, building, and businesses, the swindlers created a boom in the Portuguese economy.

From the standpoint of monetary economics, I cannot think of a more unanticipated monetary shock. Of a surprise burst of monetary inflation and price inflation and led to the writing of books with titles such as The Man who Stole Portugal.
The final part of the swindle was to actually buy a controlling interest in the Bank of Portugal to validate the fraud by erasing all records that might inconvenience the swindlers.
The chief swindler with accomplices set up a bank of his own to facilitate fast distribution of the forged currency. A bank of their own was necessary because they had the modern equivalent of $150 billion to launder.
This Bank of Angola & Metropole set up to launder the bogus notes was also the initial place of suspicion of something fishy going on because it grew so quickly, while taking no deposits. Germans are also involved with this bank. Germany was suspected by the Portuguese government to have ambitions to take over Portuguese Angola, so this attracted additional attention from the authorities.
The chief swindler, Alves Reis, was depicted in a 50-episode TV series in 2000 as well as several books about the fraud over the decades.
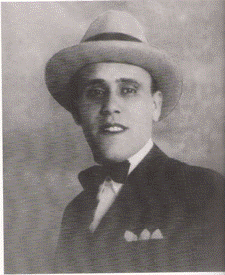
At the time of the swindle, Reis was 28 years old engineering dropout from an undistinguished middle-class Lisbon family. He already had a conviction for cheque fraud. As such, one of the greatest swindles of all time was pulled off by a petty conman.
The swindle unravelled because of the duplicate banknote serial numbers, which was an error the swindler made himself. But for that, the swindle would have been immensely difficult to uncover. The swindlers duplicated the existing serial numbers and hoped they were able to successfully release all the banknotes before they were caught.
Reis, the architect of the swindle, work out the sequence of bank governor names and serial numbers used by the Portuguese central bank, but had neglected to eliminate numbers already ordered.
When the British printer realised this, Reis convinced the London firm that the reuse of existing serial numbers for their purported place of circulation in the Portuguese colony of Angola was not a cause for alarm. Fortunately for the swindlers, a letter from the British printers to the Banco de Portugal, in that he spoke about the agreements to print the banknotes for distribution in Angola went missing in the post.
The Bank of Portugal was not supposed to issue its currency in Angola, but often did circulate its currency in Angola.
This was a clever part of the swindle. By pretending that the Bank of Portugal was doing something slightly dodgy but still standard practice, and thus had to do so in secrecy, the swindlers could induce a whole range of other more legitimate people than them to cooperate quietly with what they were doing.
The shady nature of these dealings to surreptitious circulate Bank of Portugal banknotes in Angola stamped with “Angola” was passed over by the British dupes to the swindle as another example of the corruption of Portuguese officials. The stamp “Angola” was so they wouldn’t be confused with notes from the mother country.
In addition, bank notes for the Portuguese colonies were printed at the time by a competitor. The British printer saw this on the quiet contract as an opportunity to take away some of their trade.
The swindlers said that they would take care of stamping “Angola” on the banknotes once they were delivered to them. The swindlers had accomplices in the Portuguese diplomatic service, who issued them with fake diplomatic passports, which was helpful in persuading the British printers to deliver the bogus banknotes personally to them. Consignments were delivered to the swindlers in February, March and November 1925.
the basis of the scam was forging a contract in the name of Banco de Portugal authorising Reis to print banknotes in return for an alleged loan from a consortium to develop Angola. The whole affair had to be kept secret lest Angola fall into further financial difficulties due to rumours of a pending economic ruin.
The London based specialty printer worked, for among other clients, for the English court system and printed the transcripts of its own trial! This printer tried to have the trial postponed for a year while its chief executive completed his one-year term as Lord Mayor of London to save embarrassment.
The British printing company was found liable in subsequent four years of litigation, but the key question for the court was the amount of damages.
- The Bank argued that the damages were £1 million (less funds collected from the swindlers).
- The British printer duped by the swindlers argued was that the only true costs to the Bank were the expenses for paper and printing of the replacement notes.
The House of Lords determined in 1932 that £610,000 was the correct measure. This award of damages was the £1 million less the funds recovered from the swindlers
The proper measure of damages, in the view of the majority of the Law Lords, was the face value expressed in sterling of the genuine currency given in exchange for the spurious notes.
As these damages would be paid initially in British pounds, this damages award was a real windfall for the Bank of Portugal. Worthless Portuguese banknotes exchanged for good British pounds that could buy imports.
The majority decision of the Law Lords was the correct measure of damages because that is what the bank had to outlay to make itself whole again after the breach of contract. The chief swindler got 20 years.
One of the two Law Lords in dissent had another view of the proper measure of damages:
The judgment of Wright J. should be set aside and judgment entered for the Bank for the sum of £8,922
This law lord and an appeal court justice held this view because the swindle cost the Bank of Portugal nothing bar printing costs to replace the spurious banknotes, which were widely accepted as valid currency in a cash economy.
The Bank of Portugal could issue banknotes in any number at little cost to itself up to the limit provided by Portuguese law. Ropke wrote that:
The English courts presently discovered that the case involved issues of unusual subtlety and complexity, adjudication of which necessitated the admission of testimony by leading monetary theorists.
The question before the courts was: how great were the actual losses incurred by the Bank of Portugal?
If it had been postage stamps instead of bank notes in which the swindlers had trafficked, it is perfectly clear that the loss of the Portuguese government would have equalled the total value of the stamps.
With respect to the bank notes, however, no such simple calculation could be made.
Among the many questions which troubled the experts the following stand out as particularly relevant to our study: would the Bank of Portugal have issued the same amount of notes even if the swindlers had not done so?
If not, was the increase in the supply of money resulting from the introduction of the fraudulent notes good or bad for Portugal?
No one disputes, as several of the Law Lords noted, that the theft of a postage stamp must be made good at face value. People hesitate in this case involving swindling access to banknote plates and printing currency for yourself because what exactly was stolen?
When Reis died in 1955 , The Economist said of the counterfeiting scheme:
The perpetrators, however reprehensible their motives, did Portugal a very good turn according to the best Keynesian principles.
The House of Lords case is a major British legal precedent regarding the duty of the wronged party to mitigate damages in the case of breach of contract.
The House of Lords held that this duty did not apply if it would give your business a bad name in the trade. The Bank of Portugal could have repudiated the duplicate banknotes rather than exchange them for genuine new notes, but chose not to do so because this repudiation of banknotes would have ruined what little reputation it had.
The House of Lords also upheld the right of the wronged party to choose between different methods to mitigate damages from the breach of contract.
 Utopia, you are standing in it!

Recent Comments