Sargent on moderate inflations

Sargent on hyperinflation

@TaxpayersUnion SUBMISSION ON THE FUNDING STRATEGY FOR THE DEPOSITOR COMPENSATION SCHEME @GeorgeSelgin

16 September 2023

Financial Markets
The Treasury
PO Box 3724
Wellington 6140

By email sofaconsultation@treasury.govt.nz

cc: David Hargreaves
      Manager, Policy Projects
      Financial System Policy and Analysis Department
      Reserve Bank of New Zealand
      Wellington 6140

      By email: dta@rbnz.govt.nz

DEPOSIT TAKERS ACT 2023: SUBMISSION ON THE TREASURY CONSULTATION PAPER ON THE STATEMENT OF FUNDING APPROACH – FUNDING STRATEGY FOR THE DEPOSITOR COMPENSATION SCHEME

About the Submitter

  • This submission has been prepared for the New Zealand Taxpayers’ Union by Research Fellow Jim Rose. Jim is an economist with three decades experience in the public sector in New Zealand and Australia. He has worked at the Ministry of Business, Innovation and Employment, the Department of Labour, the Ministry of Social Development, and the New Zealand Treasury, and in Canberra for the Productivity Commission, the Department of Prime Minister and Cabinet, and the Department of Finance. Jim has a master’s degrees in economics from the Australian National University and a master’s degree in public policy from the National Graduate Institute for Policy Studies in Tokyo.
  • Founded by David Farrar and Jordan Williams in 2013, the Taxpayers’ Union’s mission is Lower Taxes, Less Waste, More Transparency.
  • We enjoy the support of some 200,000 registered members and supporters, making us the most popular campaign group championing fiscal conservatism and transparency.  We are funded by our thousands of donors and approximately two percent of our income is from membership dues and donations from private industry.
  • We are a lobby group, not a think tank.  Our grassroots advocacy model is based on our international taxpayer-group counterparts, particularly in the United Kingdom and Canada, and similar to campaign organisations on the left, such as Australia’s Get Up, New Zealand’s ActionStation, and Greenpeace. 
  • The Union is a member of the World Taxpayers Associations – a coalition of taxpayer advocacy groups representing millions of taxpayers across more than 60 countries. 
  • We give permission for the Treasury to publish this submission.

The Treasury and Reserve Bank consultation papers on deposit insurance implementation

  • The Treasury has released a consultation document on the proposed funding approach by the Minister of Finance. This document discusses how quickly the deposit insurance reserve fund might accumulate towards a target reserve amount over 10 or 20 years then no further levies will be charged. The reserve target proposed by the Treasury would be between 0.5% and 1.1% of insured deposits at the end of an accumulation period of up to 20 years. This would result in a deposit insurance reserve fund of between $600 million and $1.4 billion when the target is reached.
  • The Reserve Bank has released a consultation document on what deposit insurance levies might be charged to deposit takers. This document discusses whether there should just be a general levy of 0.1% on insured deposits. This means the same levy of about 10 basis points for all deposit takers irrespective of individual risk. The alternative proposal is that the pricing of deposit insurance should be risk-based. Among the possibilities floated is a deposit insurance risk-based premium based on credit ratings or the allocation of deposit takers to four risk buckets. The proposed risk-based premium would range from 10 basis points for the safest of the banks to 40 basis points as a maximum.

Our previous submissions on deposit insurance

  • By way of background, the Taxpayers’ Union met with the Treasury in October 2020 on deposit insurance and the risk of fraud in the finance company sector. We made a submission to the public consultation on the draft Deposit Takers Bill pursuing those themes, and we made a submission to the Select Committee along with an appearance before that Committee.
  • The themes of those submissions were the poorly thought-out rationale for deposit insurance and the unwise decision to extend it to the finance company sector. Reasonable people can disagree about the wisdom of deposit insurance for banks, about whether to have it at all and how much cover to offer. Not so for finance companies.
  • We submitted that implementing deposit insurance for finance companies would be a short-sighted policy and must be considered as a policy option distinct from deposit insurance only for banks. Finance companies operate within a different set of moral hazard concerns than banks do, which deposit insurance schemes interact with to drive the sort of risk-seeking behaviour that makes the Crown deposit guarantee more likely to be activated. Economic stability is, however, not protected by deposit insurance for finance companies, in the same way it might be for banks.
  • Finance companies now account for a tiny share of deposit taking institutions. The deposit guarantee put in place for finance companies at the height of the GFC was of dubious value, even with their twenty times larger than now share of the deposit taking market in 2008. While there is a valid debate as to the correct policy about insuring deposits in banks, the case is settled that finance companies should not be included in a deposit insurance scheme such as the one proposed in the Deposit Takers Bill. We recommended to the Select Committee that finance companies be removed from the Bill.

Scope of our current submission

  • This submission on behalf of the Taxpayers’ Union is limited to discussing the reserve fund target, the preferred reserve fund target size, and the realism of the deposit taker failure scenarios. We will also discuss what we see as gaps in the analysis in the consultation paper. Our special focus will be managing the fiscal risks to the taxpayer from the implementation of a successful deposit insurance scheme that includes finance companies, in particular, and credit unions and building societies.
  • The Taxpayers’ Union will be making a submission to the Reserve Bank on its consultation paper on the deposit insurance levy framework. That submission will focus on the need for the deposit insurance premium to be risk-based and that that will not be possible if the deposit insurance reserve fund has a target set for it by the Minister. Gaps in analysis will also be discussed in that submission.

Key points in this submission

  • Deposit insurance is to be offered to a mixed bag: banks with a remote possibility of failure and finance companies whose credit ratings often imply a default probability of one chance in 10 in the next five years. Most building societies and credit unions are not much better.
  • There should be sub-targets for the reserve fund for premiums collected from banks and for premiums collected from non-bank deposit takers to make transparent the level of insurance coverage to each sector and when payouts on deposit insurance constitute a cross-subsidy.
  • Investors will move back into the non-bank deposit taking sector because deposit insurance will remove risk. They will keep their deposits with any one institution at no more than the deposit insurance coverage limit of $100,000.
  • We would prefer that there should not be a target for the deposit insurance reserve fund at all because having a target rules out the possibility of risk-based deposit insurance premiums. Once the target is reached, no further premiums are charged so the deposit insurance becomes free.
  • The recent bank runs overseas illustrate how difficult it is for governments to not honour implied guarantees for all deposits with banks and banks to be bailed out when they take excessive risks.
  • The recent bank runs overseas should have led the Treasury to consider a larger, more fortified reserve fund to be accumulated perhaps over a longer time-period such as 30+ years.
  • The motivation for our submissions has been that deposit insurance is a dicey policy tool because of moral hazard. The recent bank failures overseas should have led to some refection on this moral hazard dilemma by the Treasury and the Reserve Bank but that didn’t happen.

The deposit insurance funding approach to government insured junk bonds

  • The statement of funding approach should take a clear tack on the mixed bag of deposit takers it plans to include in the Crown deposit guarantee. Some of these deposit takers are far more likely to call upon the deposit guarantee than others. In addition to nearly all banks having high credit ratings, the non-bank deposit takers have more questionable credit ratings but will receive a deposit guarantee, nonetheless. Prior to the global financial crisis (GFC), all but five of the sixty odd finance companies lacked a credit agency rating, but they still received a temporary Crown deposit guarantee.
  • The majority of the seven remaining finance companies now do have credit ratings at a BB standing or less; see table 1 below which shows their credit ratings as well as a standardised explanation of default probabilities. The same table shows the credit ratings and the default probabilities implied by those ratings for the credit unions and building societies. The appendix to this letter has a full explanation of the default probabilities implied by all the ratings issued by the three credit rating agencies.

Table 1: Non-bank deposit taker credit ratings

Deposit takerCredit rating agencyRating & outlookApprox probability of default over 5 years
Christian Savings LtdFitch RatingsBB, Stable1 in 10
FE Investments Ltd (in receivership) n/aCredit ratings withdrawn 
Finance Direct Ltdn/aExempt 
General Finance LtdEquifaxBB-, PositiveLow to moderate risk
Gold Band Finance Ltdn/aExempt 
Liberty Financial LtdStandard & Poor’sBBB-, Stable1 in 30
Mutual Credit Finance Ltdn/aExempt 
Xceda Finance LtdEquifaxB, StableModerate to high risk
Credit Union AucklandEquifaxCCC+, NegativeA very high level of risk
First Credit Union Inc.Fitch RatingsBB, Stable1 in 10
Fisher & Paykel Credit Union Exempt 
Police and Families Credit UnionEquifaxBB+, StableLow to moderate risk
Unity Credit UnionFitch RatingsBB, Negative1 in 10
Heretaunga Building Society Exempt 
Nelson Building SocietyFitch RatingsBB+, Stable1 in 10
Wairarapa Building SocietyFitch RatingsBB+, Stable1 in 10

Sources: Reserve Bank at https://www.rbnz.govt.nz/regulation-and-supervision/cross-sector-oversight/registers-of-entities-we-regulate/register-of-non-bank-deposit-takers-in-new-zealand and https://www.rbnz.govt.nz/regulation-and-supervision/oversight-of-banks/standards-and-requirements-for-banks/bank-credit-ratings and Equifax at https://nzcuauckland.co.nz/assets/files/info-files/Credit-Union-Auckland-Credit-Rating-June-2023.pdf, https://generalfinance.co.nz/service/credit-rating/, https://www.xceda.co.nz/media/ntfcqtku/equifax-credit-rating-interim-full-year.pdf, and https://www.policecu.org.nz/documents/167/PFCU_Credit_Rating__Synopsis_Dec22_.pdf
  • The BBB credit rating suggests investment grade; BB means a higher probability for default. BB and B bonds fall in the category of junk bonds, high-yield bonds, or speculative instruments. The B rating suggests a company can meet its financial commitments but may be left highly exposed to adverse economic conditions. For Moody’s, BB and B bonds are speculative and “subject to a substantial risk of defaulting on certain senior operating obligations and other contractual commitments.” As an example, South Canterbury Finance was BBB rated when its deposits were guaranteed by the Crown in 2008. This implies a probability of failure of one chance in 30 in the next five years.
  • Several of the finance companies in Table 1 have a one chance in 10 probability of default over the next five years – see table 1 above, columns three and four. The building societies and credit unions are not much better in their credit ratings. That high risk to be taken onto the Crown portfolio because of the Crown backstop should be considered when deciding the target size for the reserve fund.
  • Their current credit ratings suggest that a finance company, credit union or building society might make an early call on the deposit guarantee before the reserve fund accumulates to the target set by the Minister. This will mean the Crown backstop to the deposit insurance reserve fund will be called upon rather early in the life of the deposit insurance scheme. The banks will be paying into that same reserve fund so their premiums will be cross-subsidising any early call by the credit unions, the finance companies, or the building societies on the freshly minted deposit insurance reserve fund. This high risk of a default by a credit union, a building society or a finance company crosses over into the setting of the deposit insurance premium. We will be writing separately to the Reserve Bank on this matter regarding the Bank’s consultation paper on the deposit insurance levy framework.

Deposits flooded into finance companies off the back of the 2008 Crown deposit guarantee

  • The Statement of Funding Approach should consider the probability, the high probability, that there will be a surge of deposits into the higher risk non-bank deposit taking sector. This happened in the past at home and abroad off the back of government guarantees of retail deposits.
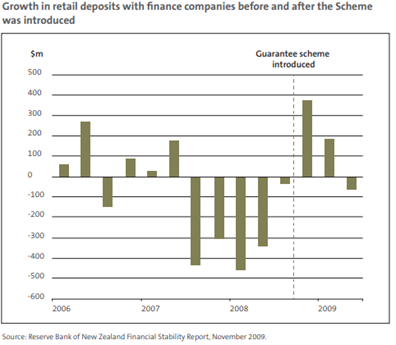
  • After bleeding money in 2007 and 2008, there is a surge in deposits after the 2008 Crown guarantee for finance companies, see the chart below from the report by the Auditor-General (2011). South Canterbury Finance grew by 25% in deposits after the Crown guarantee (Auditor-General 2011); deposits in South Canterbury Finance increased from $75 million in 2004 to $2 billion in 2008 (O’Sullivan 2015). Another company grew from $800,000 in deposits to $8 million in deposits off the back of the Crown retail deposit guarantee (Auditor-General, 2011).
  • There is little discussion in the Treasury and Reserve Bank papers of the implications of the deposit guarantee for a resurgence of investor interest in what is an intrinsically riskier sector. There is no mention in the Reserve Bank and Treasury papers of the massive surge in investment in finance companies after the 2008 Crown retail deposit guarantee, as shown in the chart below from the report by the Auditor-General. Instead of bleeding $500 million every quarter as in the lead up to the GFC, $600 million flooded back into the sector off the back of the Crown retail deposit guarantee.
  • The previous experiences of the Treasury in administering the Crown deposit guarantee after the global financial crisis is barely mentioned in the consultation paper. That is unsatisfactory because the Auditor-General’s report was highly critical of the Treasury’s administration of that scheme.
  • Now as then, the Treasury (and the Reserve Bank) appear to be aloof to the mercurial nature of deposit insurance as a policy instrument. It can bite back at the taxpayer big time as the 2008-2011 scheme certainly did. The deposit guarantee has not been jumbled together in a few days as was the guarantee cobbled together at the height of the GFC. This reincarnation is years in the making.
  • The Auditor-General’s 2011 review found that the Treasury was focused on how to pay out depositors with little regard to how to reduce risk to the Crown by offering deposit insurance to failing finance companies. Indeed, the Crown deposit guarantee was renewed for South Canterbury Finance despite the Treasury having concluded at the time that the finance company was likely to fail:

The Treasury received the inspector’s report on 17 July 2009. The report reaffirmed the seriousness of the risk factors suspected with the books and management of South Canterbury Finance. From April to August 2009, the Treasury investigated the affairs of South Canterbury Finance extensively. On 12 August 2009, the Treasury made a provision for the estimated loss if South Canterbury Finance failed. This provision reflected the Treasury’s judgment that South Canterbury Finance was more likely than not to fail. The provision was made with the benefit of the inspector’s report (Auditor-General 2011, p.103).

  • Would a fair deposit insurance premium towards the end be perhaps up to one-half of South Canterbury Finance’s deposits under a Crown guarantee? To quote the Audit report again:

The Treasury’s monthly financial statements did not include any provisions for pay-outs under the Scheme until June 2009, when the provision was estimated at $0.8 billion. The Treasury knew before June 2009 that further failures of finance companies were likely, so this information should have been better reflected in the monthly financial statements earlier than June 2009 (Auditor-General 2011, p.94).
  1. About $1.6 billion of the $2 billion in initial losses to the Crown from the deposit guarantee were from the failure of South Canterbury Finance. The Treasury didn’t face up to the facts as early as it should have with the 2008-2011 Crown deposit guarantee to finance companies. History is repeating.

Depositors chase riskier returns when government insured

  • The proposition that depositors will invest in higher risk returns if they are government insured is well-established overseas. The burst of deposits back into the finance company sector after the government guarantee in New Zealand in 2008 is not an anomaly to be dismissed.
  • For example, Martin, Puri, and Ufier (2018) examined the daily account level balances of a distressed bank in the USA at the height of the GFC. They studied the outflow (bank run-off) of uninsured depositors and the inflow (bank run-in) of insured deposits as this bank was in its death throes. The maximum level of federal deposit insurance increased from $100,000 to $250,000 per account holder as a stabilisation measure at the height of the GFC in 2008.
  • Martin, Puri, and Ufier (2018) found that this failing bank was able to replace about 1/3rd of its depositor base in its last year of life. This was despite public knowledge of the intensive regulatory scrutiny of its declining condition. Much of these new deposits came in in the last 90 days of the bank. The bank’s regulatory filings spoke of being significantly undercapitalised and then a critically undercapitalised financial state. The new deposits were almost all term deposits paying slightly above market interest rates and were just under the Federal Deposit Insurance Corporation insurance limit. These deposits initially bunched at the $100,000 limit, then bunched at the $250,000 insurance limit when this limit was increased at the height of the GFC in October 2008.
  • Iyer, Jensen, Johannesen and Sheridan (2019) had access to all personal deposit accounts and their balances in Denmark when they studied changes in deposit insurance for Danish banks. The Danish government guaranteed all bank liabilities in 2008. Prior to the GFC, deposit insurance was limited to 300,000 Danish kroner. The Danish government later limited deposit insurance to 750,000 Danish kroner in 2011. The Danish government also named six Danish banks as too big to fail.
  • Iyer, Jensen, Johannesen and Sheridan (2019) found that for the banks that were not too big to fail, accounts clustered around the insurance limit of 750,000 Danish kroner. There was no similar bunching of deposits at the deposit insurance limit for the six large banks deemed by the Danish Government to be too big to fail. Canny Danish depositors quickly sifted out where their deposits were fully guaranteed by the Danish government and where they were only partially guaranteed. Iyer, Jensen, Johannesen and Sheridan (2019) also found the deposits above the insurance limit of 750,000 Danish kroner halved in the smaller banks that were not too big to fail but fell only by 20% in the six large banks that were marked by the Danish government as too big to fail.
  • Belgian depositors were just as canny as their Danish neighbours in sifting through the incentives behind explicit and implicit government guarantees. Atmaca, Kirschenmann, Ongena and Schoors (2020) used micro-data on 300,000 Belgian depositors of a large European bank during 2008 and 2009. In November 2008, Belgian deposit insurance was increased from €20,000 to €100,000 per customer-bank relation. The bank under study, like several other EU banks, was first nationalised and then re-privatised. In the run up to the GFC, more and more depositors limited their deposits to €20,000 for full coverage. Once coverage is increased to €100,000, €100,000 bunching largely substituted for €20,000 bunching. This €100,000 bunching faded away during the period of nationalisation, when implicit blanket guarantees apply. It then returned in full force once the bank was re-privatized and the new €100,000 coverage limit was the binding guarantee for the depositors.

Insured deposit takers take more risks

  1. It is well-established that deposit takers respond strongly to the introduction of deposit insurance or an increase in coverage. Lambert, North and Schuwer (2017) looked at what happened to insured deposits in 1,300 federally insured banks in the USA when their deposit insurance coverage was increased in October 2008 from $100,000 to $250,000. For some banks, the amount of their federally insured deposits increased significantly. The most affected banks were found by Lambert, North and Schuwer (2017) to increase their loans to risky commercial real estate, when compared to those banks that were largely unaffected by the federal deposit insurance limit increase.
  2. Gropp, Gruendi and Guettler (2014) studied the response of 452 German savings banks after government guarantees were removed, following a lawsuit in the European Court of Justice in 2001. As a group, savings banks in Germany have assets totalling 1 trillion Euro and 22,000 branches. Gropp, Gruendi and Guettler (2014) found that the German savings banks cut off their most risky borrowers and raised interest rates to the rest after the guarantee was removed. There were no similar effects in the control group of German banks to whom the guarantee was not applicable.
  3. Calomiris and Jeremski (2019) looked at eight state deposit insurance schemes that were open to state charted banks but not federally chartered banks. They found that the insured state-chartered banks competed aggressively for deposits with their uninsured rivals, reduced capital ratios and were more likely to fail. Wheelock (1992), Wheelock and Kumbhakar (1995) and Wheelock and Wilson (1994, 1995) found that the less solvent, and less efficient banks joined a voluntary state deposit insurance scheme in Kansas, and they were twice as likely to fail as similar uninsured banks. A strong institutional background is required to manage this risk of depositors chasing down government insured higher returns and deposit takers taking more risks in lending when their deposits are insured by the Crown.

Managing risk-inviting rules of the game

  • There were many more banking crises over the last 40 years around the world. Their most common cause was ever more generous safety nets, including the moral hazard risks from the proliferation of deposit insurance starting in the 1980s. The leading scholar in the field finds that:
  • Recent research that investigates the determinants of banking fragility across different countries in the current era reaches a similar conclusion: the expansion of government-sponsored deposit insurance and other bank safety net programs throughout the world in the past three decades accounts very well for the increasing frequency and severity of banking crises in the current era. Empirical studies of this era of unprecedented frequency and severity of banking system losses has concluded uniformly that deposit insurance and other policies that protect banks from market discipline, intended as a cure for instability, have instead become the single greatest source of banking instability (Calomiris 2009).
  • Deposit insurance, such as that to be rolled out in New Zealand, invites risk-taking but its redeeming feature is once the banking crisis it seeded occurs, it may quell a bank run or banking panic (Anginer, Demirgüç-and Zhu 2014). When pondering deposit insurance for banks, there is a subtle policy trade-off between the incentive to take more risks and seed a banking crisis must be weighed against the stabilising influence of deposit insurance when there is a banking crisis and the possibility of bank runs (Allen, Carletti, Goldstein and Leonello 2018; Gorton and Winton 2003). Reasonable people can disagree earnestly over whether the financial policy trade-off between encouraging moral hazard and a better banking crisis management tool kit justifies offering deposit insurance to banks.
  • The consultation paper by the Treasury does not state clearly that the non-bank deposit takers are a far greater risk than banks, and that they are far more likely to draw on the deposit insurance reserve fund. What taxpayers are getting in return for these fiscal risks as the Crown backstop is not stated.
  • At their peak in 2008, there were about 65 finance companies. Half of them failed inside of two years with no implications for the stability of the banking system. As the then Governor of the Reserve Bank reflected later in his book on his crisis management decision making about the finance companies:
  • At the end of 2006 and in early 2007, we started to hear about property finance companies in trouble. Most were very small, and as individual failures they did not greatly concern us. But in the second half of the 2007, bigger finance companies started to fall like flies. As each one entered into liquidation, receivership or moratorium, media speculation turned to the next. We saw angry scenes of elderly debenture holders haranguing hapless managers at meetings. The pattern seemed clear: poor governance, spider-web company structures, vulnerable business models, mismatched balance sheets, bad management and inadequate supervision by the trustee companies. At the Reserve Bank we started to worry: were the combined failures big enough to lead to a deposit run on the banks? The answer seemed to be no; in fact the banks were benefitting from a flight to quality. Did the failures point to fragile business models and practices in the banks themselves? Again, we thought not, the banks being much more sophisticated organisations than many finance companies (Bollard 2013).
  • The seven finance companies still in operation have $600 million in deposits and will have no role in future financial crises. The Governor of the Reserve Bank in 2008 dismissed the sector as a possible spark for bank runs. The finance company sector is now one-fifteenth of its size at the eve of the GFC.
  • There is no trade-off between moral hazard and better crisis management from deposit insurance for finance companies or for the other non-bank deposit takers. The Reserve Bank observed in its consultation paper that “… (building societies and credit unions) has shown an ability to manage distress in the sector through mergers and acquisitions”. Three building societies converted to banks in the last 15 years. In 2022 alone, the Firefighters Credit Union merged with NZCU Auckland, Westforce Credit Union merged with First Credit Union, and Steelsands Credit Union merged with First Credit Union. There are five credit unions left, down from 13 in 2018. The Unity Credit Union is the product of more than 10 mergers after starting in a freezing works in 1971. In the early 1980s, there were several hundred credit unions. There were no implications for the stability of banks from these many reorganisations among the non-bank deposit takers. The only policy issue is deposit insurance will encourage greater risk taking after the non-bank deposit takers are insured by the Crown.

The deposit insurance reserve fund and access to the lender of last resort function

  • The consultation papers from the Treasury and from the Reserve Bank barely allude to the access that banks have to the lender of last resort function at the Reserve Bank. This lender of last resort access greatly reduces the likelihood of the banks calling upon the deposit insurance offered by the Crown. The lender of last resort function duplicates much of the role of deposit insurance. Both policy tools assure jittery depositors that their bank balances are safe (Bordo 1990, Humphrey and Keleher 1984).
  • Most countries initially manage banks in distress through the lender of last resort function. The central bank lends to a bank in distress against good collateral at a high rate (Bordo 1990, 2018; Gorton and Metrick 2013). The Reserve Bank would help a bank through its difficulties while its loans are restructured and the bank perhaps recapitalised. Any risk from lending against compromised assets of the distressed bank is factored into the interest rate charged with the capital base of that bank acting as a buffer against further losses on a lender of last resort loan. No one suggests that finance companies or other non-bank deposit takers should have lender of last resort access.
  • Finance companies, credit unions and building societies have nowhere to go except the Crown deposit guarantee if things go bad. We will be writing separately to the Reserve Bank about how its consultation paper is also quiet on the interaction of the lender of last resort function and fair deposit insurance premiums. The deposit insurance premium to be paid by the banks should take account of their access to lender of last resort facilities. They can call on the lender of last resort function for help before they need to rely on payouts from the deposit insurance reserve fund.
  • A glaring anomaly in debates about deposit insurance is the tenacious stability of the Canadian banking system. The last bank failure, bar one, in Canada was in 1923; the 1923 bank failure was due to fraud (Bordo 1990; Bordo, Redish and Rockoff 2015). Canada’s banks sailed through the Great Depression and the GFC because it had large banks with diversified loan portfolios (Bordo and Redish 1987; Bordo, Redish and Rockoff 2015). Thousands of banks failed in the USA because they lacked a national branch networks and diversified loan portfolios (Calomiris and Jaremski 2016).
  • New Zealand also has five large banks with diversified loan portfolios. They are very unlikely to call on the deposit insurance reserve fund because any crisis is likely to be resolved through the lender of last resort function assisting with a bank recapitalisation. Twenty-three of the 27 registered banks listed in table A2 of the appendix to this letter and all the major banks in New Zealand have ‘A’ or ‘AA’ credit ratings. The ‘AA’ credit ratings imply a one chance in 300 of that bank failing in the next five years; the ‘A’ credit rating implies a probability of failure in the next five years of one chance in 150.
  • The policy trade-off regarding deposit insurance for banks is staving off bank runs while inviting banks to take on more risk in their lending. But failure is a far greater risk for US banks than for New Zealand banks. This is because the US still has thousands of small banks with less diversified loan portfolios (Calomiris 2008, 2011, 2013; Gorton and Winton 2003). The number of federally insured commercial banks in the US was 14,146 in 1934, 14,384 in 1975, 8,300 in 2000 and 4,377 in 2020. So many small banks in the US with few, if any branches, is why banking panics and bank runs are regarded as very much an American phenomenon in the economic literature. As Gorton and Winton (2003) explain:
  • On the basis of the stylized facts about cross-country banking history … it would seem straightforward to observe that banks are not fundamentally flawed institutions. In fact, it does not seem to be an exaggeration to say that most of the theoretical work on panics has been motivated by the USA experience, which has then been incorrectly generalized. Panics simply are not a feature of most economies that have banks. The world is more complicated; industrial organization seems to be at the center of the incidence of panics. Not surprisingly, therefore, almost all the empirical work on panics has been on the USA experience. Until bank “crises” around the world in the last ten years, there simply has not been much else to study (Gorton and Winton 2003, p. 508).
  • A British banking scholar would be likely to remember the names of each of their banks that failed over the last 200 years. North Rock is the only British bank to have failed since 1866. By contrast, banks fail every year in the USA. This includes the hundreds of bank failures during and after the GFC. A total of 1,617 federally insured banks failed between 1980 and 1994 (Hane 1998).
  • Non-bank deposit takers are a different story to our banks because they have much lower credit ratings and lack access to a lender of last resort facility. The B, BB and BBB credit ratings for non-bank deposit takers in table 1 several pages above represent a large break in default probabilities as compared to the A and AA ratings of banks. A BBB credit rating implies a default probability of one chance in 30 in the next five years. Liberty Finance Limited is the only finance company in table 1 above with such a credit rating. The BB ratings for two finance companies and for the three building societies in table 1 above imply a failure probability in the next five years of one in 10. The credit unions are not much better in financial strength. This high level of risk should be considered by the Minister when setting premiums to ensure the reserve fund is of sufficient size based on contributions from non-bank deposit takers to self-fund any payouts to any of the non-bank deposit takers that fail. Deposit insurance will be their first port of call in a crisis rather than the lender of last resort function.

Only banks should be as safe as a bank

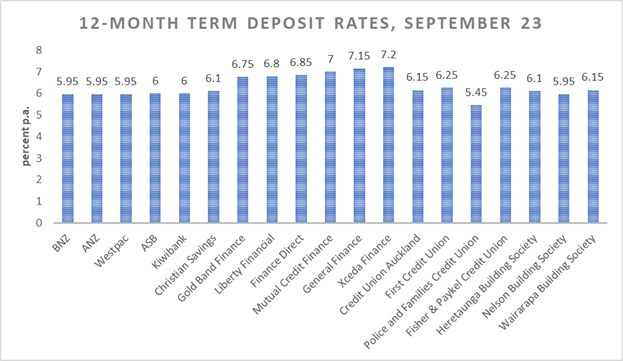
  • Given the local and overseas evidence just summarised, there is every reason to believe that the finance companies, in particular, and the building societies and credit unions will take advantage of Crown deposit insurance to tout themselves as ‘as safe as a bank’ to win more deposits. Currently, as shown in the chart below, finance companies must offer a risk premium of 75 to 120 basis points over the major banks to attract 12-month term deposits. Building societies and credit unions usually offer a 10 to 20 basis points more than the major banks for term deposits.

Source: web scrapings of deposit taker web sites

  • Gatti and Oliviero (2021) looked at what happened to the retail deposit interest rates of Eurozone banks after the European Union increased the minimum deposit insurance coverage for banks from €20,000 to €200,000 per bank account in 2009. Italian banks already had deposit insurance cover of €103,291. They found that compared to the Italian banks, the banks in the rest of the Eurozone reduced their interest rates by between 30 basis points and 70 basis points after they received more deposit insurance coverage. Gatti and Oliviero (2021) also found that the fall in deposit interest rates were largest among the riskier banks. There is every reason to believe that finance companies, in particular, and the credit unions and building societies in New Zealand will find it easier to attract deposits without having to offer as much as in the past in interest rates on deposits.

A deposit insurance reserve fund target fit for junk bonds

  • The record with the Crown deposit guarantee scheme between 2008 and 2011 and the overseas experience with changes in deposit insurance limits show conclusively that investors will run back into the sector because the finance companies, credit unions and building societies are once again provided with Crown deposit insurance. These deposit takers have a higher probability of default than the banks. They will draw down on the deposit insurance reserve fund that is to be mainly built up by the banks and this will constitute a cross-subsidy between groups with very different risk profiles. A fair deposit insurance premium for the finance company sector would be large given their previous experience with risky lending, with related party lending and exposure to real estate development.
  • Crown deposit insurance will encourage many retirees to re-enter the finance company sector. Who wouldn’t be tempted by higher returns for no extra risk because of the Crown deposit guarantee? A canny retiree would deposit $100,000 with each of the six finance companies to bet on a sure thing. The previous pages presented ample evidence that investors watch deposit interest rates keenly especially if higher but riskier returns that are government insured come on the market.
  • The funding approach to the reserve fund must take account of the likely rapid growth of the higher risk deposits takers. The reserve fund must build at a rate that will consider the possibility of an early call for compensation from a failing finance company, a failing building society or a failing credit union because of this rapid growth in their deposits and risky lending. The deposit insurance premium must be risk-based. This is a possibility subject to a separate consultation process by the Reserve Bank.
  • The Minister must choose the funding approach and fund size that reflects the likely more frequent calls from the non-bank deposit takers so there are no cross-subsidies between the banks and the other deposit takers. In addition to a risk-based deposit insurance premium, which is a must, the Minister should consider setting separate sub-targets for funds accumulated from deposit insurance premiums from the banks and for deposit premiums from the other deposit takers.
  • Separate targets should be set because banks are much less likely to call upon the deposit insurance reserve fund and the Crown backstop because of the lender of last resort facility. Non-bank deposit takers do not have this option in a crisis. Their credit ratings imply that they are also far more likely to fail than the banks. The range proposed for the size of the fund in the consultation paper by the Treasury of between 0.6% and 1.1% of insured deposits is not helpful because most of the calls on the deposit insurance reserve fund will come from non-bank deposit takers. Premiums from the non-bank deposit takers will be a small part of the funds accumulated but a large part of the payouts.

The severe deposit taker failure scenarios hint at a cross-subsidy

  • Table 4 of the consultation paper sets out the funding requirements for the deposit compensation scheme for severe but plausible failures scenarios for major banks, medium-sized banks and for the non-bank deposit takers sector. The failure scenario for the non-bank deposit takers sector is for
  • widespread liquidations requiring an upfront pay out to depositors of $800 million-$900 million. After recoveries, the likely cost of this scenario is estimated to be $100 million-$400 million.
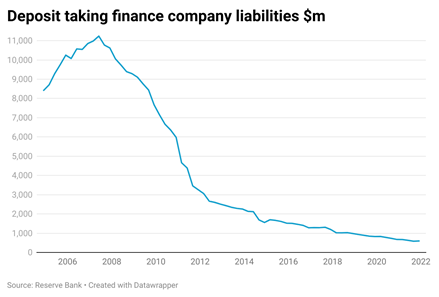
  • This payout scenario for the non-bank deposit takers before recoveries and after recoveries is far larger than any reasonable amount of premiums that could be accumulated from the non-bank deposit takers sector even over several decades. As can be seen from the chart below, deposits with the building societies and credit unions have been growing strongly in the last decade but are just $2 billion. The finance company sector is a shadow of its former self; a $9 billion peak in deposits in 2007. Their deposits are now $585 million, which is up 20% on their low two years ago in 2021.

 
Source: Reserve Bank at https://www.rbnz.govt.nz/statistics/series/non-banks-and-other-financial-institutions/deposit-taking-finance-companies-balance-sheet and https://www.rbnz.govt.nz/statistics/series/non-banks-and-other-financial-institutions/savings-institutions-balance-sheet
Notes: the three abrupt drops in building society/credit union deposits are due to the conversion of building societies into the Heartland, Cooperative and SBS banks. Data for finance companies appears to include FE Investments Ltd which entered receivership in March 2020 and Christian Savings Ltd.

  • The finance companies are unlikely to pay more than $3 million per year in deposit insurance premiums. The building societies and credit unions are unlikely to pay more than $10 million per year in deposit insurance premiums given the current levy framework out for consultation from the Reserve Bank. This premium income will take decades to accumulate to the level where these premiums could cover the failure scenarios discussed in the consultation paper from the Treasury.
  • Up until 2006, there were separate deposit insurance reserve funds in the USA for banks and for the other federally insured deposit takers. It is too late to have a similar structural separation in New Zealand now. But it is still possible to set separate accumulation sub-targets for premiums from non-bank deposit takers and premiums from banks and to have risk-based deposit insurance premiums.

No retreat from full funding by deposit takers of deposit insurance

  • The failure scenarios put forward by the Treasury consultation paper say that a failure of a major bank even after the target for the reserve fund is reached would often require a drawing on the Crown backstop. This is to fund the initial pay out depositors pending partial or full repayment to the Crown through recoveries. Taxpayers will pay part of the initial cost of the resolution of a large bank failure.
  • Deposit insurance is supposed to be self-funding through levies on deposit takers. The Minister of Finance reiterated this government policy when the Deposit Takers Bill passed Parliament. The Treasury has given up on this important safeguard for taxpayers at the first turn. Calls on the Crown backstop to the deposit insurance scheme should be limited to the rarest of rare major bank failures.

Setting deposit insurance premiums to target deposit insurance fund reserves

  • We will be writing to the Reserve Bank to point out that the effect of setting deposit insurance premiums to have a reserve fund target has the effect of ruling out the possibility of risk-based deposit insurance. This is because the any decision to stop collecting premiums once the target is reached means that the deposit insurance is no longer risk-based. It is free. As Feldman explains:
  • The policy of setting premiums based on the size of current reserves prevents, almost by definition, the setting of actuarially fair premiums. Reserves are backward looking, informing policymakers about past premiums and past payments to the insured. In contrast, the setting of fair premiums is an exercise in forecasting future losses that may not reflect what happened last year or the year before that. In this case, the FDIC (Federal Deposit Insurance Corporation) must currently give away insurance to the vast majority of banks because reserves exceed the targeted level. As a result, the FDIC essentially charges banks one flat rate for deposit insurance just as it did over the vast majority of its history, even though Congress ostensibly required premiums to vary by the risk of a bank failing in 1991 (Feldman 1998).
  • George Pennacchi (1987, 2000, 2006, 2010) has written extensively on the interaction between deposit insurance premiums and targets for deposit insurance reserve funds. He argues that:
  • Conventional economic theory maintains that a fairly priced deposit insurance for default-risk premium should reflect the current financial risk of the issuing institution. In particular, a fair premium should not be dependent directly on the past losses sustained by the insurer and, therefore, should not bear any direct relationship to the reserves of the insurance fund. From this perspective, it is puzzling that most insurance systems choose not to set fair insurance rates but set either flat rate premiums or premiums that target a fund’s reserves (Pennacchi 2000, p. 154).
  • Setting a deposit insurance fund reserves target is fundamentally inconsistent with setting a risk-based deposit insurance premiums for deposit takers for the insurance provided by the Crown. For example, from 1991, the US Congress experimented with having both risk-based deposit insurance premiums and a target for their deposit insurance fund. This meant no further premiums were collected once the insurance fund reserves reached a target of 1.25% of insured deposits. That target was soon reached in 1995. No federal deposit insurance premiums were charged to almost all US banks in the 12 years leading up to the global financial crisis (Pennacchi 2010). That is hardly ideal in terms of encouraging banks to have regard for the risks in their portfolios and depositors to be wary of risky banks offering above-average returns on their deposits. Taxpayers will be very wary of having a target for the deposit insurance reserve fund because it turns into free deposit insurance once that target is reached.

Systemic risk and the deposit insurance reserve fund target

  • Deposit insurance is not like other deposit insurance where risk arising from individual policy claims can be diversified by underwriting many policies as the risks are largely independent of each other.
  • Most claims on deposit insurance will arise during recessions. Furthermore, the ability to recover deposit insurance payouts through sale of a distressed bank’s loans is more difficult during recessions because the real estate and other collateral offered by borrowers is also depressed in price. Therefore, deposit insurance losses are not diversifiable, they are systemic. As Pennacchi explains:
  • The risks from underwriting multiple term life insurance policies or automobile collision policies can be diversified away by pooling the risks of several policies together. This is not the case for deposit insurance. The risks of deposit insurance losses due to bank failures cannot be diversified away by pooling the risks of many banks together because deposit insurance loss claims are not independent or uncorrelated events. Bank failures are linked to macroeconomic conditions which tend to create financial distress at many banks at the same time. This is not surprising since bank assets consist largely of real estate, commercial, and consumer loans which experience higher default rates during economic downturns. Thus, bank failures and deposit insurance losses rise during recessions and decline during expansions, so that they bear ‘systematic’ risk (Pennacchi 2010).
  • Deposit insurance requires the Crown to take onto its portfolio business cycle risk from bank and non-bank deposit takers. It is not such as is the case with car insurance where the insurer gets a small profit or loss on his portfolio of policies. A deposit insurance fund should earn positive profits in the long-run as a premium for taking on business cycle or systemic risk. As Pennacchi explains:
  • In terms of the Capital Asset Pricing Model (CAPM), underwriting deposit insurance is a positive ‘beta’ investment: during economic expansions (recessions) when stock market returns are high (low), a deposit insurer will make profits (losses) because premiums will be greater (less) than loss claims from bank failures. Thus, to compensate an insurer for the risk that losses will be highest during severe recessions, fair premiums must exceed expected losses. In other words, fair market deposit insurance premiums will contain a systematic risk premium in addition to expected losses so that a deposit insurer charging fair premiums will earn positive average profits (Pennacchi 2010).
  • The deposit insurance premium that includes systemic risk in the premium means that the deposit insurance fund should grow indefinitely and indeed would have the capacity to pay a dividend to the Crown in recompense for taxpayers taking on systemic risk (Pennacchi 2000, 2006, 2010).
  • Setting a target for the reserve fund and then charging no further premiums is a subsidy to deposit takers. It is the taking on of significant systemic risk or business cycle risk onto the Crown portfolio. This is because most of the losses, and especially in the case of non-bank deposit takers, from deposit insurance is from systemic risk from the business cycle (Jokivuolle and Pennacchi 2019).

Lessons from recent bank runs overseas

  • There is no mention in the Treasury and Reserve Bank consultation documents of the bank runs in the USA and Switzerland or the pressures on all banks around the world from the recent large increases in inflation rates and nominal interest rates. Banks everywhere are suffering losses on their large long-term bond holdings, which they bought at ultra-low interest rates.
  • Silicon Valley Bank tripled in size from the end of 2019 to the end of 2021 to have $200 billion in deposits. It invested mostly in long-term US Treasury bonds, mortgage-backed bonds, and municipal bonds. More than 90% of its at-demand deposits were not federally insured because of the large balances of most of its customers. Silicon Valley Bank was paying more than the other banks in interest on deposits because it was not hedging its interest rate risk. The Federal Reserve Bank of San Francisco expressed concerns about this with the Silicon Valley Bank but did not mandate corrective action.
  • The Silicon Valley Bank was heavily exposed to a mismatch in duration in its portfolio and had an unusually large share of uninsured deposits. Silicon Valley Bank made unhedged bets that interest rates would stay very low for a long time (which was the Fed’s forward guidance at the time). It did not help that central banks everywhere said that the current inflationary burst was transitory driven by Covid-19 supply change disruptions that would soon subside and may even reverse themselves rather than from the expansionary monetary policy choices of those central banks in 2020 and after.
  • The bank run started after Silicon Valley Bank announced on Thursday 8 March that it sold $21 billion in long-term securities for a loss of $1.8 billion. $42 billion in withdrawals were made the next day. $100 billion in withdrawals were sought the following day which the bank could not honour. The California State regulator put the bank into receivership with deposits guaranteed to the federal limit.
  • Over the weekend, the Federal Deposit Insurance Corporation bailed-out all deposits at the Silicon Valley Bank and the Signature Bank and not just those up to the $250,000 federal deposit insurance limit. The Federal Deposit Insurance Corporation took over these banks and bailed them out to stem national and global financial jitters. For example, after a run on its deposits, the scandal plagued Credit Suisse was taken over by UBS in a rescue underwritten by the Swiss central bank. In 2007, Credit Suisse was worth 100 billion Swiss francs (SFr). On 19 March 2023, UBS bought it for SFr3 billion.
  • When announcing the blanket deposit guarantee for the Signature bank, the Silicon Valley Bank and two other foundering banks, the Federal authorities strongly hinted that that a deposit guarantee would be extended to other banks if such action was necessary to stabilise the banking system.

Have we got this covered?

  • None of these bank runs overseas are mentioned in the consultation documents with lessons for NZ. Taxpayers don’t know whether the deposit insurance being rolled out and our prudential regulation are robust to the forces behind the recent overseas bank runs! There is no evidence that the Treasury or the Reserve Bank have paused to consider these developments when rolling out deposit insurance.
  • At a minimum, these bank runs against major global banks should have led the Treasury to consider a larger target fund to be accumulated perhaps over a longer time-period such as 30+ years. After the 30 years, the Minister of Finance can then decide on the wisdom of waiving in part or in full further deposit insurance levies because the deposit insurance fund has finally reached its target.
  • The overseas banks collapsed because of a basic failure to hedge portfolios made up of large uninsured at-demand deposits and mostly long-term securities purchased at ultra-low interest rates. The Crown deposit insurance fund might need to be bigger than is currently planned in the consultation document to fortify it against a similar interest rate risk pushing a local bank into distress.
  • Taxpayers deserve to know whether the Crown deposit compensation fund is robust to the interest rate risk behind the bank runs abroad and that the Treasury and Reserve Bank can adapt the implementation of Crown deposit insurance to events. All of the banks overseas subject to bank runs were in compliance with their regulatory standards until the day before they collapsed.

Polar opposite models of deposit insurance

  1. Another lesson for New Zealand from the recent bank runs overseas is the primary intellectual framework of policymakers at least in the USA is based on Bryant (1980) and Diamond and Dybvig (1983) models of bank runs. Banks have a maturity mismatch in their balance sheets, which Bryant (1980) and Diamond and Dybvig (1983) say is to blame for bank runs. Deposits are payable on demand, but most of these deposits finance long-term loans.
  2. Diamond and Dybvig (1983) argued that if too many depositors suddenly seek to withdraw, the bank will run out of cash despite being solvent. In a run, depositors are not reacting to news about the quality of the bank’s portfolio. Instead, they are withdrawing because they see others doing so and do not want to be left with a deposit in a bank with no cash reserves. The otherwise solvent bank then fails because a depositor panic forces the bank to sell good assets in a fire-sale.
  3. Importantly, in the Diamond-Dybvig (1983) model of bank panics, if there is government-supplied deposit insurance, depositors do not start bank runs because they trust that their deposits are safely insured by the taxpayer. The icing on the cake is that the deposit insurance under this Diamond-Dybvig scenario of bank runs costs the taxpayers nothing because there are no bank panics to stem.
  4. During the GFC, many governments seemed to see Diamond and Dybvig type panic-based bank runs everywhere and used deposit guarantees to quell the panic. As Thomas Sargent observed:
  5. When monetary policy authorities, deposit insurance authorities and others looked out their windows in the fall of 2008, they saw Bryant-Diamond-Dybvig bank runs all over the place. And the logic of the Bryant-Diamond-Dybvig model persuaded them that if they could arrest the runs by effectively convincing creditors that their loans—that is, their short-term deposits—to these “banks” were insured, that could be done at little or no eventual cost to the taxpayers. You could nip the run in the bud and really prevent the next Great Depression. This is a very optimistic view of those 2008 interventions enlightened by the Bryant and Diamond-Dybvig model (Rolick 2010).
  6. Diamond and Dybvig were well-aware of the risk of moral hazard. They recommended a 1978 paper by Kareken and Wallace on deposit insurance. That paper was about what the Diamond and Dybvig model left out: moral hazard. Sargent summarises the Kareken and Wallace modelling as follows:
  7. Kareken and Wallace compare that no-deposit-insurance situation to another situation in which a government agency provides deposit insurance that is either free or is priced too cheaply, meaning that it’s not priced with a proper risk-loading. Kareken and Wallace show that in that situation, banks have an incentive to become as risky as possible, and as large as possible. Therefore, with a positive probability, banks will fail and taxpayers will have to compensate banks’ depositors. It is in banks’ shareholders’ interest that the banks organize themselves this way. This lets them gamble with the insurers’ and depositors’ money. The Kareken and Wallace model’s prediction is that if a government sets up deposit insurance and doesn’t regulate bank portfolios to prevent them from taking too much risk, the government is setting the stage for a financial crisis (Rolick 2010).
  8. In the Kareken and Wallace (1978) model, deposit insurance encourages risk-taking and crises unless bank portfolios are successfully regulated. The literature on regulation of bank portfolios is one of profound subtlety, where the correct amount of capital that banks must hold is subject to intense debate (Aiyar, Calomiris and Wieladek 2015). The spotty record of regulators before the GFC also throws doubt on their ability to do better next time (Calomiris 2011, 2013). It is still debated as to whether the regulatory response to the GFC made things worse rather than better (Tarullo 2019).
  9. The consultation papers by the Reserve Bank and the Treasury are silent on the recent bank runs overseas and soundness of the intellectual framework behind the policy responses to them. The consultation documents also missed the biggest lesson from the policy response to those bank runs.

Implied bank deposit guarantees

  • The big depositors in the Silicon Valley Bank won their bet. Despite a balance sheet at the Silicon Valley Bank and the other banks that went into receivership that showed tens of billions of dollars in unrealised losses on long-term securities, they could regard their bank balances of whatever amount as safe because there is an implied deposit guarantee by the Federal authorities. This will be forthcoming in a bank crisis especially if there is a high-profile bank run. The other US banks that have mismatched portfolios were equally successful in their betting about an implied deposit guarantee.
  • This triggering of an implied deposit guarantee for all depositors is what happened in New Zealand at the height of the global financial crisis when a choice had to be made, and it may have been for the best. The Crown guaranteed all retail and wholesale bank deposits for two years in return for a 1% fee to calm market jitters. The government in 2008 also made the unfortunate decision, very much as an afterthought to guarantee deposits with finance companies.

Different models for different deposit takers

  • Diamond and Dybvig (1983) was the relevant intellectual framework for banks and the calming of market jitters and the potential for bank panics in 2008. The Kareken and Wallace (1978) model of deposit insurance and moral hazard was the relevant framework for finance companies but was ignored in 2008 and has been ignored again with the Deposit Takers Act 2023.
  • For the rollout of deposit insurance in New Zealand, the Diamond and Dybvig (1983) model is the relevant intellectual framework for preventing bank panics. An illiquid but solvent bank can avoid failure by borrowing from the lender of last resort facility. The lender of last resort facility, a deposit insurance payout and a bank recapitalisation are the likely responses to an insolvent bank.
  • The Kareken and Wallace (1978) model of deposit insurance and moral hazard is the relevant intellectual model for insuring the non-bank deposit takers. The Treasury’s consultation paper does not draw out this intellectual framework for understanding the large risks that are to be taken on to the Crown portfolio from insuring the non-bank deposit takers as well as the banks.

Conclusions

  • Crown deposit insurance is to be offered to a mixed bag. The AA and A credit ratings for the banks imply a remote probability of default. The credit ratings for the non-bank deposit takers often imply a default probability of one chance in 10 in the next five years. Too many of these non-bank deposit takers have what are in effect junk bond credit ratings. The consultation papers by the Treasury and from the Reserve Bank do not make this fiscal risk from deposit insurance clear.
  • The target for the deposit insurance reserve fund should accept that most of the calls on its funds will be from the non-bank deposit takers. The consultation papers by the Treasury and Reserve Bank do not make this fiscal risk to taxpayers from deposit insurance clear.
  • The Minister should consider adopting sub-targets for premiums collected from banks and for premiums collected from non-bank deposit takers to make transparent the level of coverage to each sector and when payouts on deposit insurance constitute a cross-subsidy. Cross-subsidies between different types of deposit takers should be kept to a minimum, and risk-based pricing for deposit insurance is an essential protection for taxpayers and the public purse.
  • Indeed, we prefer that there should not be a target for the deposit insurance reserve fund. Such a target rules out risk-based deposit insurance premiums. Once the target is reached, no further premiums are charged so the deposit insurance is free which encourages risk-taking by deposit takers.
  • There is every reason to believe that investors will move back into the non-bank deposit taking sector because deposit insurance will remove any need for concerns about the solvency of non-bank deposit takers as long as they keep their deposits with any one institution at no more than $100,000. Non-bank deposit takers will be encouraged to take more risks in their lending because their depositors will not penalise them by going elsewhere unless an additional risk premium is offered.
  • The recent bank runs overseas illustrate how difficult it is for governments to not cave-in to public pressures about implied guarantees for all deposits with banks and for banks to be bailed-out despite taking excessive risks in their lending and in their securities portfolio management.
  • None of the bank runs overseas are mentioned in the consultation documents. We don’t know whether the deposit insurance being rolled out for NZ and our prudential regulation are robust to the interest rate risk behind the recent bank runs overseas! There is no evidence that the Treasury or the Reserve Bank have paused to consider these recent major policy developments overseas.

Yours sincerely,
New Zealand Taxpayers’ Union Inc.

Jim Rose

Jim Rose
Research Fellow
Jim@taxpayers.org.nz

References

Aiyar, Shekhar & Charles W Calomiris & Tomasz Wieladek, 2015. “Bank Capital Regulation: Theory, Empirics, and Policy,” IMF Economic Review vol. 63 (4), pp. 955-983, November.

Allen, Franklin, Elena Carletti, Itay Goldstein and Agnese Leonello 2018. “Government guarantees and financial stability”. Journal of Economic Theory, Vol 177 pp. 518-557.

Anginer, Deniz and Demirgüç-Kunt, Asli and Zhu, Min, “How Does Deposit Insurance Affect Bank Risk? Evidence from the Recent Crisis”, Journal of Banking & Finance, 2014, vol. 48, issue C, 312-321.

Atmaca, S, K Kirschenmann, S Ongena and K Schoors (2020), “Deposit insurance, bank ownership and depositor behavior”, CEPR Discussion Paper 15547.

Auditor-General 2011. The Treasury: Implementing and managing the Crown Retail Deposit Guarantee Scheme. Office of the Auditor-General, Wellington.

Bollard, Alan and Sarah Gaitanos, Crisis: One Central Bank Governor & the Global Financial Collapse. Auckland University Press (2013).

Bordo, Michael D. “The Lender of Last Resort: Alternative Views and Historical Experience.” Economic Review (Federal Reserve Bank of Richmond), Vol. 76/1, pp. 18-29, (January/February 1990).

Bordo, Michael D. 2018. “An Historical Perspective on the Quest for Financial Stability and the Monetary Policy Regime,” The Journal of Economic History, vol 78(2), pp. 319-357.

Bordo, Michael D., and Angela Redish. “Why did the Bank of Canada Emerge in 1935?” Journal of Economic History, Vol. XLVII, No. 2, June 1987, pp. 405-417.

Bordo, Michael D., Angela Redish and Hugh Rockoff, 2015. “Why didn’t Canada have a banking crisis in 2008 (or in 1930, or 1907, or …)?,” The Economic History Review, vol 68 (1), pp. 218-243.

Bryant, John. 1980. “A Model of Reserves, Bank Runs, and Deposit Insurance. Journal of Banking & Finance 4(4), pp. 335–44.

Calomiris, Charles W., “Banking Crises,” In New Palgrave Dictionary of Economics, 2nd Edition, edited by Steven Durlauf and Lawrence Blume, 2009.

Calomiris, Charles W., “Banking crises yesterday and today,” Financial History Review, Cambridge University Press, vol. 17 (1), pp. 3-12, April 2010.

Calomiris, Charles W., “Banking Crises and the Rules of the Game,” In Monetary and Banking History: Essays in Honour of Forrest Capie, edited by Geoffrey Wood, Terence Mills, and Nicholas Crafts, Routledge, 2011, pp. 88-132.

Calomiris, Charles W., “Banking Fragility of the United States, 1790-2009”. In Handbook of Key Global Financial Markets, Institutions, and Infrastructure, edited by Gerard Caprio, Charles W. Calomiris, and Larry Neal. London: Elsevier Press, 2013.

Calomiris, Charles W. and Matthew Jaremski, 2016. “Deposit Insurance: Theories and Facts,” Annual Review of Financial Economics, vol. 8(1), pages 97-120, October.

Calomiris, Charles W. and Matthew Jaremski, “Stealing Deposits: Deposit Insurance, Risk-Taking, and the Removal of Market Discipline in Early 20-Century Banks.” The Journal of Finance 74, no. 2 (2019): 711–54.

Diamond, Douglas W., and Philip H. Dybvig. 1983. “Bank Runs, Deposit Insurance, and Liquidity.” Journal of Political Economy 91(3), pp. 401–19.

Feldman, R., “When should the FDIC act like a private insurance company?” Federal Reserve Bank of Minneapolis at https://www.minneapolisfed.org/article/1998/when-should-the-fdic-act-like-a-private-insurance-company

Gorton, Gary., and Andrew Winton. “Financial Intermediation”. In Constantinides, George, Milton Harris, and Rene Stulz (eds). The Handbook of the Economics of Finance Elsevier Science, 2003 pp 431-552.

Gropp, Reint., Christian Gruendl, and Andre Guettler. “The Impact of Public Guarantees on Bank Risk-Taking: Evidence from a Natural Experiment”. Review of Finance, Volume 18, Issue 2, April 2014, pp. 457–488.

Hane, George. “The Banking Crises of the 1980s and Early 1990s: Summary and Implications”. FDIC Banking Review, 1998 Vol. 11, No. 1, pp. 1-21.

Humphrey, Thomas H., and Robert E. Keleher, “The Lender of Last Resort; A Historical Perspective”, Cato Journal, 1984, vol. 4, issue 1, 275-321

Iyer R., Jensen, TL., Johannesen, N., and Sheridan, A. 2019. “The distortive effects of too-big-to-fail: evidence from the Danish market for retail deposits”, The Review of Financial Studies, Vol:32, pp. 4653-4695.

Jokivuolle, Esa & George Pennacchi, 2019. “Designing a Multinational Deposit Insurance System: Implications for the European Deposit Insurance Scheme,” ifo DICE Report, ifo Institute – Leibniz Institute for Economic Research at the University of Munich, vol. 17(01), pages 21-25, May.

Kareken, John H., and Neil Wallace. 1978. “Deposit Insurance and Bank Regulation: A Partial-Equilibrium Exposition.” Journal of Business 51 (July), pp. 413–38.

Lambert, C., F. Noth, and U. Schüwer (2014). “How do insured deposits affect bank risk? Evidence from the 2008 Emergency Economic Stabilization Act. Journal of Financial Intermediation 29 (October), pp. 81–102.

Martin, Christopher., Manju Puri and Alexander Ufier, 2018. “Deposit Inflows and Outflows in Failing Banks: The Role of Deposit Insurance,” NBER Working Papers 24589, National Bureau of Economic Research.

O’Sullivan, Fran. “Vital witness missing at SCF trial”. New Zealand Herald, 15 October 2014.

Pennacchi, George G. “A Reexamination of the Over- (or Under-) Pricing of Deposit Insurance.” Journal of Money, Credit and Banking 19, no. 3 (1987): 340–60.

Pennacchi, George G. “Deposit insurance, bank regulation, and financial system risks”, Journal of Monetary Economics, 2006, vol. 53, issue 1, 1-30.

Pennacchi, George G (2010), “Deposit Insurance Reform” in J Brown (ed.), Public Insurance and Private Markets, AEI Press.

Pennacchi, George G. (2000), “The Effects of Setting Deposit Insurance Premiums to Target Insurance Fund Reserves”, Journal of Financial Services Research 17, 153-180.

Rolick, A., 2010. “Interview with Thomas Sargent”. The Region, Federal Bank of Minneapolis, vol. 24, issue Sep, pp. 26-39.

Tarullo, Daniel K. “Financial Regulation: Still Unsettled a Decade After the Crisis.” The Journal of Economic Perspectives 33, no. 1 (2019): 61–80.

Wheelock, David C. “Regulation and Bank Failures: New Evidence from the Agricultural Collapse of the 1920s.” The Journal of Economic History 52, no. 4 (1992): 806–25.

Wheelock, David C., and Subal C. Kumbhakar. “Which Banks Choose Deposit Insurance? Evidence of Adverse Selection and Moral Hazard in a Voluntary Insurance System.” Journal of Money, Credit and Banking 27, no. 1 (1995): 186–201.

Wheelock, David C. & Paul W. Wilson, 1994. “Can deposit insurance increase the risk of bank failure? Some historical evidence,” Review, Federal Reserve Bank of St. Louis, May, pages 57-71.

Wheelock, David C., and Paul W. Wilson. “Explaining Bank Failures: Deposit Insurance, Regulation, and Efficiency.” The Review of Economics and Statistics 77, no. 4 (1995): 689–700.

Appendix

Table A1 Standardised credit rating agency rating scale

 Description S&P ScaleMoody’s ScaleFitch Scale  Approx probability of default over 5 years*
Capacity to make timely paymentExtremely strongAAAAaaAAA1 in 600
Capacity to make timely paymentVery strongAAAaAA1 in 300
Capacity to make timely paymentStrongAAA1 in 150
Capacity to make timely paymentAdequateBBBBaaBBB1 in 30
Vulnerability to non-paymentLess vulnerableBBBaBB1 in 10
Vulnerability to non-paymentMore vulnerableBBB1 in 5
Vulnerability to non-paymentCurrently vulnerableCCCCaaCCC1 in 2
Vulnerability to non-paymentCurrently highly vulnerableCC CC 
Vulnerability to non-paymentDefaultDCD 

Source: Reserve Bank at https://www.rbnz.govt.nz/regulation-and-supervision/oversight-of-banks/standards-and-requirements-for-banks/bank-credit-ratings

* The approximate, median likelihood that an investor will not receive repayment on a five-year investment on time and in full based upon historical default rates published by each agency

Table A2: Banks currently registered in New Zealand

Name of registered bankCredit rating agency & rating
 Standard & Poor’sFitchMoody’s
ANZ Bank New Zealand Ltd AA- A+ A1
ASB Bank Limited AA- A+A1 
Australia and New Zealand Banking Group Limited (B) AA- A+Aa3 
Bank of Baroda (New Zealand) Limited – BBB- –
Bank of China Limited (B) A AA1
Bank of China (New Zealand) Limited A–A1
Bank of India (New Zealand) Limited–BBB-–
Bank of New ZealandAA-A+A1
China Construction Bank Corporation (B)AAA1
China Construction Bank (New Zealand) Limited–AA1
Citibank N A (B)A+A+Aa3
Commonwealth Bank of Australia (B)AA-A+Aa3
Heartland Bank Limited–BBB–
Industrial and Commercial Bank of China (New Zealand) LimitedA–A1
Industrial and Commercial Bank of China Limited (B)A–A1
JPMorgan Chase Bank NA (B)A+AAAa2
Kiwibank Limited–AAA1
Kookmin Bank (B)A+AAa3
MUFG Bank, Ltd (B)AA-A1
Cooperative Rabobank U.A. trading as Rabobank Nederland (B)A+A+Aa2
Rabobank New Zealand LimitedA––
Southland Building Society –BBB–
The Co-operative Bank Limited–BBB–
The Hongkong and Shanghai Banking Corporation Limited (B)AA-AA-Aa3
TSB Bank Limited–A-–
Westpac Banking Corporation (B)AA-A+Aa3
Westpac New Zealand LimitedAA-A+A1

Source: Reserve Bank at https://www.rbnz.govt.nz/regulation-and-supervision/cross-sector-oversight/registers-of-entities-we-regulate/registered-banks-in-new-zealand

Note: Banks marked (B) operate in New Zealand as branches of overseas-incorporated banks. All other banks are incorporated in New Zealand.

Sargent on moderate inflations

An Investor’s Introduction to Austrian Economics (by Murray N. Rothbard)

Sargent on hyperinflation

Friedman on fiscal policy

Scott Freeman and the AI boom and possible initial slowdown

@TaxpayersUnion 2022 Submission opposing deposit insurance for finance companies @GeorgeSelgin

8 November 2022

Committee Secretariat
Finance and Expenditure Select Committee
Parliament Buildings
Wellington

SUBMISSION ON THE DEPOSIT TAKERS BILL: NO DEPOSIT INSURANCE FOR FINANCE COMPANIES

About the Submitter

This submission has been prepared for the New Zealand Taxpayers’ Union by Research Fellow Jim Rose. Jim is an economist with three decades’ experience in the public sector in New Zealand and Australia. He has worked at the Ministry of Business, Innovation and Employment, the Department of Labour, the Ministry of Social Development, and the New Zealand Treasury, and in Canberra for the Productivity Commission, the Department of Prime Minister and Cabinet, and the Department of Finance. Jim has a master’s degree in economics from the Australian National University and a master’s degree in public policy from the National Graduate Institute for Policy Studies in Tokyo.

Founded by David Farrar and Jordan Williams in 2013, the Taxpayers’ Union’s mission is Lower Taxes, Less Waste, More Transparency.

We enjoy the support of some 200,000 registered members and supporters, making us the most popular campaign group championing fiscal conservatism and transparency.  We are funded by our thousands of donors and approximately three percent of our income is from membership dues and donations from private industry.

We are a lobby group not a think tank.  Our grassroots advocacy model is based on international taxpayer-group counterparts, particularly in the United Kingdom and Canada, and similar to campaign organisations on the left, such as Australia’s Get Up, New Zealand’s ActionStation, and Greenpeace. 

The Union is a member of the World Taxpayers Associations – a coalition of taxpayer advocacy groups representing millions of taxpayers across more than 60 countries. 

We give permission for the Select Committee to publish this submission.

We wish to speak to this submission in front of the Committee.

Scope of submission

This submission on behalf the Taxpayers’ Union is limited to opposing the proposal in the Deposit Takers Bill to offer $100,000 in Crown deposit insurance per depositor per institution to deposit-taking finance companies. There will, however, be a short discussion on the insurance premium that deposit takers such as banks, finance companies, credit unions, and building societies will have to pay for their Crown deposit insurance.

This submission builds on a letter on behalf of the Taxpayers’ Union to the Minister of Finance in late 2020 and a submission to the public consultation on the draft Deposit Takers Bill last year. The Taxpayers’ Union met with the Treasury and Reserve Bank in October 2020.

Executive summary

We submit that implementing deposit insurance for finance companies would be a short-sighted policy and must be considered a policy option distinct from deposit insurance only for banks.

  1. Deposit insurance is a high-stakes trade-off between quelling depositor panic during a banking crisis and seeding that crisis by encouraging insured banks to take more risk in their lending.
  2. Finance companies now account for a tiny share of deposit-taking institutions. The Crown deposit guarantee put in place for finance companies at the height of the GFC was of dubious value, even with their twenty times larger than now share of the deposit-taking market in 2008. The finance company sector has shrunk by 95 percent since the height of the GFC.
  3. Reasonable people can disagree over the Crown insuring deposits in banks but not so for the finance companies because they mostly have junk bond credit ratings and is a sector with a history that is plagued by scandal and Serious Fraud Office investigations.
  4. Deposit insurance for finance companies should be removed from the Bill because retirees will flood back into the sector chasing the higher Crown insured risky investment returns. This risk of a resurgent finance company sector underwritten by taxpayers and the many other risks and shortcomings discussed in this submission were not mentioned, much less addressed in the consultation papers issued by the Reserve Bank and the Treasury.

Finance companies are inherently riskier

The Auditor-General’s 2011 report goes unremembered

The previous Crown deposit guarantee scheme is barely mentioned in the thousands of pages sent to the Minister and the Cabinet as part of the review of the Reserve Bank legislation. This is especially disappointing considering the highly critical remarks in the Auditor-General’s 2011 review of the implementation of the 2008-2011 Crown retail deposit guarantee scheme by the Treasury.

Now as then, the Treasury and the Reserve Bank appear to be aloof to the mercurial nature of deposit insurance as a policy instrument. It can bite back at the taxpayer big time as the 2008-2011 scheme certainly did. The proposed deposit guarantee has not been jumbled together in a few days as was the guarantee cobbled together at the height of the GFC. This reincarnation is years in the making.

The Auditor-General’s 2011 review found that the Treasury was focused on how to pay out depositors with little regard to how to reduce risk to the Crown by offering deposit insurance to failing finance companies. Indeed, the Crown deposit guarantee was renewed for South Canterbury Finance despite the Treasury having concluded at the time that the finance company was likely to fail.

The Treasury received the inspector’s report on 17 July 2009. The report reaffirmed the seriousness of the risk factors suspected with the books and management of South Canterbury Finance. From April to August 2009, the Treasury investigated the affairs of South Canterbury Finance extensively. On 12 August 2009, the Treasury made a provision for the estimated loss if South Canterbury Finance failed. This provision reflected the Treasury’s judgment that South Canterbury Finance was more likely than not to fail. The provision was made with the benefit of the inspector’s report (Auditor-General 2011, p.103).

Would a fair deposit insurance premium towards the end be perhaps up to one-half of South Canterbury Finance’s deposits under a Crown guarantee? To quote the Audit report again:

The Treasury’s monthly financial statements did not include any provisions for pay-outs under the Scheme until June 2009, when the provision was estimated at $0.8 billion. The Treasury knew before June 2009 that further failures of finance companies were likely, so this information should have been better reflected in the monthly financial statements earlier than June 2009 (Auditor-General 2011, p.94).

About $1.6 billion of the $2 billion in initial losses to the Crown from the deposit guarantee scheme was from the failure of South Canterbury Finance. The Treasury didn’t face up to the facts as early as it should have with the 2008-2011 Crown deposit guarantee to finance companies. History is repeating.

Deposits flooded into finance companies off the back of the 2008 Crown guarantee

After bleeding money in 2007 and 2008, there is a surge in deposits after the 2008 Crown guarantee for finance companies, as in the chart below from the report by the Auditor-General (2011). South Canterbury Finance grew by 25% in deposits after the Crown guarantee (Auditor-General 2011); deposits in South Canterbury Finance increased from $75 million in 2004 to $2 billion in 2008 (O’Sullivan 2015); another company grew from $800,000 in deposits to $8 million in deposits off the back of the Crown retail deposit guarantee (Auditor-General, 2011).
There is no discussion in the Treasury and Reserve Bank papers of the implications of the guarantee for a resurgence of investor interest in what is an intrinsically riskier sector. There is no mention in the Reserve Bank and Treasury review papers of the massive surge in investment in finance companies after the 2008 Crown retail deposit guarantee, as shown in the above chart from the report by the Auditor-General. Instead of bleeding $500 million every quarter as in the lead up to the GFC, $600 million flooded back into the sector off the back of the Crown retail deposit guarantee.

Depositors chase riskier returns when government insured

The proposition that depositors will invest in higher risk returns if they are government insured is well-established. The burst of deposits back into the finance company sector after the government guarantee in New Zealand is not an anomaly to be dismissed. Instead, a resurgence in growth in the finance company sector is inevitable if the Bill continues to include deposit insurance for the sector.

Martin, Puri, and Ufier (2018) examined the daily account level balances of a distressed bank in the USA at the height of the GFC. They studied the outflow (bank run-off) of uninsured depositors and the inflow (bank run-in) of insured deposits as this bank was in its death throes. The maximum level of federal deposit insurance increased from $100,000 to $250,000 per account holder as a stabilisation measure at the height of the GFC in 2008.

Martin, Puri, and Ufier (2018) found that this failing bank was able to replace about 1/3rd of its depositor base in its last year of life, despite public knowledge of the intensive regulatory scrutiny of its declining condition. Much of these new deposits came in in the last 90 days of the bank. The bank’s regulatory filings spoke of being significantly under-capitalised and then being critically under-capitalised. The new deposits were almost all term deposits paying slightly above market interest rates and were just under the Federal Deposit Insurance Corporation insurance limit. These deposits initially bunched at the $100,000 dollar limit, then bunched at the $250,000 insurance limit when this limit was increased at the height of the GFC in October 2008.

Iyer, Jensen, Johannesen and Sheridan (2019) had access to all personal deposit accounts and their balances in Denmark when they studied changes in deposit insurance for Danish banks. The Danish government guaranteed all bank liabilities in 2008. Prior to the GFC, deposit insurance was limited to 300,000 Danish kroner. The Danish government later limited deposit insurance to 750,000 Danish kroner in 2011. The Danish government also named six Danish banks as too big to fail.

Iyer, Jensen, Johannesen and Sheridan (2019) found that for the banks that were not too big to fail, accounts clustered around the insurance limit of 750,000 Danish kroner. There was no similar bunching of deposits at the deposit insurance limit for the six large banks deemed by the Danish Government to be too big to fail. Canny Danish depositors quickly sifted out where their deposits were fully guaranteed by the Danish government and where they were only partially guaranteed.

Iyer, Jensen, Johannesen and Sheridan (2019) also found the deposits above the insurance limit of 750,000 Danish kroner halved in the smaller banks that were not too big to fail but fell only by 20% in the six large banks that were publically marked by the Danish government as too big to fail.

Belgian depositors were just as canny as their Danish counterparts in sifting through the incentives behind explicit and implicit government guarantees. Atmaca, Kirschenmann, Ongena and Schoors (2020) used micro-data on 300,000 Belgian depositors of a large European bank during 2008 and 2009. In November 2008, Belgian deposit insurance was increased from €20,000 to €100,000 per customer-bank relation. The bank under study was, like several other EU banks, first nationalised and then re-privatised. In the run up to the GFC, more and more depositors limited their deposits to €20,000 for full coverage. Once coverage is increased to €100,000, €100,000 bunching largely substituted for €20,000 bunching. This €100,000 bunching faded away during the period of nationalisation, when implicit blanket guarantees applied. Bunching then returned in full force once the bank was re-privatised and the new €100,000 coverage limit becomes the binding guarantee for the depositors.

The record with the Crown deposit guarantee scheme between 2008 and 2011 and the overseas experience with changes in deposit insurance limits show conclusively that investors will run back into the sector if the finance companies are once again provided with Crown deposit insurance.

Finance companies dwell at the very margins of the financial system

But the biggest error of all is repeated, both now and back at the height of the GFC, finance companies are being included in the deposit guarantee scheme very much as an afterthought. Obvious arguments as to why they should not be included have been missed.

To begin with, 28 finance companies failed in the preceding two years with no implications for the stability of the banking system. At their peak, there were about 65 finance companies in the country. Half of them failed inside two years with no implications for the stability of the banking system or public policy. As the then Governor of the Reserve Bank reflected later on his crisis management decision making about the finance companies:

At the end of 2006 and in early 2007, we started to hear about property finance companies in trouble. Most were very small, and as individual failures they did not greatly concern us. But in the second half of the 2007, bigger finance companies started to fall like flies. As each one entered into liquidation, receivership or moratorium, media speculation turned to the next. We saw angry scenes of elderly debenture holders haranguing hapless managers at meetings. The pattern seemed clear: poor governance, spider-web company structures, vulnerable business models, mismatched balance sheets, bad management and inadequate supervision by the trustee companies.

At the Reserve Bank we started to worry: were the combined failures big enough to lead to a deposit run on the banks? The answer seemed to be no; in fact the banks were benefitting from a flight to quality. Did the failures point to fragile business models and practices in the banks themselves? Again, we thought not, the banks being much more sophisticated organisations than many finance companies (Bollard 2012).

There are now six finance companies in New Zealand with their asset-based barely exceeding $1/2 billion, less than 1/20th of the deposit base of the sector prior to the GFC as the chart below shows. The inclusion of finance companies in the Crown guarantee was a dubious decision in 2008 when the finance company sector was more than 20 times its current size.
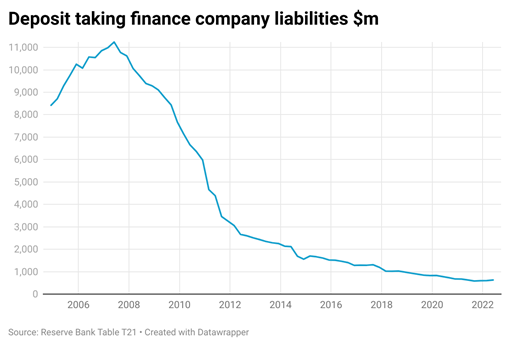
Six tiny finance companies plus a Christian charity engaged in social lending are irrelevant to the stability of the New Zealand financial system. These six and a Christian charity lender are all that is left of a sector that grew by 1/3rd in the four years before the GFC, by $4 billion, then quickly shrunk by nearly 90% in the aftermath of the GFC to 2017 and then continued in a further long decline.

Not only did the finance company sector shrink by 90% between 2008 and 2017, the sector shrunk a further 50% over the course of the review of the Reserve Bank legislation, which started with the change of government in 2017 and resulted in earlier legislation and now with the Deposit Takers Bill. The fact that the sector has almost faded away to oblivion was not highlighted in any of the official advice to ministers. Taxpayers, the Parliament and this Select Committee deserve better advice and research from the Treasury and the Reserve Bank.

Finance companies are vulnerable to Ponzi schemes

There have been one or two Ponzi scheme prosecutions by the Serious Fraud Office almost every year since the GFC, according to an Official Information Act Response to us from that Office. There is no mention of Ponzi schemes in the consultation documents written by the Treasury or Reserve Bank.

The Serious Fraud Office have told us that they have not received any communication from the Treasury or the Reserve Bank about criminal offending in the finance company sector according to Official Information Act responses. There is no mention in the Treasury and Reserve Bank papers on deposit insurance of the 20 convictions obtained by the Serious Fraud Office against nine finance companies between 2007 and 2010. The South Canterbury Finance prosecution alleging a $1.6 billion fraud in obtaining the Crown deposit guarantee came later. That Serious Fraud Office prosecution was unsuccessful.

After the South Canterbury Finance prosecution and 20 other successful prosecutions, we submit that it was a basic responsibility of the Treasury and Reserve Bank to go to the Serious Fraud Office for advice on the extent of sharp practice in the finance company sector. The Treasury and the Bank have let taxpayers down. None of the Treasury and Reserve Bank advice to ministers warned of the fraud all too common in that sector despite our written urgings to them to do so in October 2020 and in mid-2021.

Not enough separation of ownership and control in finance companies

Fraud is more likely in the finance company sector because they are owner-operated concerns or privately held. The owners can directly benefit by resort to a Ponzi scheme. Ponzi schemes such as the Bernie Madoff scheme are often a last ditch response to declining deposits. New deposits are paid out as returns on the investment in the hope that things will turn around shortly, but they rarely do.

The banks are run by professional staff who do not want to jeopardise their careers with sharp practice. Indeed, bankers are notoriously conservative; the origin of the bonus culture in banking was to find some way for the shareholders in a bank to introduce a little bit more risk into the lending decisions of the bank’s managers (Laeven 2013). Banks have professional and independent auditors, both internal and external, as well as overseas owners keen to protect their global brands. There is also no way for miscreant staff to divert the proceeds of a Ponzi scheme into their pockets. None of these safeguards apply to the finance company sector. The more than 20 prosecutions in the finance company sector after the introduction of 2008-2011 Crown deposit guarantee scheme should make the Treasury, the Reserve Bank, and ministers and now the Select Committee wary of the sector.

Fraud at the fringes of the financial sector is not rare overseas. The American taxpayer paid out over $150 billion in the 1980s on deposit insurance to their equivalent of our building societies. At least $53 billion was lost to 1,000 Saving and Loan (S&L) associations, where there were fraud convictions (Akerlof and Romer 1993). The failure of thousands of these savings and loan associations had no implications for the stability of American banking (Gorton and Tallman 2018). The era that encompassed the S&L crisis was known as the Great Moderation because the sustained real US real GDP growth between 1983 and 2007 was punctuated by only two short recessions.

The Reserve Bank should not administer the deposit insurance scheme

Staving off the breath of scandal

There were five criminal prosecutions of Ponzi schemes in 2013 alone and four more the next year. The Reserve Bank Governor cannot testify regularly in court about signing off on yet another finance company Ponzi scheme without job consequences. The Bank must be beyond reproach.

As a precaution against even the breath of a finance company Ponzi scheme scandal touching the Reserve Bank, the administration of any deposit insurance scheme should be squarely the responsibility of the Treasury. What is left of the international reputation of our Reserve Bank for independence and inflation targeting cannot be placed at risk because of a need to consider dismissing a Governor who yet again signs off on what turns out to be a Ponzi scheme.

A brief history of deposit insurance schemes

Deposit insurance had an inauspicious start

The proposed extension of deposit insurance to the finance company sector is not the extension of the tried-and-true policy instrument; deposit insurance is not a safe pair of hands. Reasonable people can disagree on its merits for banks. The question is does moral hazard offset any stabilising influence deposit insurance might have in a banking crisis (Allen, Carletti, Goldstein and Leonello 2018; Gorton and Winton 2003). This ambiguous reputation is not gleaned from the thousands of pages of writings of the Treasury and Reserve Bank as part of the Reserve Bank Act review.

Federal deposit insurance was the only bill in the New Deal 100 days legislation opposed by President Roosevelt, the Treasury, the Federal Reserve Board, and the American Bankers Association (Calomiris and White 1994). In the depths of the Great Depression, on the heels of the four-day federal bank holiday and off the back of many thousands of banks closing, the Roosevelt administration regarded deposit insurance as too risky a bet in the deepest financial crisis in American history.

The congressional and public debates in 1933 were sophisticated regarding the issues of moral hazard and adverse selection (Calomiris and White 1994). It was well known that the eight state deposit insurance schemes failed because of fraud and risky lending by the banks. When deposit insurance by the state governments was voluntary, only the riskier banks joined, and they were more likely to fail after joining (Calomiris and White 1994).

Deposit insurance was a backroom deal to keep in business the tens of thousands of American banks that only had one office and highly undiversified lending portfolios (Calomiris and White 1994). Most of America’s 40,000 banks in the mid-1920s had only one office. Of the over 9,000 banks that failed between 1929 and 1993 in the Great Depression, barely a handful of the failed banks were banks with branches (Calomiris 2009, 2011, 2013). Deposit insurance took effect in 1934, which is after US banking had stabilised in the Great Depression (Gorton and Winton 2003). The better policy choice came a one-half a century later with the repeal of state and federal restrictions on intrastate and interstate branching to allow for a diversification of lending portfolios.

Oh Canada

Canada was the next country to have adopted deposit insurance in 1967 for banks and mortgage companies. Again, it was a backroom deal; mortgage companies obtained federal deposit guarantees in return for not opposing the entry of trading banks into the mortgage business (Carr, Mathewson and Quigley 1995). A glaring anomaly in debates about bank crises is the tenacious stability of Canadian banking (Bordo, Redish and Rockoff 2015). The last bank failure, bar one, in Canada was in 1923. Canada’s banking system sailed through the Great Depression and the GFC because it had large banks with diversified portfolios (Bordo and Redish 1987; Bordo, Redish and Rockoff 2015).

When deposit insurance became a purely good thing

Papers by Bryant (1980) and Diamond and Dybvig (1983) significantly improved the academic reputation of the concept of deposit insurance schemes. Banks have a maturity mismatch in their balance sheets, which they say is to blame for bank runs. Deposits are payable on demand, but most of these deposits finance long-term loans such as mortgages. A rumour may start that more customers than the bank’s cash reserves can cope with are about to withdraw their deposits. Regardless of whether this rumour is true, it can send depositors rushing to withdraw their money.

Diamond and Dybvig (1983) argued that if too many depositors suddenly seek to withdraw, the bank will run out of cash despite being solvent. In a run, depositors are not reacting to news about the quality of the bank’s portfolio. Instead, they are withdrawing because they see others queuing up to do so and do not want to be left with a deposit in a bank with no cash reserves and teetering on bankruptcy. The bank fails because the panic forces the bank to sell good assets in a fire-sale.

Importantly, in the Diamond-Dybvig model of bank panics, if there is government-supplied deposit insurance or there is a central bank acting as a lender of last resort, depositors do not initiate bank runs, as they trust that their deposits are safely insured by the taxpayer. The icing on the cake is that the deposit insurance under this Diamond-Dybvig scenario costs the taxpayer nothing because there are no bank panics to stem. But on closer inspection, deposit insurance is a high stakes trade-off:

What can be done to mitigate the risk of self-fulfilling panic? As Diamond and Dybvig noted, a government backstop — either deposit insurance, the willingness of the central bank to lend money to troubled banks or both — can short-circuit potential crises. Indeed, the mere knowledge that a backstop exists can often quell a bank run; no money need actually change hands. But providing such a backstop raises the possibility of abuse; banks may take on undue risks because they know they’ll be bailed out if things go wrong. Case in point: the huge costs to taxpayers of bailing out irresponsible players during the savings and loans crisis in the 1980s. So banks need to be regulated as well as backstopped. As I said, the Diamond-Dybvig analysis had remarkably large implications for policy. (Krugman 2022).

The Diamond-Dybvig model of banking explains how sound banks can fail in a crisis of the back of just rumours and how depositor panic can spread from one bank to another. The Diamond and Dybvig model of banking crises certainly is popular because these two authors just shared the Nobel Prize in economics in 2022 with former Fed chair Ben Bernanke.

Diamond-Dybvig bank runs everywhere?

During the GFC, many governments seemed to see Diamond and Dybvig type panic-based bank runs everywhere and used bank deposit guarantees to quell the financial panic. As Sargent observed:

When monetary policy authorities, deposit insurance authorities and others looked out their windows in the fall of 2008, they saw Bryant-Diamond-Dybvig bank runs all over the place. And the logic of the Bryant-Diamond-Dybvig model persuaded them that if they could arrest the runs by effectively convincing creditors that their loans—that is, their short-term deposits—to these “banks” were insured, that could be done at little or no eventual cost to the taxpayers. You could nip the run in the bud and really prevent the next Great Depression. This is a very optimistic view of those 2008 interventions enlightened by the Bryant and Diamond-Dybvig model (Rolick 2010).

Reasonable people can disagree over whether offering a government guarantee to the retail and wholesale deposits of banks and shadow banks was wise at the height of the GFC (Tarullo 2019; Bordo 2018; Gorton and Metrick 2013). It is a rear-guard action to argue that six finance companies that now barely cobble together $1/2 billion in assets warrant attention from the Minister of Finance when planning for the next banking crisis.

The purpose of the preceding and the coming discussions of deposit insurance is to show that setting up deposit insurance is a nuanced policy trade-off for banks but not so for finance companies. Finance companies are a sideshow in any financial crisis and certainly never seed a banking crisis.

When deposit insurance is a pure bad

Diamond and Dybvig were well-aware of the risk of moral hazard. They recommended a 1978 paper by Kareken and Wallace on deposit insurance because that paper was about what Diamond and Dybvig left out: moral hazard. Sargent (2010) summarises the Kareken and Wallace modelling as follows:

Kareken and Wallace compare that no-deposit-insurance situation to another situation in which a government agency provides deposit insurance that is either free or is priced too cheaply, meaning that it’s not priced with a proper risk-loading. Kareken and Wallace show that in that situation, banks have an incentive to become as risky as possible, and as large as possible. Therefore, with a positive probability, banks will fail and taxpayers will have to compensate banks’ depositors. It is in banks’ shareholders’ interest that the banks organize themselves this way. This lets them gamble with the insurers’ and depositors’ money. The Kareken and Wallace model’s prediction is that if a government sets up deposit insurance and doesn’t regulate bank portfolios to prevent them from taking too much risk, the government is setting the stage for a financial crisis (Roleck 2010).

From this angle, deposit insurance is now a pure bad that encourages risk-taking and crises unless bank portfolios are successfully regulated. The literature on regulation of bank portfolios is one of profound subtlety, where the correct amount of capital banks must hold is subject to intense debate (Aiyar, Calomiris and Wieladek 2015). The spotty record of regulators before the GFC also throws doubt on their ability to do better next time (Calomiris 2011, 2013). It is still debated as to whether the regulatory response to the GFC made things worse rather than better (Tarullo 2019).

Insured deposit takers take more risks

Gropp, Gruendi and Guettler (2014) studied the response of 452 German savings banks after government guarantees were removed, following a lawsuit in the European Court of Justice in 2001. As a group, savings banks in Germany had assets totalling €1 trillion Euro and 22,000 branches. Gropp, Gruendi and Guettler (2014) found that the German savings banks cut off their most risky borrowers and raised interest rates to the rest after the deposit guarantee was removed. There were no similar effects in the control group of German banks to whom the guarantee was not applicable.

Lambert, North and Schuwer (2017) looked at what happened to insured deposits in 1,300 federally insured banks in the USA when their deposit insurance coverage was increased in October 2008 from $100,000 to $250,000. For some banks, the amount of insured deposits increased significantly. The most affected banks were found to increase their loans to risky commercial real estate, when compared to those banks that were largely unaffected by the deposit insurance limit change.

Risk-inviting rules of the game

The studies by Martin, Puri, and Ufier (2018), Iyer, Jensen, Johannesen and Sheridan (2019), Gropp, Gruendi and Guettler (2014) and Lambert, North and Schuwer (2017) show that depositors chase down government-insured higher returns and that bankers take more risks when deposits are insured. The papers published by the Treasury and Reserve Bank to justify deposit insurance just don’t pick up on the nuances in the theoretical and empirical literature such as summarised by Thomas Sargent:

So, of those two models, the Kareken-Wallace model makes you very cautious about lender-of-last-resort facilities and very sensitive to the risk-taking activities of banks. The Diamond-Dybvig and Bryant model makes you very sensitive to runs and very optimistic about the ability of insurance to cure them. Both models leave something out, and I think in the real world we’re in a situation where we have to worry about runs and we also have to worry about moral hazard (Roleck 2010).

The policy trade-off regarding deposit insurance for banks is staving off bank runs while inviting banks to take on more risk in their lending. This is a far greater risk for US banks than for New Zealand banks, because the US still has thousands of small banks with less diversified loan portfolios (Calomiris 2008, 2011, 2013; Gorton and Winton 2003). The number of federally insured commercial banks in the US was 14,146 in 1934, 14,384 in 1975, 8,300 in 2000 and 4,377 in 2020. So many small banks in the US with few, if any branches, is why bank panics and bank runs are regarded as very much an American phenomenon in the economic literature, as Gorton and Winton (2003) explain:

On the basis of the stylized facts about cross-country banking history … it would seem straightforward to observe that banks are not fundamentally flawed institutions. In fact, it does not seem to be an exaggeration to say that most of the theoretical work on panics has been motivated by the USA experience, which has then been incorrectly generalized. Panics simply are not a feature of most economies that have banks. The world is more complicated; industrial organization seems to be at the center of the incidence of panics. Not surprisingly, therefore, almost all the empirical work on panics has been on the USA experience. Until bank “crises” around the world in the last ten years, there simply has not been much else to study (Gorton and Winton 2003, p. 508).

A British banking scholar would be likely to remember the names of each of their banks that failed over the last 200 years. Northern Rock is the only British bank to have failed since 1866. By contrast, banks fail every year in the USA, as in the Federal Deposit Insurance Corporation chart reproduced below that includes the hundreds of bank failures during and after the GFC. A total of 1,617 federally insured banks failed between 1980 and 1994 (Hane 1998).

Chart, line chart

Description automatically generated

(Source: Federal Deposit Insurance Corporation)

There were many more banking crises over the last 40 years around the world. Their most common cause was ever more generous safety nets, including the moral hazard arising from the proliferation of deposit insurance starting in the 1970s and 1980s. The leading scholar in the field finds:

Recent research that investigates the determinants of banking fragility across different countries in the current era reaches a similar conclusion: the expansion of government-sponsored deposit insurance and other bank safety net programs throughout the world in the past three decades accounts very well for the increasing frequency and severity of banking crises in the current era. Empirical studies of this era of unprecedented frequency and severity of banking system losses has concluded uniformly that deposit insurance and other policies that protect banks from market discipline, intended as a cure for instability, have instead become the single greatest source of banking instability (Calomiris 2009).

The Deposit Takers Bill plans to extend to the finance company sector what is a contentious policy instrument in the banking sector. Deposit insurance invites risk-taking but its redeeming feature is once the banking crisis it may have seeded occurs, it may quell a bank run or panic. When pondering deposit insurance for banks, the trade-off between the incentive to take more risks and seed a crisis must be weighed against the stabilising influence of deposit insurance when there is a crisis and the possibility of bank runs (Allen, Carletti, Goldstein and Leonello 2018; Gorton and Winton 2003).

What is lost in the advice to ministers and now to Parliament is that temporary guarantees of bank deposits at the height of financial crises can be in theory implemented with little cost to taxpayers. Crisis management tools such as the temporary system-wide deposit guarantees for banks in the GFC have little to do with the case for permanent deposit insurance for banks or finance companies.

Most countries initially manage banks in distress through the lender of last resort function. The central bank lends to a bank in distress against good collateral at a high rate (Bordo 1990, 2018; Gorton and Metrick 2013). The Reserve Bank would help an individual bank through its difficulties while its loans are restructured and the bank perhaps recapitalised. Any risk from lending against compromised assets of the distressed bank is factored into the interest rate charged with the capital base of that distressed bank acting as a buffer against further losses on a lender of last resort loan. No one suggests that finance companies should have lender of last resort access.

The possibility of bank failures is best dealt with by adequate capital ratios. The Reserve Bank was planning to require banks to increase their capital ratios but postponed this because of Covid-19. As a crisis prevention tool, higher capital adequacy ratios make banks sturdier. Higher capital ratios make even those banks that regard themselves as “too big to fail” sturdier. This contrasts with deposit insurance, which invites insured institutions, big and small, and depositors to take on more risk. Higher capital adequacy ratios create a larger buffer against bad loans undermining a bank, big or small.

No crisis management trade-off for finance companies

Reasonable people can disagree on whether deposit insurance destabilises the financial system by incentivising risk-taking more than it stabilises it by calming potential depositor panics during a crisis:

Theory suggests that deposit insurance can either increase or decrease banking system risk. On the one hand, credible deposit insurance can make the banking system more stable by reducing liquidity risk. It does so by removing the incentive of depositors to withdraw funds from banks when bank risk increases. On the other hand, deposit insurance may be a source of “moral hazard”—it may increase the risk appetite of banks because their ability to attract deposits no longer reflects the risk of their portfolios. Deposit insurance can also cause “adverse selection,” including as the result of unwitting increases in risk when the absence of market discipline permits poor risk managers to operate banks. If the capital position and asset risk of banks are not regulated and supervised carefully, the insurance-induced risk taking may increase insolvency risk and undermine financial stability in the long run, despite the liquidity risk reductions that deposit insurance creates (Calomiris and Chen 2020).

The debate over deposit insurance for banks is nuanced. Observers must listen carefully to the competing arguments before making up their mind (Demirgüç-Kunt, Kane, and Laeven 2008; Calomiris and Jaremski 2016). Readers must also guard against the protagonists making incorrect generalisations from the uniquely fragile US banking system, past and present (Gorton and Winston 2003). No such policy trade-off exists between moral hazard and better financial and banking system crisis management when making the case for deposit insurance for finance companies.

Back to the New Zealand situation

Just moral hazard

The six finance companies with barely $1/2 billion in assets between them will have no role in future financial crises. The sector is at the edge of oblivion; one-twentieth of its size at the eve of the GFC.

The only policy issue here is that deposit insurance will encourage greater risk taking when finance company deposits are insured by the Crown. What do taxpayers get back in return for this windfall to the finance company sector? The higher returns in the finance company sector comes off the back of greater risk taking. Everyone knows that. At some point we must expect their investors to just beware.

How much?

As it stands, taxpayers will not know how much they will pay for deposit insurance until the Minister of Finance issues a Statement of Funding after the Bill is passed. Only then will depositors know how much they will pay and how quickly the Minister wants to accumulate the fund. That is unsatisfactory. We cannot submit our views to the Select Committee on the premium without such an estimate.

The discussion of the deposit insurance premium in the papers by the Treasury and the Reserve Bank focused on how long it will take to build a fund of a certain size relative the deposits to be insured. The Bank refers to 0.2% per year as a reasonable rate for the deposit insurance premium:

Looking at countries with banking systems and per capita GDP similar to New Zealand, a target size for a domestic insurance scheme of 2 percent of insured deposits would be large. At a per-depositor insurance limit of $30,000-$50,000, this implies an insurance fund of around $2-3 billion (Table 5B). The Review Team estimates this could be built up over a decade through a levy of 5 percent of the banking sector’s annual profits, or a premium of 20-basis points on banks’ insured deposits (Reserve Bank 2019, p. 92)

That was said in a 2019 consultation paper. A deposit insurance premium of 20-basis points was about equal to the return on an online call account a mere year ago before the sharp spike in inflation and nominal interest rates – see the chart below. The same chart shows that term deposit rates were closing in on the 20-basis points deposit insurance premium and that gap charted below is before tax.
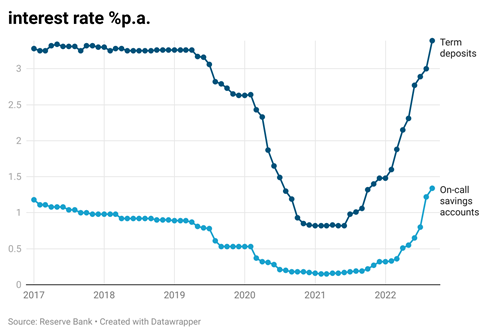
Interest rates on term deposits and on online call accounts dropped by about two thirds over the course of the review of the Reserve Bank legislation which started after the 2017 election. Deposit insurance has moved from clipping a small part of the interest rate return on deposits in 2019 to taking most or all of it in 2021 and still in 2022 after the spike in recent inflation is accounted for.

The estimate of a 20-basis point deposit insurance premium was for advice from the Reserve Bank and Treasury to have a deposit insurance limit per depositor of $30,000 to $50,000. The Bill has a much larger deposit insurance limit of $100,000. It will either take many decades to build up to the reserve fund target or the deposit insurance premiums for banks must be much more than 20-basis points.

The need for deposit insurance premiums to be risk rated for different institutions is mentioned in a sentence or two in the discussion papers and regulatory impact statement but there is no suggestion as to how high these premiums might go for different institutions including finance companies.

Government-insured junk bonds

Before the surge in inflation, the interest rate paid by finance companies on six-month deposits was up to twice that of banks. A fair insurance premium for deposit takers in the finance company sector would be large given their previous experience with risky lending, with related party lending and exposure to real estate development. Prior to the GFC, all but five of the sixty odd finance companies lacked a credit agency rating. South Canterbury Finance was BBB rated when its deposits were guaranteed by the Crown in 2008. All but one of the six now remaining finance companies have credit agency ratings at a BB standing or less or no credit agency rating at all; see the table below.

Finance companyCredit rating agencyRating and outlook
Christian Savings LimitedFitch RatingsBB+, Stable
FE Investments Limited (in receivership) n/aCredit ratings have been withdrawn
Finance Direct Limitedn/aExempt
General Finance LimitedEquifaxBB-, Stable
Gold Band Finance Limitedn/aExempt
Liberty Financial LimitedStandard & Poor’sBBB-, Stable
Mutual Credit Finance Limitedn/aExempt
Xceda Finance LimitedEquifaxB, Stable

Source: Reserve Bank at https://www.rbnz.govt.nz/regulation-and-supervision/cross-sector-oversight/registers-of-entities-we-regulate/register-of-non-bank-deposit-takers-in-new-zealand

The BBB credit rating suggests investment grade; BB means a higher probability for default. BB and B bonds fall in the category of junk bonds, high-yield bonds, or speculative instruments. The B rating suggests a company can meet its financial commitments but may be left highly exposed to adverse economic conditions. For Moody’s, BB and B bonds are speculative and “subject to a substantial risk of defaulting on certain senior operating obligations and other contractual commitments.” It is a disservice to the taxpayer to contemplate deposit insurance for a sector that trades in junk bonds.

A magnet for retirees

The previous pages presented ample evidence that investors watch interest rates keenly especially if higher but riskier returns that are government insured come on the market. Crown deposit insurance will encourage retirees to re-enter the finance company sector. Who wouldn’t be tempted to increase the returns on their retirement savings for no extra risk because of a Crown deposit guarantee? A canny retiree would deposit $100,000 with each of the six finance companies to bet on a sure thing.

Yours faithfully,
New Zealand Taxpayers’ Union Inc.

Jim Rose
Research Fellow
Jim@taxpayers.org.nz

References

Aiyar, Shekhar & Charles W Calomiris & Tomasz Wieladek, 2015. “Bank Capital Regulation: Theory, Empirics, and Policy,” IMF Economic Review vol. 63 (4), pp. 955-983, November.

Akerlof, George A., and Paul M. Romer, 1993. “Looting: The Economic Underworld of Bankruptcy for Profit,” Brookings Papers on Economic Activity vol. 24(2), pp. 1-74.

Allen, Franklin, Elena Carletti, Itay Goldstein and Agnese Leonello 2018. “Government guarantees and financial stability”. Journal of Economic Theory, Vol 177 pp. 518-557.

Atmaca, S, K Kirschenmann, S Ongena and K Schoors (2020), “Deposit insurance, bank ownership and depositor behavior”, CEPR Discussion Paper 15547.

Auditor-General 2011. The Treasury: Implementing and managing the Crown Retail Deposit Guarantee Scheme. Office of the Auditor-General, Wellington.

Bordo, Michael D. “The Lender of Last Resort: Alternative Views and Historical Experience.” Economic Review (Federal Reserve Bank of Richmond), Vol. 76/1, pp. 18-29, (January/February 1990).

Bordo, Michael D. 2018. “An Historical Perspective on the Quest for Financial Stability and the Monetary Policy Regime,” The Journal of Economic History, vol 78(2), pp. 319-357.

Bordo, Michael D. and Angela Redish. “Why did the Bank of Canada Emerge in 1935?” Journal of Economic History, Vol. XLVII, No. 2, June 1987, pp. 405-4 17.

Bordo, Michael D., Angela Redish and Hugh Rockoff, 2015. “Why didn’t Canada have a banking crisis in 2008 (or in 1930, or 1907, or …)?,” The Economic History Review, vol 68 (1), pp. 218-243.

Bryant, John. 1980. “A Model of Reserves, Bank Runs, and Deposit Insurance”. Journal of Banking & Finance 4(4), pp. 335–44.

Calomiris, Charles W., “Banking Crises,” In New Palgrave Dictionary of Economics, 2nd Edition, edited by Steven Durlauf and Lawrence Blume, 2009.

Calomiris, Charles W., “Banking crises yesterday and today,” Financial History Review, Cambridge University Press, vol. 17 (1), pp. 3-12, April 2010.

Calomiris, Charles W., “Banking Crises and the Rules of the Game,” In Monetary and Banking History: Essays in Honour of Forrest Capie, edited by Geoffrey Wood, Terence Mills, and Nicholas Crafts, Routledge, 2011, pp. 88-132.

Calomiris, Charles W., “Banking Fragility of the United States, 1790-2009”. In Handbook of Key Global Financial Markets, Institutions, and Infrastructure, edited by Gerard Caprio, Charles W. Calomiris, and Larry Neal. London: Elsevier Press, 2013.

Calomiris, Charles W. and Sophia Chen, 2020. “The Spread of Deposit Insurance and the Global Rise in Bank Asset Risk since the 1970s,” Journal of Financial Intermediation, January.

Calomiris, Charles W. and Matthew Jaremski, 2016. “Deposit Insurance: Theories and Facts,” Annual Review of Financial Economics, vol. 8(1), pages 97-120, October.

Calomiris, Charles W., and E. N. White. “The Origins of Federal Deposit Insurance”, In The Regulated Economy: A Historical Approach to Political Economy, C. Goldin and G. Libecap (eds.), NBER, University of Chicago Press, 1994, pp. 145-188.

Carr, Jack, Frank Mathewson and Neil Quigley. “The Economics of Canadian Deposit Insurance.” Department of Economics Research Reports, 9502. London, ON: Department of Economics, University of Western Ontario (1995).

Demirgüç-Kunt, A., E.J. Kane, and L. Laeven (eds.), 2008, Deposit Insurance around the World: Issues of Design and Implementation (Cambridge, MA: MIT Press).

Diamond, Douglas W., and Philip H. Dybvig. 1983. “Bank Runs, Deposit Insurance, and Liquidity.” Journal of Political Economy 91(3), pp. 401–19.

Gorton, Gary, and Andrew Metrick. 2013. “The Federal Reserve and Panic Prevention: The Roles of Financial Regulation and Lender of Last Resort.” Journal of Economic Perspectives, 27 (4): 45-64.

Gorton, Gary, and Ellis Tallman, Fighting Financial Crises: Learning from the Past. Chicago: University of Chicago Press, 2018.

Gorton, Gary., and Andrew Winton. “Financial Intermediation”. In Constantinides, George, Milton Harris, and Rene Stulz (eds). The Handbook of the Economics of Finance Elsevier Science, 2003 pp 431-552.

Gropp, Reint., Christian Gruendl, and Andre Guettler. “The Impact of Public Guarantees on Bank Risk-Taking: Evidence from a Natural Experiment”. Review of Finance, Volume 18, Issue 2, April 2014, pp. 457–488.

Hane, George. “The Banking Crises of the 1980s and Early 1990s: Summary and Implications”. FDIC Banking Review, 1998 Vol. 11, No. 1, pp. 1-21.

Iyer R., Jensen, TL., Johannesen, N., and Sheridan, A. 2019. “The distortive effects of too-big-to-fail: evidence from the Danish market for retail deposits”, The Review of Financial Studies, Vol:32, pp. 4653-4695.

Kareken, John H., and Neil Wallace. 1978. “Deposit Insurance and Bank Regulation: A Partial-Equilibrium Exposition.” Journal of Business 51(July), pp. 413–38.

Krugman, P. “A Nobel Prize for the Economics of Panic”, New York Times (11 October 2022) at https://www.nytimes.com/2022/10/11/opinion/nobel-economics-bernanke-diamond-dybvig.html

Laeven, Luc, 2013. “Corporate Governance: What’s Special About Banks?” Annual Review of Financial Economics, vol. 5(1), pp. 63-92, November.

Lambert, C., F. Noth, and U. Schüwer (2014). “How do insured deposits affect bank risk? Evidence from the 2008 Emergency Economic Stabilization Act.” Journal of Financial Intermediation 29 (October), pp. 81–102.

Martin, Christopher., Manju Puri and Alexander Ufier, 2018. “Deposit Inflows and Outflows in Failing Banks: The Role of Deposit Insurance,” NBER Working Papers 24589, National Bureau of Economic Research.

O’ Sullivan, Fran. “Vital witness missing at SCF trial”. New Zealand Herald, 15 October 2014.

Reserve Bank 2019. Safeguarding the future of our financial system In-principle decisions and follow-up questions on: The role of the Reserve Bank and how it should be governed Consultation Document 2A Phase 2 of the Reserve Bank Act Review June 2019. Reserve Bank of New Zealand, Wellington.

Rolick, A., 2010. “Interview with Thomas Sargent”. The Region, Federal Bank of Minneapolis, vol. 24, issue Sep, pp. 26-39.

Tarullo, Daniel K. “Financial Regulation: Still Unsettled a Decade After the Crisis.” The Journal of Economic Perspectives 33, no. 1 (2019): 61–80.

Two AI summaries of @Dandolfa on deficient demand

Scott Freeman on the money  multiplier

Prescott and Kydland on business cycles

@TaxpayersUnion 2021 SUBMISSION ON THE DEPOSIT TAKERS BILL @GeorgeSelgin

21 February 2021

David Hargreaves
Manager, Policy Projects
Financial System Policy and Analysis Department
Reserve Bank of New Zealand
Wellington 6140

By email: dta@rbnz.govt.nz

Dear David,
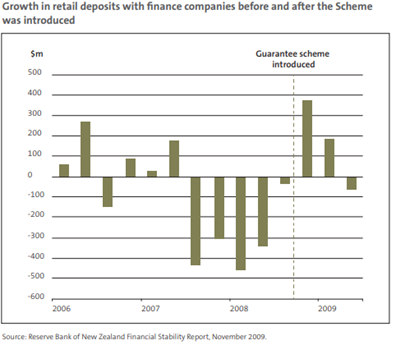
SUBMISSION ON THE DEPOSIT TAKERS BILL: NO DEPOSIT INSURANCE FOR FINANCE COMPANIES

About the Submitter

  1. This submission has been prepared for the New Zealand Taxpayers’ Union by Research Fellow Jim Rose. Jim is an economist with three decades experience in the public sector in New Zealand and Australia. He has worked at the Ministry of Business, Innovation and Employment, the Department of Labour, the Ministry of Social Development, and the New Zealand Treasury, and in Canberra for the Productivity Commission, the Department of Prime Minister and Cabinet, and the Department of Finance. Jim has Masters degrees in economics and in public policy from the Australian National University and from the National Graduate Institute for Policy Studies in Tokyo respectively.
  2. Founded by David Farrar and Jordan Williams in 2013, the Taxpayers’ Union’s mission is Lower Taxes, Less Waste, More Transparency.
  3. We enjoy the support of some 170,000 registered members and supporters, making us the most popular campaign group championing fiscal conservatism and transparency.  We are funded by our thousands of donors and approximately five percent of our income is from membership dues and donations from private industry.
  4. We are a lobby group not a think tank.  Our grassroots advocacy model is based on international taxpayer-group counterparts, particularly in the United Kingdom and Canada, and similar to campaign organisations on the left, such as Australia’s Get Up, New Zealand’s ActionStation, and Greenpeace. 
  5. The Union is a member of the World Taxpayers Associations – a coalition of taxpayer advocacy groups representing millions of taxpayers across more than 60 countries. 
  6. We give permission for the Reserve Bank to publish this submission.

Scope of submission

  • This submission on behalf the Taxpayers’ Union is limited to opposing the proposal in the exposure draft of the Deposit Takers Bill to offer Crown deposit insurance to finance companies. No opinion is offered on issues raised in the exposure draft that are not connected to deposit insurance for finance companies except for a short discussion on the pricing of Crown deposit insurance.

Executive summary

  • This submission contends that implementing deposit insurance for finance companies would be a short-sighted policy and must be considered a policy option distinct from deposit insurance only for banks.
    • Finance companies operate within a different set of moral hazard concerns than banks do, which deposit insurance schemes interact with to drive the sort of risk-seeking behaviour that makes the guarantee more likely to be activated.
    • Economic stability is, however, not protected by deposit insurance for finance companies, in the same way is it may be for banks.
    • In New Zealand, finance companies now make an even smaller proportion of capital markets than they did prior to the Global Financial Crisis (GFC). The deposit guarantee scheme put in place for finance companies then was of dubious value, even with their larger share of the market in 2008.
    • The Reserve Bank Governor would be placed in an unenviable position as regulator for finance company deposit insurance, as that portion of the market is regularly plagued by scandal and Serious Fraud Office investigations.
    • While there is valid debate as to the correct policy balance for insuring deposits in banks, the case is settled that finance companies should not be included in a scheme such as the one proposed. It is recommended that finance companies be removed from the Draft Bill.

Finance companies are inherently risky

The Auditor-General’s 2011 report goes unremembered

  • The previous Crown deposit guarantee scheme is barely mentioned in the thousands of pages sent to the Minister and the Cabinet as part of the review of the Reserve Bank legislation. This is especially disappointing considering the highly critical remarks in the Auditor-General’s 2011 review of the implementation of the 2008-2011 retail deposit guarantee scheme by the Treasury.
  • Now as then, the Treasury and the Reserve Bank appear to be aloof to the mercurial nature of deposit insurance as a policy instrument. It can bite back at the taxpayer big time as the 2008-2011 scheme certainly did. The proposed deposit guarantee has not been jumbled together in a few days as was the guarantee cobbled together at the height of the GFC. This reincarnation is years in the making.
  • The Auditor-General’s 2011 review found that the Treasury was focused on how to pay out depositors with little regard to how to reduce risk to the Crown by offering deposit insurance to failing finance companies. Indeed, the Crown deposit guarantee was renewed for South Canterbury Finance despite the Treasury having concluded at the time that the finance company was likely to fail.
    • The Treasury received the inspector’s report on 17 July 2009. The report reaffirmed the seriousness of the risk factors suspected with the books and management of South Canterbury Finance. From April to August 2009, the Treasury investigated the affairs of South Canterbury Finance extensively. On 12 August 2009, the Treasury made a provision for the estimated loss if South Canterbury Finance failed. This provision reflected the Treasury’s judgment that South Canterbury Finance was more likely than not to fail. The provision was made with the benefit of the inspector’s report (Auditor-General 2011, p.103).
  • Would a fair deposit insurance premium towards the end be perhaps up to one-half of South Canterbury Finance’s deposits under a Crown guarantee? To quote the Audit report again:
    • The Treasury’s monthly financial statements did not include any provisions for payouts under the Scheme until June 2009, when the provision was estimated at $0.8 billion. The Treasury knew before June 2009 that further failures of finance companies were likely, so this information should have been better reflected in the monthly financial statements earlier than June 2009 (Auditor-General 2011, p.94).
  • About $1.6 billion of the $2 billion in initial losses to the Crown from the deposit guarantee scheme was from the failure of South Canterbury Finance. The Treasury didn’t face up to the facts as early as it should have with the 2008-2011 Crown deposit guarantee to finance companies. History is repeated.

Deposits flooded into finance companies off the back of the 2008 Crown guarantee

  1. After bleeding money in 2007 and 2008, there is a surge in deposits after the 2008 Crown guarantee for finance companies, as in the chart below from the Auditor-General (2011). South Canterbury Finance grew by 25% in deposits after the Crown Guarantee (Auditor-General 2011); deposits in South Canterbury Finance increased from $75 million in 2004 to $2 billion in 2008 (O’Sullivan 2015); another company grew from $800,000 in deposits to $8 million in deposits off the back of the Crown guarantee (Auditor-General, 2011).
  1. There is little discussion in the Treasury and Reserve Bank papers of the implications of the guarantee for a resurgence of investor interest in what is an intrinsically more risky sector. There is no mention in the Reserve Bank legislation review papers of the massive surge in investment, as shown in the above chart. Instead of bleeding $500 million every quarter as in the lead up to the GFC, $600 million flooded back into the sector off the back of the Crown guarantee.

Depositors chase riskier returns when government insured

  1. The proposition that depositors will invest in higher-risk returns if they are government insured is well-established in the deposit insurance literature. The burst of deposits back into the finance company sector after the government guarantee in New Zealand is not an anomaly to be dismissed. Instead, a resurgence in growth in the finance company sector is inevitable if the draft Bill continues to include deposit insurance for the sector.
  2. Martin, Puri, and Ufier (2018) examined the daily account level balances of a distressed bank in the USA at the height of the GFC. They studied the outflow (bank run-off) of uninsured depositors and the inflow (bank run-in) of insured deposits as this bank was in its death throes. The maximum level of federal deposit insurance increased from $100,000 to $250,000 per account holder as a stabilisation measure at the height of the GFC in 2008.
  3. Martin, Puri, and Ufier (2018) found that this failing bank was able to replace about 1/3rd of its depositor base in its last year of life, despite public knowledge of the intensive revelatory scrutiny of its declining condition. Much of these new deposits came in in the last 90 days of the bank. The bank’s regulatory filings spoke of being significantly undercapitalised and then critically undercapitalised financial states. The new deposits were almost all term deposits paying slightly above market interest rates and were just under the Federal Deposit Insurance Corporation insurance limit. These deposits initially bunched at the $100,000 dollar limit, then bunched at the $250,000 insurance limit when this limit was increased at the height of the GFC in October 2008.
  4. Iyer, Jensen, Johannesen and Sheridan (2019) had access to all personal deposit accounts and their balances in Denmark when they studied changes in deposit insurance for Danish banks. The Danish government guaranteed all bank liabilities in 2008. Prior to the GFC, deposit insurance was limited to 300,000 Danish kroner. The Danish government later limited deposit insurance to 750,000 Danish kroner in 2011. The Danish government also named six Danish banks as too big to fail.
  5. Iyer, Jensen, Johannesen and Sheridan (2019) found that for the banks that were not too big to fail, accounts clustered around the insurance limit of 750,000 Danish kroner. There was no similar bunching of deposits at the deposit insurance limit for the six banks deemed too big to fail. They also found the deposits above the insurance limit of 750,000 Danish kroner halved in the banks not too big to fail but fell only by 20% in banks that were marked by the Danish government as too big to fail.
  6. The record with the Crown deposit guarantee scheme between 2008 and 2011 and the overseas experience with changes in deposit insurance limits show conclusively that investors will run back into the sector if the finance companies are once again provided with Crown deposit insurance.

Finance companies dwell at the very margins of the financial system

  • But the biggest error of all is repeated, both now and back at the height of the GFC, finance companies are being included in the deposit guarantee scheme very much as an afterthought. Obvious arguments as to why they should not be included have been missed. To begin with, 28 finance companies had failed in the preceding two years with no implications for financial stability. At their peak, there were about 65 finance companies in the country. Half of them failed inside two years with no implications for the stability of the banking system or public policy. As the then Secretary to the Treasury and then the Governor of the Reserve Bank reflected later on his crisis management decision making about the finance companies:
    • At the end of 2006 and in early 2007, we started to hear about property finance companies in trouble. Most were very small, and as individual failures they did not greatly concern us. But in the second half of the 2007, bigger finance companies started to fall like flies. As each one entered into liquidation, receivership or moratorium, media speculation turned to the next. We saw angry scenes of elderly debenture holders haranguing hapless managers at meetings. The pattern seemed clear: poor governance, spider-web company structures, vulnerable business models, mismatched balance sheets, bad management and inadequate supervision by the trustee companies.
    • At the Reserve Bank we started to worry: were the combined failures big enough to lead to a deposit run on the banks? The answer seemed to be no, in fact the banks were benefitting from a flight to quality. Did the failures point to fragile business models and practices in the banks themselves? Again, we thought not, the banks being much more sophisticated organisations than many finance companies (Bollard 2012
  • There are now five finance companies in New Zealand with their asset-based barely exceeding $1/2 billion, less than 1/20th of the deposit base of the sector prior to the GFC as the chart below shows. The inclusion of finance companies in the Crown guarantee was a dubious decision in 2008 when the finance company sector was more than 20 times its current size. Five tiny finance companies plus a Christian charity engaged in social lending are irrelevant to the stability of the New Zealand financial system. These five and a Christian charity lender are all that is left of a sector that grew by 1/3rd in the four years before the GFC, by $4 billion, then quickly shrunk by nearly 90% in the aftermath of the GFC and then continued in a further long decline.
  • The above chart shows that the finance company sector has halved in size since the review of the Reserve Bank Act started after the 2017 General Election. The sector is now a tiny part of the financial system.

Finance companies are vulnerable to Ponzi scheme

  • There have been one or two Ponzi scheme prosecutions by the Serious Fraud Office almost every year since the GFC, according to an Official Information Act Response from that Office. There is no mention of Ponzi schemes in the consultation documents written by the Treasury or Reserve Bank.
  • The Serious Fraud Office has not received any communication from the Treasury in recent years about criminal offending in the finance company sector according to a 16 September 2020 Official Information Act response. There is no mention in the Treasury and Reserve Bank papers on deposit insurance in the finance company sector of the 20 convictions obtained by the Serious Fraud Office against nine finance companies between 2007 and 2010. The South Canterbury Finance prosecutions over a $1.6 billion fraud came later.
  • After the South Canterbury Finance prosecution and 20 other successful prosecutions, it was a basic responsibility of the Treasury and Reserve Bank to go to the Serious Fraud Office for advice on the extent of sharp practice in the finance company sector. The Treasury is letting taxpayers down.

Not enough separation of ownership and control in finance companies

  • Fraud is more likely in the finance company sector because they are owner-operated concerns or privately held. The owners can directly benefit by resort to a Ponzi scheme. Ponzi schemes such as the Bernie Madoff scheme was a response to declining deposits. New deposits are paid out as returns on the investment in the hope that things will turn around shortly, but they rarely do.
  • The banks are run by professional staff who do not want to jeopardise their careers with sharp practice. Indeed, bankers are notoriously conservative; the origin of the bonus culture in banking was to find some way for the shareholders in a bank to introduce a little bit more risk into the lending decisions of the bank’s managers (Laeven 2013). Banks have professional and independent auditors, both internal and external, as well as overseas owners keen to protect their global brands. There is also no way for miscreant staff to divert the proceeds of a Ponzi scheme into their pockets. None of these safeguards apply to the finance company sector. The more than 20 prosecutions in the finance company sector after the introduction of Crown deposit guarantee scheme should make the Treasury, the Reserve Bank, and ministers wary of the sector.
  • Fraud at the fringes of the financial sector is not rare overseas. The American taxpayer paid out over $150 billion in the 1980s on deposit insurance to their equivalent of our building societies. At least $53 billion was lost to 1,000 Saving and Loan (S&L) associations, where there were fraud convictions (Akerlof and Romer 1993). The failure of thousands of these savings and loan associations had no implications for the stability of American banking (Gorton and Tallman 2018). The era was known as the Great Moderation because the sustained real GDP growth between 1983 and 2007 was punctuated by only two short recessions.

Reserve Bank not the desirable regulator

Staving off the breath of scandal

  • The Government is borrowing $50 billion from the Reserve Bank to finance the COVID-19 spend-up. The Crown’s reputation as a sovereign borrower cannot be put at risk by ministers having to discipline the Reserve Bank Governor for signing off on deposit insurance for what turned out to be yet another finance company Ponzi scheme. There were five criminal prosecutions of Ponzi schemes in 2013 alone and four more in the next year. The Governor cannot testify regularly in court and to select committees about signing off on yet another Ponzi scheme without job consequences.
  • The Reserve Bank must be beyond reproach. Our Reserve Bank can lend $50 billion to the Government without igniting inflationary expectations because of credibility of an inflation targeting regime built up over the last 30 years. Our reputation for keeping inflation low and never monetising debt could evaporate if governors are fired with signing-off on Ponzi schemes given yet again as the reason.

Let the Treasury carry the can

  • As a precaution against even the breath of a finance company Ponzi scheme scandal touching the Reserve Bank, the administration of any deposit insurance scheme should be squarely the responsibility of the Treasury. The international reputation of our Reserve Bank for independence and inflation targeting cannot be placed at risk because of a need to consider dismissing a Governor who yet again signs off on what turns out to be a Ponzi scheme. In contrast, a sacking of the Secretary of the Treasury for unwittingly signing off a deposit guarantee for what became a Ponzi scheme will not jeopardise the credibility of our inflation targeting regime.

The missing witness

  • When the South Canterbury fraud prosecution finally came before the courts in 2014, the Secretary to the Treasury was described as the missing witness because the Crown did not offer him as a witness (O’Sullivan 2014). Justice Paul Heath acquitted three defendants on the central charge of deceptive conduct to enable the finance company to join the Crown Retail Deposits Guarantee Scheme. His Honour the Judge wrote:
    • In the absence of evidence from the Secretary, I could not exclude the reasonable possibility that he would have signed the guarantee deed on 19 November 2008, even if the Crown was right about the alleged material omissions. That is why I found Messrs Sullivan, White and McLeod not guilty on count 10 (O’Sullivan 2014).
  • Justice Heath said that irrespective of the company’s position, the Treasury might have allowed South Canterbury Finance into the deposit guarantee scheme to maintain public confidence and to avoid capital flight to Australia where a similar deposit guarantee scheme had been introduced and because no applications by finance companies to join the deposit guarantee scheme had been refused previously due to a lack of creditworthiness or poor business practices (O’Sullivan 2014). The Judge was an astute observer about the mixed motives a Treasury Secretary might have when signing guarantees for banks and finance companies at the height of a financial crisis. The need for decisiveness at the behest of ministers under great stress may render moot the scrutinising of the creditworthiness of each deposit taker seeking a Crown guarantee. The Governor of the Reserve Bank cannot be put in the position of being a missing witness at a later fraud trial.

Finance companies and deposit insurance schemes: A brief history

Deposit insurance had an inauspicious start

  • The proposed extension of deposit insurance to the finance company sector is not the extension of the tried-and-true policy instrument; deposit insurance is not a safe pair of hands. These schemes have always had an ambiguous reputation. Reasonable people can disagree on its merits for banks. The question is does moral hazard offset any stabilising influence deposit insurance might have in a banking crisis (Allen, Carletti, Goldstein and Leonello 2018; Gorton and Winton 2003). This ambiguous reputation is not gleaned from the thousands of pages of writings of the Treasury and Reserve Bank as part of the Reserve Bank Act review.
  • Federal deposit insurance was the only bill in the New Deal 100 days legislation opposed by President Roosevelt, the Treasury, the Federal Reserve Board, and the American Bankers Association (Calomiris and White 1994). In the depths of the Great Depression, on the heels of the four day federal bank holiday and off the back of many thousands of banks closing, the Roosevelt administration regarded deposit insurance as a too risky a bet in the deepest financial crisis in American history. The congressional and public debates in 1933 were sophisticated as they are now regarding the issues of moral hazard and adverse selection (Calomiris and White 1994). It was well known that the eight state deposit insurance schemes failed because of fraud and risky lending by the banks. When deposit insurance by the state governments was voluntary, only the riskier banks joined, and they were more likely to fail after joining (Calomiris and White 1994).
  • Federal deposit insurance was enacted on the 151st attempt; 147 of the previous 150 bills did not even get out of committee. Deposit insurance was a backroom deal to keep in business the tens of thousands of American banks that only had one office and highly undiversified lending portfolios (Calomiris and White 1994). Most of America’s 40,000 banks in the mid-1920s had only one office. Of the over 9,000 banks that failed between 1929 and 1993 in the Great Depression, barely a handful of the failed banks were banks with branches (Calomiris 2009, 2011, 2013). Deposit insurance took effect in 1934 which is after US banking had stabilised in the Great Depression (Gorton and Winton 2003). The better policy choice came a one-half a century later with the repeal of state and federal restrictions on intrastate and interstate branching to allow for a diversification of lending portfolios. Deposit insurance was not the first best policy choice from its start.

Oh Canada

  • Canada was the next country to have adopted deposit insurance in 1967 for banks and mortgage companies. Again, it was a backroom deal where mortgage companies obtained federal deposit guarantees in return for not opposing the entry of trading banks into the mortgage business (Carr, Mathewson and Quigley 1995). A glaring anomaly in debates about banking crises is the tenacious stability of the Canadian banking system. The last bank failure, bar one, in Canada was in 1923. Canada’s banking system sailed through the Great Depression and the GFC because it had large banks with diversified loan portfolios (Bordo and Redish 1987; Bordo, Redish and Rockoff 2015).

When deposit insurance became a purely good thing for banks

  • The academic reputation of deposit insurance picked up no end with the papers by Bryant (1980) and Diamond and Dybvig (1983). Banks have a maturity mismatch in their balance sheets, which they say is to blame for bank runs. Deposits are payable on demand, but most of these deposits were financing long-term loans. Diamond and Dybvig (1983) argued that if too many depositors suddenly seek to withdraw, the bank will run out of cash despite being solvent. In a run, depositors are not reacting to news about the quality of the bank’s portfolio. Instead, they are withdrawing because they see others doing so and do not want to be left with a deposit in a bank with no cash reserves. The bank then fails because a depositor panic forces the bank to sell good assets in a fire-sale.
  • Importantly, in the Diamond-Dybvig model of bank panics, if there is government-supplied deposit insurance, depositors do not initiate bank runs, as they trust that their deposits are safely insured by the taxpayer. The icing on the cake is that the deposit insurance under this Diamond-Dybvig scenario costs the taxpayers nothing because there are no bank panics to stem.

Bryant-Diamond-Dybvig bank runs everywhere?

  • During the GFC, many governments seemed to see Diamond and Dybvig type panic-based bank runs everywhere and used guarantees to quell the panic. As Sargent (2010) observed:
    • When monetary policy authorities, deposit insurance authorities and others looked out their windows in the fall of 2008, they saw Bryant-Diamond-Dybvig bank runs all over the place. And the logic of the Bryant-Diamond-Dybvig model persuaded them that if they could arrest the runs by effectively convincing creditors that their loans—that is, their short-term deposits—to these “banks” were insured, that could be done at little or no eventual cost to the taxpayers. You could nip the run in the bud and really prevent the next Great Depression. This is a very optimistic view of those 2008 interventions enlightened by the Bryant and Diamond-Dybvig model.
  • Reasonable people can disagree whether offering a government guarantee to the retail and wholesale deposits of banks and shadow banks was wise at the height of the GFC. It is very much a rear-guard action to argue that five finance companies that now barely cobble together $1/2 billion in assets warrant the attention of the Minister of Finance when planning for the next financial crisis. The purpose of both the preceding and the coming discussions of deposit insurance for banks is to show that setting up a deposit insurance scheme is a nuanced policy trade-off for banking but not so for finance companies. Finance companies are a sideshow in any financial crisis and certainly never seed a banking crisis.

When deposit insurance is a pure bad for banks

  • Diamond and Dybvig were well-aware of the risk of moral hazard. They recommended a 1978 paper by Kareken and Wallace on deposit insurance because that paper was about what Diamond and Dybvig left out: moral hazard. Sargent (2010) summarises the Kareken and Wallace modelling as follows:
    • Kareken and Wallace compare that no-deposit-insurance situation to another situation in which a government agency provides deposit insurance that is either free or is priced too cheaply, meaning that it’s not priced with a proper risk-loading. Kareken and Wallace show that in that situation, banks have an incentive to become as risky as possible, and as large as possible. Therefore, with a positive probability, banks will fail and taxpayers will have to compensate banks’ depositors. It is in banks’ shareholders’ interest that the banks organize themselves this way. This lets them gamble with the insurers’ and depositors’ money. The Kareken and Wallace model’s prediction is that if a government sets up deposit insurance and doesn’t regulate bank portfolios to prevent them from taking too much risk, the government is setting the stage for a financial crisis (Roleck 2010).
  • From this angle, deposit insurance is now a pure bad that encourages risk-taking and crises unless bank portfolios are successfully regulated. The literature on regulation of bank portfolios is one of profound subtlety, where the correct amount of capital banks must hold is subject to intense debate (Aiyar, Calomiris and Wieladek 2015). The spotty record of regulators before the GFC also throws doubt on their ability to do better next time (Calomiris 2011, 2013). It is still debated as to whether the regulatory response to the GFC made things worse rather than better (Tarullo 2019).

Insured deposit takers take more risks

  • Gropp, Gruendi and Guettler (2014) studied the response of 452 German savings banks after government guarantees were removed, following a lawsuit in the European Court of Justice in 2001. As a group, savings banks in Germany have assets totalling 1 trillion Euro and 22,000 branches. Gropp, Gruendi and Guettler (2014) found that the German savings banks cut off their most risky borrowers and raised interest rates to the rest after the guarantee was removed. There were no similar effects in the control group of German banks to whom the guarantee was not applicable.
  • Lambert, North and Schuwer (2017) looked at what happened to insured deposits in 1,300 federally insured banks in the USA when their deposit insurance coverage was increased in October 2008 from $100,000 to $250,000. For some banks, the amount of insured deposits increased significantly. The most affected banks were found to increase their loans to risky commercial real estate, when compared to those banks that were largely unaffected by the deposit insurance limit change.

Risk-inviting rules of the game

  • The studies by Martin, Puri, and Ufier (2018), Iyer, Jensen, Johannesen and Sheridan (2019), Gropp, Gruendi and Guettler (2014) and Lambert, North and Schuwer (2017) show that depositors chase down government insured higher returns and that bankers take more risks when deposits are insured. The papers published by the Treasury and Reserve Bank to justify deposit insurance just don’t pick up on the nuances in the theoretical and empirical literature such as summarised by Thomas Sargent:
    • So, of those two models, the Kareken-Wallace model makes you very cautious about lender-of-last-resort facilities and very sensitive to the risk-taking activities of banks. The Diamond-Dybvig and Bryant model makes you very sensitive to runs and very optimistic about the ability of insurance to cure them. Both models leave something out, and I think in the real world we’re in a situation where we have to worry about runs and we also have to worry about moral hazard (Roleck 2010).
  • The policy trade-off regarding deposit insurance for banks is staving off bank runs while inviting banks to take on more risk in their lending. This is a far greater risk for US banks than for New Zealand banks, because the US still has thousands of small banks with less diversified loan portfolios (Calomiris 2008, 2011, 2013; Gorton and Winton 2003). The number of federally insured commercial banks in the US was 14,146 in 1934, 14,384 in 1975, 8,300 in 2000 and 4,377 in 2020. So many small banks in the US with few, if any branches, is why bank panics and bank runs are regarded as very much an American phenomenon in the economic literature, as Gorton and Winton (2003) explains:
    • On the basis of the stylized facts about cross-country banking history … it would seem straightforward to observe that banks are not fundamentally flawed institutions. In fact, it does not seem to be an exaggeration to say that most of the theoretical work on panics has been motivated by the USA experience, which has then been incorrectly generalized. Panics simply are not a feature of most economies that have banks. The world is more complicated; industrial organization seems to be at the center of the incidence of panics. Not surprisingly, therefore, almost all the empirical work on panics has been on the USA experience. Until bank “crises” around the world in the last ten years, there simply has not been much else to study (Gorton and Winton 2003, p. 508).
  • A British banking scholar would be likely to remember the names of each of their banks that failed over the last 200 years. By contrast, banks fail every year in the USA, as in the Federal Deposit Insurance Corporation chart below. 1,617 federally insured banks failed between 1980 and 1994 (Hane 1998).

Chart, line chart

Description automatically generated(Source: Federal Deposit Insurance Corporation)

  • There were many more banking crises over the last 40 years around the world. Their most common cause was ever more generous safety nets, including the moral hazard risks arising from the proliferation of deposit insurance starting in the 1970s and 1980s. The leading scholar in the field finds:
    • Recent research that investigates the determinants of banking fragility across different countries in the current era reaches a similar conclusion: the expansion of government-sponsored deposit insurance and other bank safety net programs throughout the world in the past three decades accounts very well for the increasing frequency and severity of banking crises in the current era. Empirical studies of this era of unprecedented frequency and severity of banking system losses has concluded uniformly that deposit insurance and other policies that protect banks from market discipline, intended as a cure for instability, have instead become the single greatest source of banking instability (Calomiris 2009).
  • The exposure draft of the Deposit Takers Bill plans to extend to the finance company sector what is a contentious policy instrument in the banking sector. Deposit insurance invites risk-taking but its redeeming feature is once the banking crisis it seeded occurs, it may quell a bank run or panic. When pondering deposit insurance for banks, the trade-off between the incentive to take more risks and seed a crisis must be weighed against the stabilising influence of deposit insurance when there is a crisis and the possibility of bank runs (Allen, Carletti, Goldstein and Leonello 2018; Gorton and Winton 2003).
  • Most countries initially manage banks in distress through the lender of last resort function. The central bank lends to a bank in distress against good collateral at a high rate (Bordo 1990, 2018; Gorton and Metrick 2013). The Reserve Bank would help a bank through its difficulties while its loans are restructured and the bank perhaps recapitalised. Any risk from lending against compromised assets of the distressed bank is factored into the interest rate charged with the capital base of that bank acting as a buffer against further losses on a lender of last resort loan. No one suggests that finance companies should have lender of last resort access.

No crisis management trade-off for finance companies

  • Reasonable people can disagree on whether deposit insurance destabilises the financial system by incentivising risk-taking more than it stabilises it by calming potential bank panics during a crisis:
    • Theory suggests that deposit insurance can either increase or decrease banking system risk. On the one hand, credible deposit insurance can make the banking system more stable by reducing liquidity risk. It does so by removing the incentive of depositors to withdraw funds from banks when bank risk increases. On the other hand, deposit insurance may be a source of “moral hazard”—it may increase the risk appetite of banks because their ability to attract deposits no longer reflects the risk of their portfolios. Deposit insurance can also cause “adverse selection,” including as the result of unwitting increases in risk when the absence of market discipline permits poor risk managers to operate banks. If the capital position and asset risk of banks are not regulated and supervised carefully, the insurance-induced risk taking may increase insolvency risk and undermine financial stability in the long run, despite the liquidity risk reductions that deposit insurance creates (Calomiris and Chen 2020).
  • The debate over deposit insurance for banks is nuanced. Observers must listen carefully to the competing arguments before making up their mind (Demirgüç-Kunt, Kane, and Laeven 2008; Calomiris and Jaremski 2016). Listeners to any debate must also guard against the protagonists making incorrect generalisations from the uniquely fragile US banking system, past and present (Gorton and Winston 2003). No such policy trade-off exists between moral hazard and better crisis management for deposit insurance for finance companies.

Back to the New Zealand situation

Just moral hazard

  • The five finance companies with barely $1/2 billion in assets between them will have no role in future financial crises. The sector is one-twentieth of its size at the eve of the GFC. The only policy issue here is that deposit insurance will encourage greater risk taking when finance company deposits are insured. What do taxpayers get back in return for this windfall to the finance company sector other than grief when taxpayers’ money is already short because of the COVID-19 debt crisis? The higher returns in the sector come off the back of greater risk taking. At some point, we must expect the investor to beware.

How much?

  • The discussion of the deposit insurance premium in the papers by the Treasury and the Reserve Bank focused on how long it will take to build a fund of a certain size relative the deposits to be insured. The Bank refers to 0.2% per year as a reasonable rate for the deposit insurance premium:
    • Looking at countries with banking systems and per capita GDP similar to New Zealand, a target size for a domestic insurance scheme of 2 percent of insured deposits would be large. At a per-depositor insurance limit of $30,000-$50,000, this implies an insurance fund of around $2-3 billion (Table 5B). The Review Team estimates this could be built up over a decade through a levy of 5 percent of the banking sector’s annual profits, or a premium of 20 basis points on banks’ insured deposits (Reserve Bank 2019, p. 92)
  • That was in 2019. A deposit insurance premium of 20 basis points is now about equal to the current return on an online call account – see the chart below. The same chart shows that term deposit rates are closing in on the 20 basis points deposit insurance premium and that narrowing gap charted is before tax. Interest rates on term deposits and on online call accounts dropped by about two thirds over the course of the review of the Reserve Bank legislation which started after the 2017 election. Deposit insurance has gone from clipping a small part of the interest return on deposits in 2019 to taking most or all of it in 2022.
  • The estimate of 20 basis point deposit insurance premium was off the back of advice from the Reserve Bank to have a deposit insurance limit per depositor of $30,000 to $50,000. The Government is planning a much larger deposit insurance limit of $100,000. It will either take many decades to build up to the reserve fund target or deposit insurance premiums must be much more than 20 basis points.
  • As it stands, taxpayers will not know how much they will pay for deposit insurance until the Minister of Finance issues a Statement of Funding after the Bill is enacted. Only then will depositors at banks, building societies, credit unions and deposit taking finance companies know how much they will pay and how quickly the Minister wants to accumulate the fund to a fully funded level of deposit insurance. That is unsatisfactory.

Government insured junk bonds

  • The interest rate paid by finance companies on six-month deposits is about twice that of banks. A fair insurance premium for deposit takers in the finance company sector would be large given their previous experience with risky lending, with related party lending and exposure to real estate development. Prior to the GFC, all but five of the sixty odd finance companies lacked a credit agency rating. The majority now do have credit ratings at a BB standing or less; see the table below.
Finance companyCredit rating agencyRating and outlook
Christian Savings LimitedFitch RatingsBB, Stable
FE Investments Limited (in receivership) n/aCredit ratings have been withdrawn
Finance Direct Limitedn/aExempt
General Finance LimitedEquifaxBB-, Positive
Gold Band Finance Limitedn/aExempt
Liberty Financial LimitedStandard & Poor’sBBB-, Stable
Mutual Credit Finance Limitedn/aExempt
Xceda Finance LimitedEquifaxB, Stable

Source: Reserve Bank

  • The BBB credit rating suggests investment grade; BB means a higher probability for default. BB and B bonds fall in the category of junk bonds, high-yield bonds or speculative instruments. The B rating suggests a company can meet its financial commitments but may be left highly exposed to adverse economic conditions. For Moody’s, BB and B bonds are speculative and “subject to a substantial risk of defaulting on certain senior operating obligations and other contractual commitments.” South Canterbury Finance was BBB rated when its deposits were guaranteed by the Crown in 2008.
  • It is a disservice to the taxpayer to contemplate deposit insurance for a sector that trades in what is mostly junk bonds. The previous pages presented ample evidence that investors watch deposit interest rates keenly especially if higher but riskier returns that are government insured come on the market. Crown deposit insurance will certainly encourage many retirees to re-enter the sector. Who wouldn’t be tempted to double the returns on their retirement savings for no extra risk because of the proposed Crown deposit guarantee? A canny retiree would deposit $100,000 with each of the five finance companies to bet on a sure thing.

Yours sincerely,
New Zealand Taxpayers’ Union Inc.

Jim Rose
Research Fellow
Jim@taxpayers.org.nz

References

Aiyar, Shekhar & Charles W Calomiris & Tomasz Wieladek, 2015. “Bank Capital Regulation: Theory, Empirics, and Policy,” IMF Economic Review vol. 63 (4), pp. 955-983, November.

Akerlof, George A., and Paul M. Romer, 1993. “Looting: The Economic Underworld of Bankruptcy for Profit,” Brookings Papers on Economic Activity vol. 24(2), pp. 1-74.

Allen, Franklin, Elena Carletti, Itay Goldstein and Agnese Leonello 2018. “Government guarantees and financial stability”. Journal of Economic Theory, Vol 177 pp. 518-557.

Auditor-General 2011. The Treasury: Implementing and managing the Crown Retail Deposit Guarantee Scheme. Office of the Auditor-General, Wellington.

Bordo, Michael D. “The Lender of Last Resort: Alternative Views and Historical Experience.” Economic Review (Federal Reserve Bank of Richmond), Vol. 76/1, pp. 18-29, (January/February 1990).

Bordo, Michael D. 2018. “An Historical Perspective on the Quest for Financial Stability and the Monetary Policy Regime,” The Journal of Economic History, vol 78(2), pp. 319-357.

Bordo, Michael D. and Angela Redish. “Why did the Bank of Canada Emerge in 1935?” Journal of Economic History, Vol. XLVII, No. 2, June 1987, pp. 405-4 17.

Bordo, Michael D., Angela Redish and Hugh Rockoff, 2015. “Why didn’t Canada have a banking crisis in 2008 (or in 1930, or 1907, or …)?,” The Economic History Review, vol 68 (1), pp. 218-243.

Bryant, John. 1980. “A Model of Reserves, Bank Runs, and Deposit Insurance. Journal of Banking & Finance 4(4), pp. 335–44.

Calomiris, Charles W., “Banking Crises,” In New Palgrave Dictionary of Economics, 2nd Edition, edited by Steven Durlauf and Lawrence Blume, 2009.

Calomiris, Charles W., “Banking crises yesterday and today,” Financial History Review, Cambridge University Press, vol. 17 (1), pp. 3-12, April 2010.

Calomiris, Charles W., “Banking Crises and the Rules of the Game,” In  Monetary and Banking History: Essays in Honour of Forrest Capie, edited by Geoffrey Wood, Terence Mills, and Nicholas Crafts, Routledge, 2011, pp. 88-132.

Calomiris, Charles W., “Banking Fragility of the United States, 1790-2009”. In Handbook of Key Global Financial Markets, Institutions, and Infrastructure, edited by Gerard Caprio, Charles W. Calomiris, and Larry Neal. London: Elsevier Press, 2013.

Calomiris, Charles W. and Sophia Chen, 2020. “The Spread of Deposit Insurance and the Global Rise in Bank Asset Risk since the 1970s,” Journal of Financial Intermediation, January.

Calomiris, Charles W. and Matthew Jaremski, 2016. “Deposit Insurance: Theories and Facts,” Annual Review of Financial Economics, vol. 8(1), pages 97-120, October.

Calomiris, Charles W., and E. N. White. “The Origins of Federal Deposit Insurance”, In The Regulated Economy: A Historical Approach to Political Economy, C. Goldin and G. Libecap (eds.), NBER, University of Chicago Press, 1994, pp. 145-188.

Carr, Jack, Frank Mathewson and Neil Quigley. “The Economics of Canadian Deposit Insurance.” Department of Economics Research Reports, 9502. London, ON: Department of Economics, University of Western Ontario (1995).

Demirgüç-Kunt, A., E.J. Kane, and L. Laeven (eds.), 2008, Deposit Insurance around the World: Issues of Design and Implementation (Cambridge, MA: MIT Press).

Diamond, Douglas W., and Philip H. Dybvig. 1983. “Bank Runs, Deposit Insurance, and Liquidity.” Journal of Political Economy 91(3), pp. 401–19.

Gorton, Gary, and Andrew Metrick. 2013. “The Federal Reserve and Panic Prevention: The Roles of Financial Regulation and Lender of Last Resort.” Journal of Economic Perspectives, 27 (4): 45-64.

Gorton, Gary, and Ellis Tallman, Fighting Financial Crises: Learning from the Past. Chicago: University of Chicago Press, 2018.

Gorton, Gary., and Andrew Winton. “Financial Intermediation”. In Constantinides, George, Milton Harris, and Rene Stulz (eds). The Handbook of the Economics of Finance Elsevier Science, 2003 pp 431-552.

Gropp, Reint., Christian Gruendl, and Andre Guettler. “The Impact of Public Guarantees on Bank Risk-Taking: Evidence from a Natural Experiment”. Review of Finance, Volume 18, Issue 2, April 2014, pp. 457–488.

Hane, George. “The Banking Crises of the 1980s and Early 1990s: Summary and Implications”. FDIC Banking Review, 1998 Vol. 11, No. 1, pp. 1-21.

Iyer R., Jensen, TL., Johannesen, N., and Sheridan, A. 2019. “The distortive effects of too-big-to-fail: evidence from the Danish market for retail deposits”, The Review of Financial Studies, Vol:32, pp. 4653-4695.

Kareken, John H., and Neil Wallace. 1978. “Deposit Insurance and Bank Regulation: A Partial-Equilibrium Exposition.” Journal of Business 51(July), pp. 413–38.

Laeven, Luc, 2013. “Corporate Governance: What’s Special About Banks?,” Annual Review of Financial Economics, vol. 5(1), pp. 63-92, November.

Lambert, C., F. Noth, and U. Schüwer (2014). “How do insured deposits affect bank risk? Evidence from the 2008 Emergency Economic Stabilization Act. Journal of Financial Intermediation 29 (October), pp. 81–102.

Martin, Christopher., Manju Puri and Alexander Ufier, 2018. “Deposit Inflows and Outflows in Failing Banks: The Role of Deposit Insurance,” NBER Working Papers 24589, National Bureau of Economic Research.

O’ Sullivan, Fran. “Vital witness missing at SCF trial”. New Zealand Herald, 15 October 2014.

Reserve Bank 2019. Safeguarding the future of our financial system In-principle decisions and follow-up questions on: The role of the Reserve Bank and how it should be governed Consultation Document 2A Phase 2 of the Reserve Bank Act Review June 2019. Reserve Bank of New Zealand, Wellington.

Rolick, A., 2010. “Interview with Thomas Sargent”. The Region, Federal Bank of Minneapolis, vol. 24, issue Sep, pp. 26-39.

Tarullo, Daniel K. “Financial Regulation: Still Unsettled a Decade After the Crisis.” The Journal of Economic Perspectives 33, no. 1 (2019): 61–80.

Scott Freeman’s textbook on the GFC

Scott Freeman on Endogenous Cycles and Growth with Indivisible Technological Developments

Previous Older Entries

Libertarian Land

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Arin’s Substack

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

David Andolfatto

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Monetary Non-Neutrality

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Reason Magazine

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Coyote Blog

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Thoughts from the North

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Fardels Bear

A History of the Alt-Right

Vincent Geloso

Econ Prof at George Mason University, Economic Historian, Québécois

Bassett, Brash & Hide

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Truth on the Market

Scholarly commentary on law, economics, and more

The Undercover Historian

Beatrice Cherrier's blog

Matua Kahurangi

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Temple of Sociology

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Velvet Glove, Iron Fist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Why Evolution Is True

Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.

NoTricksZone

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Homepaddock

A rural perspective with a blue tint by Ele Ludemann

Kiwiblog

DPF's Kiwiblog - Fomenting Happy Mischief since 2003

The Dangerous Economist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Watts Up With That?

The world's most viewed site on global warming and climate change

The Logical Place

Tim Harding's writings on rationality, informal logic and skepticism

Doc's Books

A window into Doc Freiberger's library

The Risk-Monger

Let's examine hard decisions!

Uneasy Money

Commentary on monetary policy in the spirit of R. G. Hawtrey

Barrie Saunders

Thoughts on public policy and the media

Liberty Scott

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Point of Order

Politics and the economy

James Bowden's Blog

A blog (primarily) on Canadian and Commonwealth political history and institutions

Science Matters

Reading between the lines, and underneath the hype.

Peter Winsley

Economics, and such stuff as dreams are made on

A Venerable Puzzle

"The British constitution has always been puzzling, and always will be." --Queen Elizabeth II

The Antiplanner

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Bet On It

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

History of Sorts

WORLD WAR II, MUSIC, HISTORY, HOLOCAUST

Roger Pielke Jr.

Undisciplined scholar, recovering academic

Offsetting Behaviour

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

JONATHAN TURLEY

Res ipsa loquitur - The thing itself speaks

Conversable Economist

In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”

The Victorian Commons

Researching the House of Commons, 1832-1868

The History of Parliament

Articles and research from the History of Parliament Trust

Books & Boots

Reflections on books and art

Legal History Miscellany

Posts on the History of Law, Crime, and Justice

Sex, Drugs and Economics

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

European Royal History

Exploring the Monarchs of Europe

Tallbloke's Talkshop

Cutting edge science you can dice with