Labour proposes wiping 10% off of outstanding student loan balances for domestic borrowers that are not in arrears and who have not benefitted from fees-free study. That write-down will happen on 1 April.It proposes doing it again in 2031, and each year afterwards, for borrowers in good standing who have been NZ-based over the prior…
Some basics on incidence of student loan relief
Some basics on incidence of student loan relief
05 Oct 2026 Leave a comment
in applied price theory, economics of education, labour economics, labour supply, occupational choice, poverty and inequality, Public Choice, public economics, rentseeking
Did the ACA reduce mortality?
05 Oct 2026 Leave a comment
in applied price theory, econometerics, economic history, health economics, politics - USA Tags: health insurance
Many of us brought up related points at the time, but basically we were booed off the reservation: While recent research has provided evidence that the Medicaid expansions of the Affordable Care Act (ACA) reduced mortality, there is no evidence on the effect of the Affordable Care Act (ACA) net of the Medicaid expansions on…
Did the ACA reduce mortality?
Mamdani Promised To Freeze the Rent. Now His Rent Freeze Is in Court.
04 Oct 2026 Leave a comment
in applied price theory, economics of regulation, income redistribution, law and economics, Marxist economics, politics - USA, property rights, Public Choice, rentseeking, urban economics Tags: New York City, rent control
A lawsuit alleges New York City’s Rent Guidelines Board broke the law by arbitrarily predetermining the outcome.
Mamdani Promised To Freeze the Rent. Now His Rent Freeze Is in Court.
@TaxpayersUnion SUBMISSION ON THE FUNDING STRATEGY FOR THE DEPOSITOR COMPENSATION SCHEME @GeorgeSelgin
04 Oct 2026 Leave a comment
in applied price theory, business cycles, comparative institutional analysis, economic history, economics, economics of bureaucracy, economics of regulation, financial economics, history of economic thought, income redistribution, industrial organisation, macroeconomics, monetary economics, politics - New Zealand, Public Choice, rentseeking Tags: deposit insurance
16 September 2023
Financial Markets
The Treasury
PO Box 3724
Wellington 6140
By email sofaconsultation@treasury.govt.nz
cc: David Hargreaves
Manager, Policy Projects
Financial System Policy and Analysis Department
Reserve Bank of New Zealand
Wellington 6140
By email: dta@rbnz.govt.nz
DEPOSIT TAKERS ACT 2023: SUBMISSION ON THE TREASURY CONSULTATION PAPER ON THE STATEMENT OF FUNDING APPROACH – FUNDING STRATEGY FOR THE DEPOSITOR COMPENSATION SCHEME
About the Submitter
- This submission has been prepared for the New Zealand Taxpayers’ Union by Research Fellow Jim Rose. Jim is an economist with three decades experience in the public sector in New Zealand and Australia. He has worked at the Ministry of Business, Innovation and Employment, the Department of Labour, the Ministry of Social Development, and the New Zealand Treasury, and in Canberra for the Productivity Commission, the Department of Prime Minister and Cabinet, and the Department of Finance. Jim has a master’s degrees in economics from the Australian National University and a master’s degree in public policy from the National Graduate Institute for Policy Studies in Tokyo.
- Founded by David Farrar and Jordan Williams in 2013, the Taxpayers’ Union’s mission is Lower Taxes, Less Waste, More Transparency.
- We enjoy the support of some 200,000 registered members and supporters, making us the most popular campaign group championing fiscal conservatism and transparency. We are funded by our thousands of donors and approximately two percent of our income is from membership dues and donations from private industry.
- We are a lobby group, not a think tank. Our grassroots advocacy model is based on our international taxpayer-group counterparts, particularly in the United Kingdom and Canada, and similar to campaign organisations on the left, such as Australia’s Get Up, New Zealand’s ActionStation, and Greenpeace.
- The Union is a member of the World Taxpayers Associations – a coalition of taxpayer advocacy groups representing millions of taxpayers across more than 60 countries.
- We give permission for the Treasury to publish this submission.
The Treasury and Reserve Bank consultation papers on deposit insurance implementation
- The Treasury has released a consultation document on the proposed funding approach by the Minister of Finance. This document discusses how quickly the deposit insurance reserve fund might accumulate towards a target reserve amount over 10 or 20 years then no further levies will be charged. The reserve target proposed by the Treasury would be between 0.5% and 1.1% of insured deposits at the end of an accumulation period of up to 20 years. This would result in a deposit insurance reserve fund of between $600 million and $1.4 billion when the target is reached.
- The Reserve Bank has released a consultation document on what deposit insurance levies might be charged to deposit takers. This document discusses whether there should just be a general levy of 0.1% on insured deposits. This means the same levy of about 10 basis points for all deposit takers irrespective of individual risk. The alternative proposal is that the pricing of deposit insurance should be risk-based. Among the possibilities floated is a deposit insurance risk-based premium based on credit ratings or the allocation of deposit takers to four risk buckets. The proposed risk-based premium would range from 10 basis points for the safest of the banks to 40 basis points as a maximum.
Our previous submissions on deposit insurance
- By way of background, the Taxpayers’ Union met with the Treasury in October 2020 on deposit insurance and the risk of fraud in the finance company sector. We made a submission to the public consultation on the draft Deposit Takers Bill pursuing those themes, and we made a submission to the Select Committee along with an appearance before that Committee.
- The themes of those submissions were the poorly thought-out rationale for deposit insurance and the unwise decision to extend it to the finance company sector. Reasonable people can disagree about the wisdom of deposit insurance for banks, about whether to have it at all and how much cover to offer. Not so for finance companies.
- We submitted that implementing deposit insurance for finance companies would be a short-sighted policy and must be considered as a policy option distinct from deposit insurance only for banks. Finance companies operate within a different set of moral hazard concerns than banks do, which deposit insurance schemes interact with to drive the sort of risk-seeking behaviour that makes the Crown deposit guarantee more likely to be activated. Economic stability is, however, not protected by deposit insurance for finance companies, in the same way it might be for banks.
- Finance companies now account for a tiny share of deposit taking institutions. The deposit guarantee put in place for finance companies at the height of the GFC was of dubious value, even with their twenty times larger than now share of the deposit taking market in 2008. While there is a valid debate as to the correct policy about insuring deposits in banks, the case is settled that finance companies should not be included in a deposit insurance scheme such as the one proposed in the Deposit Takers Bill. We recommended to the Select Committee that finance companies be removed from the Bill.
Scope of our current submission
- This submission on behalf of the Taxpayers’ Union is limited to discussing the reserve fund target, the preferred reserve fund target size, and the realism of the deposit taker failure scenarios. We will also discuss what we see as gaps in the analysis in the consultation paper. Our special focus will be managing the fiscal risks to the taxpayer from the implementation of a successful deposit insurance scheme that includes finance companies, in particular, and credit unions and building societies.
- The Taxpayers’ Union will be making a submission to the Reserve Bank on its consultation paper on the deposit insurance levy framework. That submission will focus on the need for the deposit insurance premium to be risk-based and that that will not be possible if the deposit insurance reserve fund has a target set for it by the Minister. Gaps in analysis will also be discussed in that submission.
Key points in this submission
- Deposit insurance is to be offered to a mixed bag: banks with a remote possibility of failure and finance companies whose credit ratings often imply a default probability of one chance in 10 in the next five years. Most building societies and credit unions are not much better.
- There should be sub-targets for the reserve fund for premiums collected from banks and for premiums collected from non-bank deposit takers to make transparent the level of insurance coverage to each sector and when payouts on deposit insurance constitute a cross-subsidy.
- Investors will move back into the non-bank deposit taking sector because deposit insurance will remove risk. They will keep their deposits with any one institution at no more than the deposit insurance coverage limit of $100,000.
- We would prefer that there should not be a target for the deposit insurance reserve fund at all because having a target rules out the possibility of risk-based deposit insurance premiums. Once the target is reached, no further premiums are charged so the deposit insurance becomes free.
- The recent bank runs overseas illustrate how difficult it is for governments to not honour implied guarantees for all deposits with banks and banks to be bailed out when they take excessive risks.
- The recent bank runs overseas should have led the Treasury to consider a larger, more fortified reserve fund to be accumulated perhaps over a longer time-period such as 30+ years.
- The motivation for our submissions has been that deposit insurance is a dicey policy tool because of moral hazard. The recent bank failures overseas should have led to some refection on this moral hazard dilemma by the Treasury and the Reserve Bank but that didn’t happen.
The deposit insurance funding approach to government insured junk bonds
- The statement of funding approach should take a clear tack on the mixed bag of deposit takers it plans to include in the Crown deposit guarantee. Some of these deposit takers are far more likely to call upon the deposit guarantee than others. In addition to nearly all banks having high credit ratings, the non-bank deposit takers have more questionable credit ratings but will receive a deposit guarantee, nonetheless. Prior to the global financial crisis (GFC), all but five of the sixty odd finance companies lacked a credit agency rating, but they still received a temporary Crown deposit guarantee.
- The majority of the seven remaining finance companies now do have credit ratings at a BB standing or less; see table 1 below which shows their credit ratings as well as a standardised explanation of default probabilities. The same table shows the credit ratings and the default probabilities implied by those ratings for the credit unions and building societies. The appendix to this letter has a full explanation of the default probabilities implied by all the ratings issued by the three credit rating agencies.
Table 1: Non-bank deposit taker credit ratings
| Deposit taker | Credit rating agency | Rating & outlook | Approx probability of default over 5 years |
| Christian Savings Ltd | Fitch Ratings | BB, Stable | 1 in 10 |
| FE Investments Ltd (in receivership) | n/a | Credit ratings withdrawn | |
| Finance Direct Ltd | n/a | Exempt | |
| General Finance Ltd | Equifax | BB-, Positive | Low to moderate risk |
| Gold Band Finance Ltd | n/a | Exempt | |
| Liberty Financial Ltd | Standard & Poor’s | BBB-, Stable | 1 in 30 |
| Mutual Credit Finance Ltd | n/a | Exempt | |
| Xceda Finance Ltd | Equifax | B, Stable | Moderate to high risk |
| Credit Union Auckland | Equifax | CCC+, Negative | A very high level of risk |
| First Credit Union Inc. | Fitch Ratings | BB, Stable | 1 in 10 |
| Fisher & Paykel Credit Union | Exempt | ||
| Police and Families Credit Union | Equifax | BB+, Stable | Low to moderate risk |
| Unity Credit Union | Fitch Ratings | BB, Negative | 1 in 10 |
| Heretaunga Building Society | Exempt | ||
| Nelson Building Society | Fitch Ratings | BB+, Stable | 1 in 10 |
| Wairarapa Building Society | Fitch Ratings | BB+, Stable | 1 in 10 |
Sources: Reserve Bank at https://www.rbnz.govt.nz/regulation-and-supervision/cross-sector-oversight/registers-of-entities-we-regulate/register-of-non-bank-deposit-takers-in-new-zealand and https://www.rbnz.govt.nz/regulation-and-supervision/oversight-of-banks/standards-and-requirements-for-banks/bank-credit-ratings and Equifax at https://nzcuauckland.co.nz/assets/files/info-files/Credit-Union-Auckland-Credit-Rating-June-2023.pdf, https://generalfinance.co.nz/service/credit-rating/, https://www.xceda.co.nz/media/ntfcqtku/equifax-credit-rating-interim-full-year.pdf, and https://www.policecu.org.nz/documents/167/PFCU_Credit_Rating__Synopsis_Dec22_.pdf
- The BBB credit rating suggests investment grade; BB means a higher probability for default. BB and B bonds fall in the category of junk bonds, high-yield bonds, or speculative instruments. The B rating suggests a company can meet its financial commitments but may be left highly exposed to adverse economic conditions. For Moody’s, BB and B bonds are speculative and “subject to a substantial risk of defaulting on certain senior operating obligations and other contractual commitments.” As an example, South Canterbury Finance was BBB rated when its deposits were guaranteed by the Crown in 2008. This implies a probability of failure of one chance in 30 in the next five years.
- Several of the finance companies in Table 1 have a one chance in 10 probability of default over the next five years – see table 1 above, columns three and four. The building societies and credit unions are not much better in their credit ratings. That high risk to be taken onto the Crown portfolio because of the Crown backstop should be considered when deciding the target size for the reserve fund.
- Their current credit ratings suggest that a finance company, credit union or building society might make an early call on the deposit guarantee before the reserve fund accumulates to the target set by the Minister. This will mean the Crown backstop to the deposit insurance reserve fund will be called upon rather early in the life of the deposit insurance scheme. The banks will be paying into that same reserve fund so their premiums will be cross-subsidising any early call by the credit unions, the finance companies, or the building societies on the freshly minted deposit insurance reserve fund. This high risk of a default by a credit union, a building society or a finance company crosses over into the setting of the deposit insurance premium. We will be writing separately to the Reserve Bank on this matter regarding the Bank’s consultation paper on the deposit insurance levy framework.
Deposits flooded into finance companies off the back of the 2008 Crown deposit guarantee
- The Statement of Funding Approach should consider the probability, the high probability, that there will be a surge of deposits into the higher risk non-bank deposit taking sector. This happened in the past at home and abroad off the back of government guarantees of retail deposits.
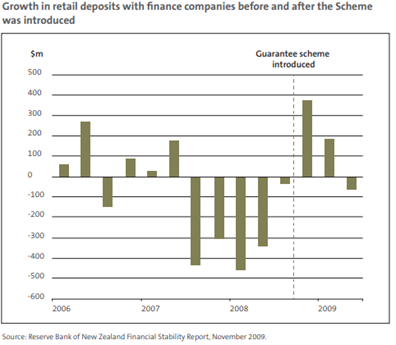
- After bleeding money in 2007 and 2008, there is a surge in deposits after the 2008 Crown guarantee for finance companies, see the chart below from the report by the Auditor-General (2011). South Canterbury Finance grew by 25% in deposits after the Crown guarantee (Auditor-General 2011); deposits in South Canterbury Finance increased from $75 million in 2004 to $2 billion in 2008 (O’Sullivan 2015). Another company grew from $800,000 in deposits to $8 million in deposits off the back of the Crown retail deposit guarantee (Auditor-General, 2011).
- There is little discussion in the Treasury and Reserve Bank papers of the implications of the deposit guarantee for a resurgence of investor interest in what is an intrinsically riskier sector. There is no mention in the Reserve Bank and Treasury papers of the massive surge in investment in finance companies after the 2008 Crown retail deposit guarantee, as shown in the chart below from the report by the Auditor-General. Instead of bleeding $500 million every quarter as in the lead up to the GFC, $600 million flooded back into the sector off the back of the Crown retail deposit guarantee.
- The previous experiences of the Treasury in administering the Crown deposit guarantee after the global financial crisis is barely mentioned in the consultation paper. That is unsatisfactory because the Auditor-General’s report was highly critical of the Treasury’s administration of that scheme.
- Now as then, the Treasury (and the Reserve Bank) appear to be aloof to the mercurial nature of deposit insurance as a policy instrument. It can bite back at the taxpayer big time as the 2008-2011 scheme certainly did. The deposit guarantee has not been jumbled together in a few days as was the guarantee cobbled together at the height of the GFC. This reincarnation is years in the making.
- The Auditor-General’s 2011 review found that the Treasury was focused on how to pay out depositors with little regard to how to reduce risk to the Crown by offering deposit insurance to failing finance companies. Indeed, the Crown deposit guarantee was renewed for South Canterbury Finance despite the Treasury having concluded at the time that the finance company was likely to fail:
The Treasury received the inspector’s report on 17 July 2009. The report reaffirmed the seriousness of the risk factors suspected with the books and management of South Canterbury Finance. From April to August 2009, the Treasury investigated the affairs of South Canterbury Finance extensively. On 12 August 2009, the Treasury made a provision for the estimated loss if South Canterbury Finance failed. This provision reflected the Treasury’s judgment that South Canterbury Finance was more likely than not to fail. The provision was made with the benefit of the inspector’s report (Auditor-General 2011, p.103).
- Would a fair deposit insurance premium towards the end be perhaps up to one-half of South Canterbury Finance’s deposits under a Crown guarantee? To quote the Audit report again:
The Treasury’s monthly financial statements did not include any provisions for pay-outs under the Scheme until June 2009, when the provision was estimated at $0.8 billion. The Treasury knew before June 2009 that further failures of finance companies were likely, so this information should have been better reflected in the monthly financial statements earlier than June 2009 (Auditor-General 2011, p.94).
- About $1.6 billion of the $2 billion in initial losses to the Crown from the deposit guarantee were from the failure of South Canterbury Finance. The Treasury didn’t face up to the facts as early as it should have with the 2008-2011 Crown deposit guarantee to finance companies. History is repeating.
Depositors chase riskier returns when government insured
- The proposition that depositors will invest in higher risk returns if they are government insured is well-established overseas. The burst of deposits back into the finance company sector after the government guarantee in New Zealand in 2008 is not an anomaly to be dismissed.
- For example, Martin, Puri, and Ufier (2018) examined the daily account level balances of a distressed bank in the USA at the height of the GFC. They studied the outflow (bank run-off) of uninsured depositors and the inflow (bank run-in) of insured deposits as this bank was in its death throes. The maximum level of federal deposit insurance increased from $100,000 to $250,000 per account holder as a stabilisation measure at the height of the GFC in 2008.
- Martin, Puri, and Ufier (2018) found that this failing bank was able to replace about 1/3rd of its depositor base in its last year of life. This was despite public knowledge of the intensive regulatory scrutiny of its declining condition. Much of these new deposits came in in the last 90 days of the bank. The bank’s regulatory filings spoke of being significantly undercapitalised and then a critically undercapitalised financial state. The new deposits were almost all term deposits paying slightly above market interest rates and were just under the Federal Deposit Insurance Corporation insurance limit. These deposits initially bunched at the $100,000 limit, then bunched at the $250,000 insurance limit when this limit was increased at the height of the GFC in October 2008.
- Iyer, Jensen, Johannesen and Sheridan (2019) had access to all personal deposit accounts and their balances in Denmark when they studied changes in deposit insurance for Danish banks. The Danish government guaranteed all bank liabilities in 2008. Prior to the GFC, deposit insurance was limited to 300,000 Danish kroner. The Danish government later limited deposit insurance to 750,000 Danish kroner in 2011. The Danish government also named six Danish banks as too big to fail.
- Iyer, Jensen, Johannesen and Sheridan (2019) found that for the banks that were not too big to fail, accounts clustered around the insurance limit of 750,000 Danish kroner. There was no similar bunching of deposits at the deposit insurance limit for the six large banks deemed by the Danish Government to be too big to fail. Canny Danish depositors quickly sifted out where their deposits were fully guaranteed by the Danish government and where they were only partially guaranteed. Iyer, Jensen, Johannesen and Sheridan (2019) also found the deposits above the insurance limit of 750,000 Danish kroner halved in the smaller banks that were not too big to fail but fell only by 20% in the six large banks that were marked by the Danish government as too big to fail.
- Belgian depositors were just as canny as their Danish neighbours in sifting through the incentives behind explicit and implicit government guarantees. Atmaca, Kirschenmann, Ongena and Schoors (2020) used micro-data on 300,000 Belgian depositors of a large European bank during 2008 and 2009. In November 2008, Belgian deposit insurance was increased from €20,000 to €100,000 per customer-bank relation. The bank under study, like several other EU banks, was first nationalised and then re-privatised. In the run up to the GFC, more and more depositors limited their deposits to €20,000 for full coverage. Once coverage is increased to €100,000, €100,000 bunching largely substituted for €20,000 bunching. This €100,000 bunching faded away during the period of nationalisation, when implicit blanket guarantees apply. It then returned in full force once the bank was re-privatized and the new €100,000 coverage limit was the binding guarantee for the depositors.
Insured deposit takers take more risks
- It is well-established that deposit takers respond strongly to the introduction of deposit insurance or an increase in coverage. Lambert, North and Schuwer (2017) looked at what happened to insured deposits in 1,300 federally insured banks in the USA when their deposit insurance coverage was increased in October 2008 from $100,000 to $250,000. For some banks, the amount of their federally insured deposits increased significantly. The most affected banks were found by Lambert, North and Schuwer (2017) to increase their loans to risky commercial real estate, when compared to those banks that were largely unaffected by the federal deposit insurance limit increase.
- Gropp, Gruendi and Guettler (2014) studied the response of 452 German savings banks after government guarantees were removed, following a lawsuit in the European Court of Justice in 2001. As a group, savings banks in Germany have assets totalling 1 trillion Euro and 22,000 branches. Gropp, Gruendi and Guettler (2014) found that the German savings banks cut off their most risky borrowers and raised interest rates to the rest after the guarantee was removed. There were no similar effects in the control group of German banks to whom the guarantee was not applicable.
- Calomiris and Jeremski (2019) looked at eight state deposit insurance schemes that were open to state charted banks but not federally chartered banks. They found that the insured state-chartered banks competed aggressively for deposits with their uninsured rivals, reduced capital ratios and were more likely to fail. Wheelock (1992), Wheelock and Kumbhakar (1995) and Wheelock and Wilson (1994, 1995) found that the less solvent, and less efficient banks joined a voluntary state deposit insurance scheme in Kansas, and they were twice as likely to fail as similar uninsured banks. A strong institutional background is required to manage this risk of depositors chasing down government insured higher returns and deposit takers taking more risks in lending when their deposits are insured by the Crown.
Managing risk-inviting rules of the game
- There were many more banking crises over the last 40 years around the world. Their most common cause was ever more generous safety nets, including the moral hazard risks from the proliferation of deposit insurance starting in the 1980s. The leading scholar in the field finds that:
- Recent research that investigates the determinants of banking fragility across different countries in the current era reaches a similar conclusion: the expansion of government-sponsored deposit insurance and other bank safety net programs throughout the world in the past three decades accounts very well for the increasing frequency and severity of banking crises in the current era. Empirical studies of this era of unprecedented frequency and severity of banking system losses has concluded uniformly that deposit insurance and other policies that protect banks from market discipline, intended as a cure for instability, have instead become the single greatest source of banking instability (Calomiris 2009).
- Deposit insurance, such as that to be rolled out in New Zealand, invites risk-taking but its redeeming feature is once the banking crisis it seeded occurs, it may quell a bank run or banking panic (Anginer, Demirgüç-and Zhu 2014). When pondering deposit insurance for banks, there is a subtle policy trade-off between the incentive to take more risks and seed a banking crisis must be weighed against the stabilising influence of deposit insurance when there is a banking crisis and the possibility of bank runs (Allen, Carletti, Goldstein and Leonello 2018; Gorton and Winton 2003). Reasonable people can disagree earnestly over whether the financial policy trade-off between encouraging moral hazard and a better banking crisis management tool kit justifies offering deposit insurance to banks.
- The consultation paper by the Treasury does not state clearly that the non-bank deposit takers are a far greater risk than banks, and that they are far more likely to draw on the deposit insurance reserve fund. What taxpayers are getting in return for these fiscal risks as the Crown backstop is not stated.
- At their peak in 2008, there were about 65 finance companies. Half of them failed inside of two years with no implications for the stability of the banking system. As the then Governor of the Reserve Bank reflected later in his book on his crisis management decision making about the finance companies:
- At the end of 2006 and in early 2007, we started to hear about property finance companies in trouble. Most were very small, and as individual failures they did not greatly concern us. But in the second half of the 2007, bigger finance companies started to fall like flies. As each one entered into liquidation, receivership or moratorium, media speculation turned to the next. We saw angry scenes of elderly debenture holders haranguing hapless managers at meetings. The pattern seemed clear: poor governance, spider-web company structures, vulnerable business models, mismatched balance sheets, bad management and inadequate supervision by the trustee companies. At the Reserve Bank we started to worry: were the combined failures big enough to lead to a deposit run on the banks? The answer seemed to be no; in fact the banks were benefitting from a flight to quality. Did the failures point to fragile business models and practices in the banks themselves? Again, we thought not, the banks being much more sophisticated organisations than many finance companies (Bollard 2013).
- The seven finance companies still in operation have $600 million in deposits and will have no role in future financial crises. The Governor of the Reserve Bank in 2008 dismissed the sector as a possible spark for bank runs. The finance company sector is now one-fifteenth of its size at the eve of the GFC.
- There is no trade-off between moral hazard and better crisis management from deposit insurance for finance companies or for the other non-bank deposit takers. The Reserve Bank observed in its consultation paper that “… (building societies and credit unions) has shown an ability to manage distress in the sector through mergers and acquisitions”. Three building societies converted to banks in the last 15 years. In 2022 alone, the Firefighters Credit Union merged with NZCU Auckland, Westforce Credit Union merged with First Credit Union, and Steelsands Credit Union merged with First Credit Union. There are five credit unions left, down from 13 in 2018. The Unity Credit Union is the product of more than 10 mergers after starting in a freezing works in 1971. In the early 1980s, there were several hundred credit unions. There were no implications for the stability of banks from these many reorganisations among the non-bank deposit takers. The only policy issue is deposit insurance will encourage greater risk taking after the non-bank deposit takers are insured by the Crown.
The deposit insurance reserve fund and access to the lender of last resort function
- The consultation papers from the Treasury and from the Reserve Bank barely allude to the access that banks have to the lender of last resort function at the Reserve Bank. This lender of last resort access greatly reduces the likelihood of the banks calling upon the deposit insurance offered by the Crown. The lender of last resort function duplicates much of the role of deposit insurance. Both policy tools assure jittery depositors that their bank balances are safe (Bordo 1990, Humphrey and Keleher 1984).
- Most countries initially manage banks in distress through the lender of last resort function. The central bank lends to a bank in distress against good collateral at a high rate (Bordo 1990, 2018; Gorton and Metrick 2013). The Reserve Bank would help a bank through its difficulties while its loans are restructured and the bank perhaps recapitalised. Any risk from lending against compromised assets of the distressed bank is factored into the interest rate charged with the capital base of that bank acting as a buffer against further losses on a lender of last resort loan. No one suggests that finance companies or other non-bank deposit takers should have lender of last resort access.
- Finance companies, credit unions and building societies have nowhere to go except the Crown deposit guarantee if things go bad. We will be writing separately to the Reserve Bank about how its consultation paper is also quiet on the interaction of the lender of last resort function and fair deposit insurance premiums. The deposit insurance premium to be paid by the banks should take account of their access to lender of last resort facilities. They can call on the lender of last resort function for help before they need to rely on payouts from the deposit insurance reserve fund.
- A glaring anomaly in debates about deposit insurance is the tenacious stability of the Canadian banking system. The last bank failure, bar one, in Canada was in 1923; the 1923 bank failure was due to fraud (Bordo 1990; Bordo, Redish and Rockoff 2015). Canada’s banks sailed through the Great Depression and the GFC because it had large banks with diversified loan portfolios (Bordo and Redish 1987; Bordo, Redish and Rockoff 2015). Thousands of banks failed in the USA because they lacked a national branch networks and diversified loan portfolios (Calomiris and Jaremski 2016).
- New Zealand also has five large banks with diversified loan portfolios. They are very unlikely to call on the deposit insurance reserve fund because any crisis is likely to be resolved through the lender of last resort function assisting with a bank recapitalisation. Twenty-three of the 27 registered banks listed in table A2 of the appendix to this letter and all the major banks in New Zealand have ‘A’ or ‘AA’ credit ratings. The ‘AA’ credit ratings imply a one chance in 300 of that bank failing in the next five years; the ‘A’ credit rating implies a probability of failure in the next five years of one chance in 150.
- The policy trade-off regarding deposit insurance for banks is staving off bank runs while inviting banks to take on more risk in their lending. But failure is a far greater risk for US banks than for New Zealand banks. This is because the US still has thousands of small banks with less diversified loan portfolios (Calomiris 2008, 2011, 2013; Gorton and Winton 2003). The number of federally insured commercial banks in the US was 14,146 in 1934, 14,384 in 1975, 8,300 in 2000 and 4,377 in 2020. So many small banks in the US with few, if any branches, is why banking panics and bank runs are regarded as very much an American phenomenon in the economic literature. As Gorton and Winton (2003) explain:
- On the basis of the stylized facts about cross-country banking history … it would seem straightforward to observe that banks are not fundamentally flawed institutions. In fact, it does not seem to be an exaggeration to say that most of the theoretical work on panics has been motivated by the USA experience, which has then been incorrectly generalized. Panics simply are not a feature of most economies that have banks. The world is more complicated; industrial organization seems to be at the center of the incidence of panics. Not surprisingly, therefore, almost all the empirical work on panics has been on the USA experience. Until bank “crises” around the world in the last ten years, there simply has not been much else to study (Gorton and Winton 2003, p. 508).
- A British banking scholar would be likely to remember the names of each of their banks that failed over the last 200 years. North Rock is the only British bank to have failed since 1866. By contrast, banks fail every year in the USA. This includes the hundreds of bank failures during and after the GFC. A total of 1,617 federally insured banks failed between 1980 and 1994 (Hane 1998).
- Non-bank deposit takers are a different story to our banks because they have much lower credit ratings and lack access to a lender of last resort facility. The B, BB and BBB credit ratings for non-bank deposit takers in table 1 several pages above represent a large break in default probabilities as compared to the A and AA ratings of banks. A BBB credit rating implies a default probability of one chance in 30 in the next five years. Liberty Finance Limited is the only finance company in table 1 above with such a credit rating. The BB ratings for two finance companies and for the three building societies in table 1 above imply a failure probability in the next five years of one in 10. The credit unions are not much better in financial strength. This high level of risk should be considered by the Minister when setting premiums to ensure the reserve fund is of sufficient size based on contributions from non-bank deposit takers to self-fund any payouts to any of the non-bank deposit takers that fail. Deposit insurance will be their first port of call in a crisis rather than the lender of last resort function.
Only banks should be as safe as a bank
- Given the local and overseas evidence just summarised, there is every reason to believe that the finance companies, in particular, and the building societies and credit unions will take advantage of Crown deposit insurance to tout themselves as ‘as safe as a bank’ to win more deposits. Currently, as shown in the chart below, finance companies must offer a risk premium of 75 to 120 basis points over the major banks to attract 12-month term deposits. Building societies and credit unions usually offer a 10 to 20 basis points more than the major banks for term deposits.
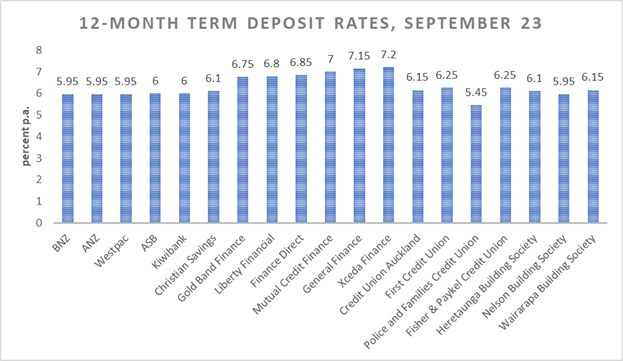
Source: web scrapings of deposit taker web sites
- Gatti and Oliviero (2021) looked at what happened to the retail deposit interest rates of Eurozone banks after the European Union increased the minimum deposit insurance coverage for banks from €20,000 to €200,000 per bank account in 2009. Italian banks already had deposit insurance cover of €103,291. They found that compared to the Italian banks, the banks in the rest of the Eurozone reduced their interest rates by between 30 basis points and 70 basis points after they received more deposit insurance coverage. Gatti and Oliviero (2021) also found that the fall in deposit interest rates were largest among the riskier banks. There is every reason to believe that finance companies, in particular, and the credit unions and building societies in New Zealand will find it easier to attract deposits without having to offer as much as in the past in interest rates on deposits.
A deposit insurance reserve fund target fit for junk bonds
- The record with the Crown deposit guarantee scheme between 2008 and 2011 and the overseas experience with changes in deposit insurance limits show conclusively that investors will run back into the sector because the finance companies, credit unions and building societies are once again provided with Crown deposit insurance. These deposit takers have a higher probability of default than the banks. They will draw down on the deposit insurance reserve fund that is to be mainly built up by the banks and this will constitute a cross-subsidy between groups with very different risk profiles. A fair deposit insurance premium for the finance company sector would be large given their previous experience with risky lending, with related party lending and exposure to real estate development.
- Crown deposit insurance will encourage many retirees to re-enter the finance company sector. Who wouldn’t be tempted by higher returns for no extra risk because of the Crown deposit guarantee? A canny retiree would deposit $100,000 with each of the six finance companies to bet on a sure thing. The previous pages presented ample evidence that investors watch deposit interest rates keenly especially if higher but riskier returns that are government insured come on the market.
- The funding approach to the reserve fund must take account of the likely rapid growth of the higher risk deposits takers. The reserve fund must build at a rate that will consider the possibility of an early call for compensation from a failing finance company, a failing building society or a failing credit union because of this rapid growth in their deposits and risky lending. The deposit insurance premium must be risk-based. This is a possibility subject to a separate consultation process by the Reserve Bank.
- The Minister must choose the funding approach and fund size that reflects the likely more frequent calls from the non-bank deposit takers so there are no cross-subsidies between the banks and the other deposit takers. In addition to a risk-based deposit insurance premium, which is a must, the Minister should consider setting separate sub-targets for funds accumulated from deposit insurance premiums from the banks and for deposit premiums from the other deposit takers.
- Separate targets should be set because banks are much less likely to call upon the deposit insurance reserve fund and the Crown backstop because of the lender of last resort facility. Non-bank deposit takers do not have this option in a crisis. Their credit ratings imply that they are also far more likely to fail than the banks. The range proposed for the size of the fund in the consultation paper by the Treasury of between 0.6% and 1.1% of insured deposits is not helpful because most of the calls on the deposit insurance reserve fund will come from non-bank deposit takers. Premiums from the non-bank deposit takers will be a small part of the funds accumulated but a large part of the payouts.
The severe deposit taker failure scenarios hint at a cross-subsidy
- Table 4 of the consultation paper sets out the funding requirements for the deposit compensation scheme for severe but plausible failures scenarios for major banks, medium-sized banks and for the non-bank deposit takers sector. The failure scenario for the non-bank deposit takers sector is for
- widespread liquidations requiring an upfront pay out to depositors of $800 million-$900 million. After recoveries, the likely cost of this scenario is estimated to be $100 million-$400 million.
- This payout scenario for the non-bank deposit takers before recoveries and after recoveries is far larger than any reasonable amount of premiums that could be accumulated from the non-bank deposit takers sector even over several decades. As can be seen from the chart below, deposits with the building societies and credit unions have been growing strongly in the last decade but are just $2 billion. The finance company sector is a shadow of its former self; a $9 billion peak in deposits in 2007. Their deposits are now $585 million, which is up 20% on their low two years ago in 2021.
Source: Reserve Bank at https://www.rbnz.govt.nz/statistics/series/non-banks-and-other-financial-institutions/deposit-taking-finance-companies-balance-sheet and https://www.rbnz.govt.nz/statistics/series/non-banks-and-other-financial-institutions/savings-institutions-balance-sheet
Notes: the three abrupt drops in building society/credit union deposits are due to the conversion of building societies into the Heartland, Cooperative and SBS banks. Data for finance companies appears to include FE Investments Ltd which entered receivership in March 2020 and Christian Savings Ltd.

- The finance companies are unlikely to pay more than $3 million per year in deposit insurance premiums. The building societies and credit unions are unlikely to pay more than $10 million per year in deposit insurance premiums given the current levy framework out for consultation from the Reserve Bank. This premium income will take decades to accumulate to the level where these premiums could cover the failure scenarios discussed in the consultation paper from the Treasury.
- Up until 2006, there were separate deposit insurance reserve funds in the USA for banks and for the other federally insured deposit takers. It is too late to have a similar structural separation in New Zealand now. But it is still possible to set separate accumulation sub-targets for premiums from non-bank deposit takers and premiums from banks and to have risk-based deposit insurance premiums.
No retreat from full funding by deposit takers of deposit insurance
- The failure scenarios put forward by the Treasury consultation paper say that a failure of a major bank even after the target for the reserve fund is reached would often require a drawing on the Crown backstop. This is to fund the initial pay out depositors pending partial or full repayment to the Crown through recoveries. Taxpayers will pay part of the initial cost of the resolution of a large bank failure.
- Deposit insurance is supposed to be self-funding through levies on deposit takers. The Minister of Finance reiterated this government policy when the Deposit Takers Bill passed Parliament. The Treasury has given up on this important safeguard for taxpayers at the first turn. Calls on the Crown backstop to the deposit insurance scheme should be limited to the rarest of rare major bank failures.
Setting deposit insurance premiums to target deposit insurance fund reserves
- We will be writing to the Reserve Bank to point out that the effect of setting deposit insurance premiums to have a reserve fund target has the effect of ruling out the possibility of risk-based deposit insurance. This is because the any decision to stop collecting premiums once the target is reached means that the deposit insurance is no longer risk-based. It is free. As Feldman explains:
- The policy of setting premiums based on the size of current reserves prevents, almost by definition, the setting of actuarially fair premiums. Reserves are backward looking, informing policymakers about past premiums and past payments to the insured. In contrast, the setting of fair premiums is an exercise in forecasting future losses that may not reflect what happened last year or the year before that. In this case, the FDIC (Federal Deposit Insurance Corporation) must currently give away insurance to the vast majority of banks because reserves exceed the targeted level. As a result, the FDIC essentially charges banks one flat rate for deposit insurance just as it did over the vast majority of its history, even though Congress ostensibly required premiums to vary by the risk of a bank failing in 1991 (Feldman 1998).
- George Pennacchi (1987, 2000, 2006, 2010) has written extensively on the interaction between deposit insurance premiums and targets for deposit insurance reserve funds. He argues that:
- Conventional economic theory maintains that a fairly priced deposit insurance for default-risk premium should reflect the current financial risk of the issuing institution. In particular, a fair premium should not be dependent directly on the past losses sustained by the insurer and, therefore, should not bear any direct relationship to the reserves of the insurance fund. From this perspective, it is puzzling that most insurance systems choose not to set fair insurance rates but set either flat rate premiums or premiums that target a fund’s reserves (Pennacchi 2000, p. 154).
- Setting a deposit insurance fund reserves target is fundamentally inconsistent with setting a risk-based deposit insurance premiums for deposit takers for the insurance provided by the Crown. For example, from 1991, the US Congress experimented with having both risk-based deposit insurance premiums and a target for their deposit insurance fund. This meant no further premiums were collected once the insurance fund reserves reached a target of 1.25% of insured deposits. That target was soon reached in 1995. No federal deposit insurance premiums were charged to almost all US banks in the 12 years leading up to the global financial crisis (Pennacchi 2010). That is hardly ideal in terms of encouraging banks to have regard for the risks in their portfolios and depositors to be wary of risky banks offering above-average returns on their deposits. Taxpayers will be very wary of having a target for the deposit insurance reserve fund because it turns into free deposit insurance once that target is reached.
Systemic risk and the deposit insurance reserve fund target
- Deposit insurance is not like other deposit insurance where risk arising from individual policy claims can be diversified by underwriting many policies as the risks are largely independent of each other.
- Most claims on deposit insurance will arise during recessions. Furthermore, the ability to recover deposit insurance payouts through sale of a distressed bank’s loans is more difficult during recessions because the real estate and other collateral offered by borrowers is also depressed in price. Therefore, deposit insurance losses are not diversifiable, they are systemic. As Pennacchi explains:
- The risks from underwriting multiple term life insurance policies or automobile collision policies can be diversified away by pooling the risks of several policies together. This is not the case for deposit insurance. The risks of deposit insurance losses due to bank failures cannot be diversified away by pooling the risks of many banks together because deposit insurance loss claims are not independent or uncorrelated events. Bank failures are linked to macroeconomic conditions which tend to create financial distress at many banks at the same time. This is not surprising since bank assets consist largely of real estate, commercial, and consumer loans which experience higher default rates during economic downturns. Thus, bank failures and deposit insurance losses rise during recessions and decline during expansions, so that they bear ‘systematic’ risk (Pennacchi 2010).
- Deposit insurance requires the Crown to take onto its portfolio business cycle risk from bank and non-bank deposit takers. It is not such as is the case with car insurance where the insurer gets a small profit or loss on his portfolio of policies. A deposit insurance fund should earn positive profits in the long-run as a premium for taking on business cycle or systemic risk. As Pennacchi explains:
- In terms of the Capital Asset Pricing Model (CAPM), underwriting deposit insurance is a positive ‘beta’ investment: during economic expansions (recessions) when stock market returns are high (low), a deposit insurer will make profits (losses) because premiums will be greater (less) than loss claims from bank failures. Thus, to compensate an insurer for the risk that losses will be highest during severe recessions, fair premiums must exceed expected losses. In other words, fair market deposit insurance premiums will contain a systematic risk premium in addition to expected losses so that a deposit insurer charging fair premiums will earn positive average profits (Pennacchi 2010).
- The deposit insurance premium that includes systemic risk in the premium means that the deposit insurance fund should grow indefinitely and indeed would have the capacity to pay a dividend to the Crown in recompense for taxpayers taking on systemic risk (Pennacchi 2000, 2006, 2010).
- Setting a target for the reserve fund and then charging no further premiums is a subsidy to deposit takers. It is the taking on of significant systemic risk or business cycle risk onto the Crown portfolio. This is because most of the losses, and especially in the case of non-bank deposit takers, from deposit insurance is from systemic risk from the business cycle (Jokivuolle and Pennacchi 2019).
Lessons from recent bank runs overseas
- There is no mention in the Treasury and Reserve Bank consultation documents of the bank runs in the USA and Switzerland or the pressures on all banks around the world from the recent large increases in inflation rates and nominal interest rates. Banks everywhere are suffering losses on their large long-term bond holdings, which they bought at ultra-low interest rates.
- Silicon Valley Bank tripled in size from the end of 2019 to the end of 2021 to have $200 billion in deposits. It invested mostly in long-term US Treasury bonds, mortgage-backed bonds, and municipal bonds. More than 90% of its at-demand deposits were not federally insured because of the large balances of most of its customers. Silicon Valley Bank was paying more than the other banks in interest on deposits because it was not hedging its interest rate risk. The Federal Reserve Bank of San Francisco expressed concerns about this with the Silicon Valley Bank but did not mandate corrective action.
- The Silicon Valley Bank was heavily exposed to a mismatch in duration in its portfolio and had an unusually large share of uninsured deposits. Silicon Valley Bank made unhedged bets that interest rates would stay very low for a long time (which was the Fed’s forward guidance at the time). It did not help that central banks everywhere said that the current inflationary burst was transitory driven by Covid-19 supply change disruptions that would soon subside and may even reverse themselves rather than from the expansionary monetary policy choices of those central banks in 2020 and after.
- The bank run started after Silicon Valley Bank announced on Thursday 8 March that it sold $21 billion in long-term securities for a loss of $1.8 billion. $42 billion in withdrawals were made the next day. $100 billion in withdrawals were sought the following day which the bank could not honour. The California State regulator put the bank into receivership with deposits guaranteed to the federal limit.
- Over the weekend, the Federal Deposit Insurance Corporation bailed-out all deposits at the Silicon Valley Bank and the Signature Bank and not just those up to the $250,000 federal deposit insurance limit. The Federal Deposit Insurance Corporation took over these banks and bailed them out to stem national and global financial jitters. For example, after a run on its deposits, the scandal plagued Credit Suisse was taken over by UBS in a rescue underwritten by the Swiss central bank. In 2007, Credit Suisse was worth 100 billion Swiss francs (SFr). On 19 March 2023, UBS bought it for SFr3 billion.
- When announcing the blanket deposit guarantee for the Signature bank, the Silicon Valley Bank and two other foundering banks, the Federal authorities strongly hinted that that a deposit guarantee would be extended to other banks if such action was necessary to stabilise the banking system.
Have we got this covered?
- None of these bank runs overseas are mentioned in the consultation documents with lessons for NZ. Taxpayers don’t know whether the deposit insurance being rolled out and our prudential regulation are robust to the forces behind the recent overseas bank runs! There is no evidence that the Treasury or the Reserve Bank have paused to consider these developments when rolling out deposit insurance.
- At a minimum, these bank runs against major global banks should have led the Treasury to consider a larger target fund to be accumulated perhaps over a longer time-period such as 30+ years. After the 30 years, the Minister of Finance can then decide on the wisdom of waiving in part or in full further deposit insurance levies because the deposit insurance fund has finally reached its target.
- The overseas banks collapsed because of a basic failure to hedge portfolios made up of large uninsured at-demand deposits and mostly long-term securities purchased at ultra-low interest rates. The Crown deposit insurance fund might need to be bigger than is currently planned in the consultation document to fortify it against a similar interest rate risk pushing a local bank into distress.
- Taxpayers deserve to know whether the Crown deposit compensation fund is robust to the interest rate risk behind the bank runs abroad and that the Treasury and Reserve Bank can adapt the implementation of Crown deposit insurance to events. All of the banks overseas subject to bank runs were in compliance with their regulatory standards until the day before they collapsed.
Polar opposite models of deposit insurance
- Another lesson for New Zealand from the recent bank runs overseas is the primary intellectual framework of policymakers at least in the USA is based on Bryant (1980) and Diamond and Dybvig (1983) models of bank runs. Banks have a maturity mismatch in their balance sheets, which Bryant (1980) and Diamond and Dybvig (1983) say is to blame for bank runs. Deposits are payable on demand, but most of these deposits finance long-term loans.
- Diamond and Dybvig (1983) argued that if too many depositors suddenly seek to withdraw, the bank will run out of cash despite being solvent. In a run, depositors are not reacting to news about the quality of the bank’s portfolio. Instead, they are withdrawing because they see others doing so and do not want to be left with a deposit in a bank with no cash reserves. The otherwise solvent bank then fails because a depositor panic forces the bank to sell good assets in a fire-sale.
- Importantly, in the Diamond-Dybvig (1983) model of bank panics, if there is government-supplied deposit insurance, depositors do not start bank runs because they trust that their deposits are safely insured by the taxpayer. The icing on the cake is that the deposit insurance under this Diamond-Dybvig scenario of bank runs costs the taxpayers nothing because there are no bank panics to stem.
- During the GFC, many governments seemed to see Diamond and Dybvig type panic-based bank runs everywhere and used deposit guarantees to quell the panic. As Thomas Sargent observed:
- When monetary policy authorities, deposit insurance authorities and others looked out their windows in the fall of 2008, they saw Bryant-Diamond-Dybvig bank runs all over the place. And the logic of the Bryant-Diamond-Dybvig model persuaded them that if they could arrest the runs by effectively convincing creditors that their loans—that is, their short-term deposits—to these “banks” were insured, that could be done at little or no eventual cost to the taxpayers. You could nip the run in the bud and really prevent the next Great Depression. This is a very optimistic view of those 2008 interventions enlightened by the Bryant and Diamond-Dybvig model (Rolick 2010).
- Diamond and Dybvig were well-aware of the risk of moral hazard. They recommended a 1978 paper by Kareken and Wallace on deposit insurance. That paper was about what the Diamond and Dybvig model left out: moral hazard. Sargent summarises the Kareken and Wallace modelling as follows:
- Kareken and Wallace compare that no-deposit-insurance situation to another situation in which a government agency provides deposit insurance that is either free or is priced too cheaply, meaning that it’s not priced with a proper risk-loading. Kareken and Wallace show that in that situation, banks have an incentive to become as risky as possible, and as large as possible. Therefore, with a positive probability, banks will fail and taxpayers will have to compensate banks’ depositors. It is in banks’ shareholders’ interest that the banks organize themselves this way. This lets them gamble with the insurers’ and depositors’ money. The Kareken and Wallace model’s prediction is that if a government sets up deposit insurance and doesn’t regulate bank portfolios to prevent them from taking too much risk, the government is setting the stage for a financial crisis (Rolick 2010).
- In the Kareken and Wallace (1978) model, deposit insurance encourages risk-taking and crises unless bank portfolios are successfully regulated. The literature on regulation of bank portfolios is one of profound subtlety, where the correct amount of capital that banks must hold is subject to intense debate (Aiyar, Calomiris and Wieladek 2015). The spotty record of regulators before the GFC also throws doubt on their ability to do better next time (Calomiris 2011, 2013). It is still debated as to whether the regulatory response to the GFC made things worse rather than better (Tarullo 2019).
- The consultation papers by the Reserve Bank and the Treasury are silent on the recent bank runs overseas and soundness of the intellectual framework behind the policy responses to them. The consultation documents also missed the biggest lesson from the policy response to those bank runs.
Implied bank deposit guarantees
- The big depositors in the Silicon Valley Bank won their bet. Despite a balance sheet at the Silicon Valley Bank and the other banks that went into receivership that showed tens of billions of dollars in unrealised losses on long-term securities, they could regard their bank balances of whatever amount as safe because there is an implied deposit guarantee by the Federal authorities. This will be forthcoming in a bank crisis especially if there is a high-profile bank run. The other US banks that have mismatched portfolios were equally successful in their betting about an implied deposit guarantee.
- This triggering of an implied deposit guarantee for all depositors is what happened in New Zealand at the height of the global financial crisis when a choice had to be made, and it may have been for the best. The Crown guaranteed all retail and wholesale bank deposits for two years in return for a 1% fee to calm market jitters. The government in 2008 also made the unfortunate decision, very much as an afterthought to guarantee deposits with finance companies.
Different models for different deposit takers
- Diamond and Dybvig (1983) was the relevant intellectual framework for banks and the calming of market jitters and the potential for bank panics in 2008. The Kareken and Wallace (1978) model of deposit insurance and moral hazard was the relevant framework for finance companies but was ignored in 2008 and has been ignored again with the Deposit Takers Act 2023.
- For the rollout of deposit insurance in New Zealand, the Diamond and Dybvig (1983) model is the relevant intellectual framework for preventing bank panics. An illiquid but solvent bank can avoid failure by borrowing from the lender of last resort facility. The lender of last resort facility, a deposit insurance payout and a bank recapitalisation are the likely responses to an insolvent bank.
- The Kareken and Wallace (1978) model of deposit insurance and moral hazard is the relevant intellectual model for insuring the non-bank deposit takers. The Treasury’s consultation paper does not draw out this intellectual framework for understanding the large risks that are to be taken on to the Crown portfolio from insuring the non-bank deposit takers as well as the banks.
Conclusions
- Crown deposit insurance is to be offered to a mixed bag. The AA and A credit ratings for the banks imply a remote probability of default. The credit ratings for the non-bank deposit takers often imply a default probability of one chance in 10 in the next five years. Too many of these non-bank deposit takers have what are in effect junk bond credit ratings. The consultation papers by the Treasury and from the Reserve Bank do not make this fiscal risk from deposit insurance clear.
- The target for the deposit insurance reserve fund should accept that most of the calls on its funds will be from the non-bank deposit takers. The consultation papers by the Treasury and Reserve Bank do not make this fiscal risk to taxpayers from deposit insurance clear.
- The Minister should consider adopting sub-targets for premiums collected from banks and for premiums collected from non-bank deposit takers to make transparent the level of coverage to each sector and when payouts on deposit insurance constitute a cross-subsidy. Cross-subsidies between different types of deposit takers should be kept to a minimum, and risk-based pricing for deposit insurance is an essential protection for taxpayers and the public purse.
- Indeed, we prefer that there should not be a target for the deposit insurance reserve fund. Such a target rules out risk-based deposit insurance premiums. Once the target is reached, no further premiums are charged so the deposit insurance is free which encourages risk-taking by deposit takers.
- There is every reason to believe that investors will move back into the non-bank deposit taking sector because deposit insurance will remove any need for concerns about the solvency of non-bank deposit takers as long as they keep their deposits with any one institution at no more than $100,000. Non-bank deposit takers will be encouraged to take more risks in their lending because their depositors will not penalise them by going elsewhere unless an additional risk premium is offered.
- The recent bank runs overseas illustrate how difficult it is for governments to not cave-in to public pressures about implied guarantees for all deposits with banks and for banks to be bailed-out despite taking excessive risks in their lending and in their securities portfolio management.
- None of the bank runs overseas are mentioned in the consultation documents. We don’t know whether the deposit insurance being rolled out for NZ and our prudential regulation are robust to the interest rate risk behind the recent bank runs overseas! There is no evidence that the Treasury or the Reserve Bank have paused to consider these recent major policy developments overseas.
Yours sincerely,
New Zealand Taxpayers’ Union Inc.
Jim Rose
Jim Rose
Research Fellow
Jim@taxpayers.org.nz
References
Aiyar, Shekhar & Charles W Calomiris & Tomasz Wieladek, 2015. “Bank Capital Regulation: Theory, Empirics, and Policy,” IMF Economic Review vol. 63 (4), pp. 955-983, November.
Allen, Franklin, Elena Carletti, Itay Goldstein and Agnese Leonello 2018. “Government guarantees and financial stability”. Journal of Economic Theory, Vol 177 pp. 518-557.
Anginer, Deniz and Demirgüç-Kunt, Asli and Zhu, Min, “How Does Deposit Insurance Affect Bank Risk? Evidence from the Recent Crisis”, Journal of Banking & Finance, 2014, vol. 48, issue C, 312-321.
Atmaca, S, K Kirschenmann, S Ongena and K Schoors (2020), “Deposit insurance, bank ownership and depositor behavior”, CEPR Discussion Paper 15547.
Auditor-General 2011. The Treasury: Implementing and managing the Crown Retail Deposit Guarantee Scheme. Office of the Auditor-General, Wellington.
Bollard, Alan and Sarah Gaitanos, Crisis: One Central Bank Governor & the Global Financial Collapse. Auckland University Press (2013).
Bordo, Michael D. “The Lender of Last Resort: Alternative Views and Historical Experience.” Economic Review (Federal Reserve Bank of Richmond), Vol. 76/1, pp. 18-29, (January/February 1990).
Bordo, Michael D. 2018. “An Historical Perspective on the Quest for Financial Stability and the Monetary Policy Regime,” The Journal of Economic History, vol 78(2), pp. 319-357.
Bordo, Michael D., and Angela Redish. “Why did the Bank of Canada Emerge in 1935?” Journal of Economic History, Vol. XLVII, No. 2, June 1987, pp. 405-417.
Bordo, Michael D., Angela Redish and Hugh Rockoff, 2015. “Why didn’t Canada have a banking crisis in 2008 (or in 1930, or 1907, or …)?,” The Economic History Review, vol 68 (1), pp. 218-243.
Bryant, John. 1980. “A Model of Reserves, Bank Runs, and Deposit Insurance. Journal of Banking & Finance 4(4), pp. 335–44.
Calomiris, Charles W., “Banking Crises,” In New Palgrave Dictionary of Economics, 2nd Edition, edited by Steven Durlauf and Lawrence Blume, 2009.
Calomiris, Charles W., “Banking crises yesterday and today,” Financial History Review, Cambridge University Press, vol. 17 (1), pp. 3-12, April 2010.
Calomiris, Charles W., “Banking Crises and the Rules of the Game,” In Monetary and Banking History: Essays in Honour of Forrest Capie, edited by Geoffrey Wood, Terence Mills, and Nicholas Crafts, Routledge, 2011, pp. 88-132.
Calomiris, Charles W., “Banking Fragility of the United States, 1790-2009”. In Handbook of Key Global Financial Markets, Institutions, and Infrastructure, edited by Gerard Caprio, Charles W. Calomiris, and Larry Neal. London: Elsevier Press, 2013.
Calomiris, Charles W. and Matthew Jaremski, 2016. “Deposit Insurance: Theories and Facts,” Annual Review of Financial Economics, vol. 8(1), pages 97-120, October.
Calomiris, Charles W. and Matthew Jaremski, “Stealing Deposits: Deposit Insurance, Risk-Taking, and the Removal of Market Discipline in Early 20-Century Banks.” The Journal of Finance 74, no. 2 (2019): 711–54.
Diamond, Douglas W., and Philip H. Dybvig. 1983. “Bank Runs, Deposit Insurance, and Liquidity.” Journal of Political Economy 91(3), pp. 401–19.
Feldman, R., “When should the FDIC act like a private insurance company?” Federal Reserve Bank of Minneapolis at https://www.minneapolisfed.org/article/1998/when-should-the-fdic-act-like-a-private-insurance-company
Gorton, Gary., and Andrew Winton. “Financial Intermediation”. In Constantinides, George, Milton Harris, and Rene Stulz (eds). The Handbook of the Economics of Finance Elsevier Science, 2003 pp 431-552.
Gropp, Reint., Christian Gruendl, and Andre Guettler. “The Impact of Public Guarantees on Bank Risk-Taking: Evidence from a Natural Experiment”. Review of Finance, Volume 18, Issue 2, April 2014, pp. 457–488.
Hane, George. “The Banking Crises of the 1980s and Early 1990s: Summary and Implications”. FDIC Banking Review, 1998 Vol. 11, No. 1, pp. 1-21.
Humphrey, Thomas H., and Robert E. Keleher, “The Lender of Last Resort; A Historical Perspective”, Cato Journal, 1984, vol. 4, issue 1, 275-321
Iyer R., Jensen, TL., Johannesen, N., and Sheridan, A. 2019. “The distortive effects of too-big-to-fail: evidence from the Danish market for retail deposits”, The Review of Financial Studies, Vol:32, pp. 4653-4695.
Jokivuolle, Esa & George Pennacchi, 2019. “Designing a Multinational Deposit Insurance System: Implications for the European Deposit Insurance Scheme,” ifo DICE Report, ifo Institute – Leibniz Institute for Economic Research at the University of Munich, vol. 17(01), pages 21-25, May.
Kareken, John H., and Neil Wallace. 1978. “Deposit Insurance and Bank Regulation: A Partial-Equilibrium Exposition.” Journal of Business 51 (July), pp. 413–38.
Lambert, C., F. Noth, and U. Schüwer (2014). “How do insured deposits affect bank risk? Evidence from the 2008 Emergency Economic Stabilization Act. Journal of Financial Intermediation 29 (October), pp. 81–102.
Martin, Christopher., Manju Puri and Alexander Ufier, 2018. “Deposit Inflows and Outflows in Failing Banks: The Role of Deposit Insurance,” NBER Working Papers 24589, National Bureau of Economic Research.
O’Sullivan, Fran. “Vital witness missing at SCF trial”. New Zealand Herald, 15 October 2014.
Pennacchi, George G. “A Reexamination of the Over- (or Under-) Pricing of Deposit Insurance.” Journal of Money, Credit and Banking 19, no. 3 (1987): 340–60.
Pennacchi, George G. “Deposit insurance, bank regulation, and financial system risks”, Journal of Monetary Economics, 2006, vol. 53, issue 1, 1-30.
Pennacchi, George G (2010), “Deposit Insurance Reform” in J Brown (ed.), Public Insurance and Private Markets, AEI Press.
Pennacchi, George G. (2000), “The Effects of Setting Deposit Insurance Premiums to Target Insurance Fund Reserves”, Journal of Financial Services Research 17, 153-180.
Rolick, A., 2010. “Interview with Thomas Sargent”. The Region, Federal Bank of Minneapolis, vol. 24, issue Sep, pp. 26-39.
Tarullo, Daniel K. “Financial Regulation: Still Unsettled a Decade After the Crisis.” The Journal of Economic Perspectives 33, no. 1 (2019): 61–80.
Wheelock, David C. “Regulation and Bank Failures: New Evidence from the Agricultural Collapse of the 1920s.” The Journal of Economic History 52, no. 4 (1992): 806–25.
Wheelock, David C., and Subal C. Kumbhakar. “Which Banks Choose Deposit Insurance? Evidence of Adverse Selection and Moral Hazard in a Voluntary Insurance System.” Journal of Money, Credit and Banking 27, no. 1 (1995): 186–201.
Wheelock, David C. & Paul W. Wilson, 1994. “Can deposit insurance increase the risk of bank failure? Some historical evidence,” Review, Federal Reserve Bank of St. Louis, May, pages 57-71.
Wheelock, David C., and Paul W. Wilson. “Explaining Bank Failures: Deposit Insurance, Regulation, and Efficiency.” The Review of Economics and Statistics 77, no. 4 (1995): 689–700.
Appendix
Table A1 Standardised credit rating agency rating scale
| Description | S&P Scale | Moody’s Scale | Fitch Scale | Approx probability of default over 5 years* | |
| Capacity to make timely payment | Extremely strong | AAA | Aaa | AAA | 1 in 600 |
| Capacity to make timely payment | Very strong | AA | Aa | AA | 1 in 300 |
| Capacity to make timely payment | Strong | A | A | A | 1 in 150 |
| Capacity to make timely payment | Adequate | BBB | Baa | BBB | 1 in 30 |
| Vulnerability to non-payment | Less vulnerable | BB | Ba | BB | 1 in 10 |
| Vulnerability to non-payment | More vulnerable | B | B | B | 1 in 5 |
| Vulnerability to non-payment | Currently vulnerable | CCC | Caa | CCC | 1 in 2 |
| Vulnerability to non-payment | Currently highly vulnerable | CC | CC | ||
| Vulnerability to non-payment | Default | D | C | D |
Source: Reserve Bank at https://www.rbnz.govt.nz/regulation-and-supervision/oversight-of-banks/standards-and-requirements-for-banks/bank-credit-ratings
* The approximate, median likelihood that an investor will not receive repayment on a five-year investment on time and in full based upon historical default rates published by each agency
Table A2: Banks currently registered in New Zealand
Source: Reserve Bank at https://www.rbnz.govt.nz/regulation-and-supervision/cross-sector-oversight/registers-of-entities-we-regulate/registered-banks-in-new-zealand
Note: Banks marked (B) operate in New Zealand as branches of overseas-incorporated banks. All other banks are incorporated in New Zealand.
So sad for the woman
04 Oct 2026 Leave a comment
in discrimination, economics of crime, gender, law and economics, politics - New Zealand Tags: crime and punishment, criminal deterrence, law and order
The Herald reports: A protection order was supposed to keep a woman safe. Instead, a judge said it proved “no better than a piece of soiled toilet paper” as her partner hunted her down, beat her, threatened her life and raped her during a sustained attack that left her fearing she would die. Now the…
So sad for the woman
Bill Maher on accidental bipartisanship
04 Oct 2026 Leave a comment
in politics - USA, television, TV shows
This week Bill Maher’s comedy/news bit on “Real Time” mourns the lack of bipartisanship in American politics—something that was once admired but now is denigrated. His two examples of how both parties contributed to improving society involve drugs—the dramatic decrease of death from street drugs like fentanyl as well as the price drops in widely-used…
Bill Maher on accidental bipartisanship
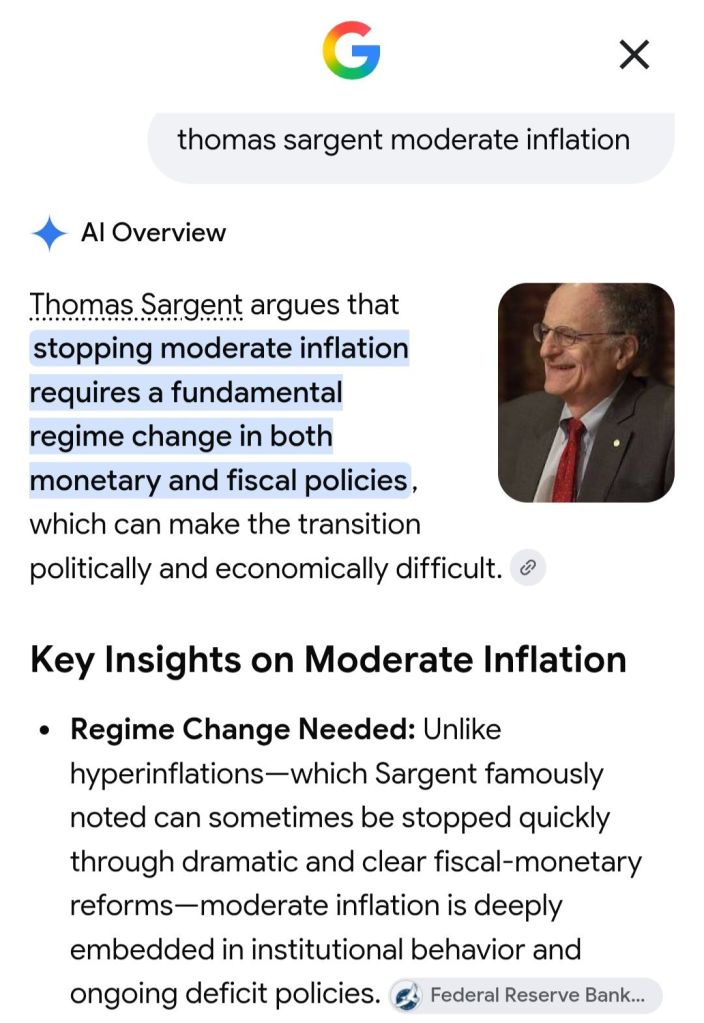
Sargent on moderate inflations
04 Oct 2026 Leave a comment
in budget deficits, business cycles, economic history, fiscal policy, history of economic thought, labour economics, labour supply, macroeconomics, monetarism, monetary economics, unemployment Tags: monetary policy
YIMBY = IGMSY
04 Oct 2026 Leave a comment
in applied price theory, economics of regulation, politics - USA, urban economics Tags: housing affordability, land supply, zoning
“I’ve got mine; screw you!” is the rallying cry of those who seek to increase the density of urban areas by building multi-story apartment buildings. Actually, the rallying cry is “Yes in my backyard,” but most prominent YIMBYs live in single-family homes and I haven’t heard of a single one … Continue reading →
YIMBY = IGMSY
New issue of Econ Journal Watch
03 Oct 2026 Leave a comment
in applied price theory, econometerics, economic history, economics of regulation, financial economics, history of economic thought
Volume 23, Issue 2, September 2026 In this issue: “China shock” fragility: According to David Autor, David Dorn, and Gordon Hanson (2013), the “China shock” hit the United States from 1990 to 2007. When corrections by Kirill Borusyak et al. (2022) are fully applied, Joseph Francis argues, the harm of Chinese imports to unemployment, labor force…
New issue of Econ Journal Watch
Urban elite obsession with supermarkets
03 Oct 2026 Leave a comment
in economics of bureaucracy, economics of regulation, entrepreneurship, income redistribution, industrial organisation, politics - New Zealand, Public Choice, rentseeking Tags: 2026 general election
Anyone who drives to Gisborne, as I have done from the north and south, will discover the roads are winding and often tedious. This means getting in produce such as groceries, incurs significant costs because of the distance and small population served. Particularly challenging for perishable meat, dairy, fruit and vegetables. The National Party’s policy […]
Urban elite obsession with supermarkets
The Taxpayers’ Union manifesto
03 Oct 2026 Leave a comment
in politics - New Zealand Tags: 2026 general election
The Taxpayers’ Union has published their 2026 manifesto. Some extracts: The post The Taxpayers’ Union manifesto first appeared on Kiwiblog.
The Taxpayers’ Union manifesto
Why George Orwell was a great writer
03 Oct 2026 Leave a comment
in defence economics, economics of education, liberalism, Marxist economics, war and peace
George Orwell is widely regarded as a great writer because he combined unusual clarity of prose with intellectual seriousness, moral urgency and a remarkable ability to turn political ideas into memorable literature. His style is one of the main reasons. Orwell worked hard to make difficult ideas seem simple without making them simplistic. His prose is […]
Why George Orwell was a great writer
Rainbow requirements and Treaty obligations: the HR issues that impede productivity but enhance diversity
03 Oct 2026 Leave a comment
in discrimination, economics of regulation, gender, human capital, labour economics, labour supply, law and economics, poverty and inequality, property rights Tags: employment law
Bob Edlin writes – PoO noted a Newsroom report headed Major export and construction firms warn against legal definition of women. The report draws attention to objections raised to the Legislation (Definitions of Woman and Man) Amendment Bill, which aims to amend the Legislation Act to define “woman” as “an adult human biological female” and […]
Rainbow requirements and Treaty obligations: the HR issues that impede productivity but enhance diversity
America’s Affordability Problem Is Government
02 Oct 2026 Leave a comment
in economic growth, economic history, entrepreneurship, financial economics, history of economic thought, human capital, labour economics, labour supply, macroeconomics, poverty and inequality Tags: The Great Enrichment, top 1%

I have a series of columns (2021, 2024, 2025, and 2026). documenting that Americans are getting richer. And here’s a chart that adds additional evidence. More and more households over time are high income (over $100k) and fewer and fewer are low income (under $35k). And, yes, these numbers are adjusted for inflation. The chart was […]
America’s Affordability Problem Is Government


Recent Comments