Entrepreneurship and the Market Process with Israel Kirzner
18 Apr 2014 Leave a comment
in applied welfare economics, Austrian economics, entrepreneurship, industrial organisation, market efficiency
Tom Sargent’s 12 lessons from economics for public policy
17 Apr 2014 Leave a comment
in applied welfare economics, entrepreneurship, industrial organisation, macroeconomics, market efficiency, politics, Public Choice Tags: Thomas Sargent, time inconsistency, trade-offs
Tom Sargent is a life-long Democrat who is old enough to remember when Democrats were fiscal conservatives.
At a graduation speech at Berkeley, Sargent listed these lessons:
-
Many things that are desirable are not feasible.
-
Individuals and communities face trade-offs.
-
Other people have more information about their abilities, their efforts, and their preferences than you do.
-
Everyone responds to incentives, including people you want to help. That is why social safety nets don’t always end up working as intended.
-
There are trade-offs between equality and efficiency.
-
In an equilibrium of a game or an economy, people are satisfied with their choices. That is why it is difficult for well-meaning outsiders to change things for better or worse.
-
In the future, you too will respond to incentives. That is why there are some promises that you’d like to make but can’t. No one will believe those promises because they know that later it will not be in your interest to deliver. The lesson here is this: before you make a promise, think about whether you will want to keep it if and when your circumstances change. This is how you earn a reputation.
-
Governments and voters respond to incentives too. That is why governments sometimes default on loans and other promises that they have made.
-
It is feasible for one generation to shift costs to subsequent ones. That is what national government debts and the U.S. social security system do (but not the social security system of Singapore).
-
When a government spends, its citizens eventually pay, either today or tomorrow, either through explicit taxes or implicit ones like inflation.
-
Most people want other people to pay for public goods and government transfers (especially transfers to themselves).
- Because market prices aggregate traders’ information, it is difficult to forecast stock prices and interest rates and exchange rates
Experts Are at a Loss on Investing
15 Apr 2014 Leave a comment
in entrepreneurship, liberalism, market efficiency Tags: Harry M. Markowitz, modern portfolio theory
Harry M. Markowitz won the Nobel Prize in economics as the father of “modern portfolio theory,” the idea that people shouldn’t put all of their eggs in one basket, but should diversify their investments.

Markowitz split most of his his own retirement investments down the middle, put half in a stock fund and the other half in a conservative, low-interest investment.
Markowitz invested more wisely than some fellow Nobelists who have significant portions of their nest eggs in money market accounts, some of the lowest-returning investment vehicles available.
The rationality postulate is under attack from the other people are stupid fallacy-updated
14 Apr 2014 Leave a comment
in applied price theory, behavioural economics, economics of crime, entrepreneurship, experimental economics, industrial organisation, market efficiency, survivor principle Tags: behavioural economics, crime and punishment, criminal deterrence, experimental economics, Gordon Tullock, token economies, Vernon Smith
The rationality postulate is under attack from the other people are stupid fallacy: not you, not me, not present company, of course, but the nameless them over there; the perpetually baffled, every man jack of them.
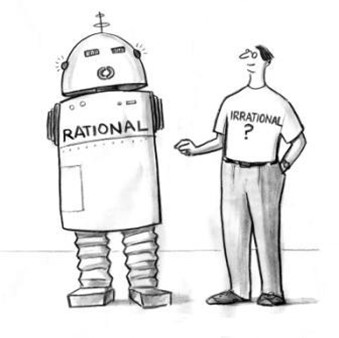
These no-hopers are deemed competent to vote and DRIVE CARS, but they cannot get their head around a credit card. How the them over there find their way to work every morning must be a mystery to behavioural economists. One summary of behavioural labour economics is this:
The key empirical findings from field research in behavioural economics imply that individuals can make systematic errors or be put off by complexity, that they procrastinate, and that they hold non-standard preferences and non-standard beliefs
I found the chapter in Tullock and McKenzie’s book on token economies in mental hospitals to be most enlightening.
The tokens were for spending money at the hospital canteen and trips to town and other privileges. They were earned by keeping you and your area clean and helping out with chores.
The first token economies were for chronic, treatment-resistant psychotic inpatients.
In 1977, a major study, still considered a landmark, successfully showed the superiority of a token economy compared to the standard treatments. Despite this success, token economies disappeared from the 1980s on.
Experiments which would now be unethical showed that the occupational choices and labour supply of certified lunatics responded to incentives in the normal, predictable way.
For example, tokens were withdrawn for helping clean halls and common areas. The changes in occupational choice and reductions in labour supply was immediate and as predicted by standard economics.
Some patients would steal the tokens for other patients, so the token individually marked, and the thefts almost stopped. Crime must pay even for criminally insane inpatients.
Kagel reported that:
The results have not varied with any identifiable trait or characteristic of the subjects of the token economy – age, IQ, educational level, length of hospitalization, or type of diagnosis.

Behavioural economics is an excellent example of how engaging in John S. Mill’s truth that engaging with people who are partly or totally wrong sharpens your arguments, improves their presentation and deepens your analysis.
People have a better understanding of rationality such as through the work of Vernon Smith on ecological and constructivist rationality and of how people deal with human frailties and correct error through specialisation, exchange and learning.
- George Stigler in his Existence of X-inefficiency paper opposed attributing behaviour to errors because error can explain everything so it explains nothing until we have a theory of error.
- Kirzner in “X–Inefficiency, Error and the Scope for Entrepreneurship” wrote that error is pervasive in economic processes. Rational Misesian human actors are human enough to err.
What is inefficient about the world, said Kirzner, is at each instant, an opportunity for improvements, in one way or another and is yet simply not yet noticed. The lure of pure entrepreneurial profits harnesses the systematic elimination of errors and points the way to the market generated institutions necessary for steady social improvements to emerge. Brand names are an obvious example of an institution to overcome doubts about product quality. Middle-men and brokers specialise in performing much of the calculation burdens in their markets.
Many still compare real-world marketplaces to idealised regulation overseen by bureaucrats free of the very biases they are nudging us along to overcome. There are real constraints that limit the options available to fix what are seen as problems to be solved.
Vernon Smith when asked about behavioural economics, wondered how so cognitively flawed a creature made it out of the caves. Vernon Smith argued that the answer had a lot to do with the institutions that emerged to overcome human limitations:
Markets are about recognizing that information is dispersed in all social systems and that the problem of society is to find, devise, and discover institutions that incentivize and enable people to make the right decisions without anyone having to tell them what to do.
Smith and Hayek both posit that market institutions rather than individuals bear the primary cognitive burden in coordinating economic activity. To quote Vernon Smith:
What we learn from experiments is that any group of people can walk into a room, be incentivized with a well-defined private economic environment, have the rules of the oral double auction explained to them for the first time, and they can make a market that usually converges to a competitive equilibrium, and is 100 per cent efficient—they maximize the gains from exchange—within two or three repetitions of a trading period.
Yet knowledge is dispersed, with no participant informed of market supply and demand, or even understanding what that means.
This strikingly demonstrates what Adam Smith called ”a certain propensity in human nature . . . to truck, barter, and exchange one thing for another”
These double oral auctions converged to the competitive price even with as few as three or four sellers with neither the buyers nor sellers knowing anything of the values or costs of others in the market. Price-taking behaviour was not necessary to reach these competitive outcomes.
Behavioural economics is a clumsy way of discussing the pervasiveness of errors because insufficient attention is paid to decentralised, emergent market processes that correct them, often long ago.
What Have We Learned from the Collapse of Communism? by Peter Boettke
13 Apr 2014 Leave a comment
in Austrian economics, constitutional political economy, development economics, entrepreneurship, law and economics, liberalism, Public Choice Tags: collapse of communism
the collapse of Communism has taught political economists several things:
first, that economic policy is always nested within a set of institutions—that there are economic/financial, political/legal, and social/cultural issues, which all must be taken into account;
second, that leadership matters throughout the transition process;
and third, that historical contingency can either work in your favour or cut against the successful transition.
And I would add a fourth one: that political power corrupts even the most informed and idealistic of individuals, such that you cannot count on ideological alignment to win the day. You have instead a small window of opportunity in which ideological alignment can be utilized to establish institutions that make it difficult for even bad men to do much harm.
In other words, the goal of our political/legal institutions should not be to ensure that the best and the brightest can govern, but instead that if the worst get in power, they can do little damage. This is the idea of a “robust political economy”.
Steve Jobs and the Twitter Left
11 Apr 2014 Leave a comment
in entrepreneurship, personnel economics, politics Tags: Steve Jobs
We saw the movie Jobs:
- I could not work out what Steve Jobs actually achieved on his own by the time the film ended in about 2001.
- Jobs was portrayed as a thoroughly unlikable fellow who was a terrible CEO who deserved to be fired in the mid-1980s.
- If he had been hit by a bus in 2000, no one would remember him now. I read a biography of Jobs around that time.
By 2012, Jobs had been labelled “Greatest entrepreneur of our time”, “brilliant, visionary, inspiring”, and “the quintessential entrepreneur of our generation” and CEO of the decade.
My estimations of Jobs did go up later when I found out that after resuming control of Apple in 1997, Jobs eliminated all corporate philanthropy programmes. Jobs said he felt that expanding Apple would do more good than giving money to charity. This is a great point by him about the role of economic progress in abolishing poverty. There is no public record of Jobs giving money to charity apart from product RED.

Good to see that having a driven personality can still get you a pass on your membership of the top 0.1% of income earners in the eyes of the Twitter Left or should it be the IPhone Left.
The Girl Scouts, entrepreneurial alertness and the theory of the firm
11 Apr 2014 Leave a comment
in entrepreneurship, theory of the firm Tags: Girl scouts

Girl Scouts (the firm) allow entrepreneurship from within. This girl was alert enough to camp outside of a marijuana dispensary.
The World Bank Ignores How Capitalism Can Help Us to Adapt to Climate Change!
05 Apr 2014 1 Comment
in development economics, economics of natural disasters, entrepreneurship, environmentalism Tags: adaptation, global warming

Matt Kahn at Environmental and Urban Economics.
Profit maximisation gets no respect
30 Mar 2014 2 Comments
in entrepreneurship, George Stigler, industrial organisation, survivor principle Tags: Armen Alchian, market selection, profit-maximisation, the market as an evolutionary process
Who would own up to personal greed and selfishness? But who sends a tip in with their taxes?

George Stigler said that if you ask business owners if they maximise profits, they say no, no, no. They are just there to provide employment, a service for their customers, and then they put a small amount aside for the education of their children.
Stigler then said that if you asked them if they lowered their prices, would they increase their profits, the answer is invariably no.
Stigler then said that if you asked them if they raised their prices, would they increase their profits, the answer is invariably no.
Stigler then said that if you asked them if they have in the last 12-months substituted some other objective for profit, they throw you out of their office.
What people do is far more important than what they say and what they say motivated them.
Alchian pointed out the evolutionary struggle for survival in the face of market competition ensured that only the profit maximising firms survived:
- Realised profits, not maximum profits, are the marks of success and viability in any market. It does not matter through what process of reasoning or motivation that business success is achieved.
- Realised profit is the criterion by which the market process selects survivors.
- Positive profits accrue to those who are better than their competitors, even if the participants are ignorant, intelligent, skilful, etc. These lesser rivals will exhaust their retained earnings and fail to attract further investor support.
- As in a race, the prize goes to the relatively fastest ‘even if all the competitors loaf.’
- The firms which quickly imitate more successful firms increase their chances of survival. The firms that fail to adapt, or do so slowly, risk a greater likelihood of failure.
- The relatively fastest in this evolutionary process of learning, adaptation and imitation will, in fact, be the profit maximisers and market selection will lead to the survival only of these profit maximising firms.
These surviving firms may not know why they are successful, but they have survived and will keep surviving until overtaken by a better rival. All business needs to know is a practice is successful. The reason for its success is less important.
Great store is placed in industry economics on how firms in direct competition in the same market producing even rather standard products such as cement can have far greater measured productivity than others. Some firms produce half as much output from the same measured inputs as their market rivals and still survive in competition (Syverson 2011).
As is too common, the conclusion is there is something wrong with the firms in these markets rather than with the analysis that fails to understand these puzzlingly large gaps in measured productivity.
Few ask the obvious question, which is how do these firms survive if they are so inferior to the market leaders. The important fact is they do survive. They must be doing something right for their customers that the productivity statistics miss.
One method of organising production and supplying to the market will supplant another when it can supply at a lower price (Marshall 1920, Stigler 1958). Gary Becker (1962) argued that firms cannot survive for long in the market with inferior product and production methods regardless of what their motives are. They will not cover their costs.
The more efficient sized firms are the firm sizes that are currently expanding their market shares in the face of competition; the less efficient sized firms are those that are currently losing market share (Stigler 1958; Alchian 1950; Demsetz 1973, 1976). Business vitality and capacity for growth and innovation are only weakly related to cost conditions and often depends on many factors that are subtle and difficult to observe (Stigler 1958, 1987).
An example is in Adam Smith’s study of religion. One thing he noticed was that religious sects with strict codes of honesty and intense mutual monitoring by co-congregants for the slightest moral lapses proliferated in cities. Many successful businessmen belonged to these strict religions. These highly religious businessmen were successful in their businesses because they were looked upon by the public as reliable trading partners in a time of weak law enforcement. These businessmen did not know that this was profit maximising but the businessmen with religious backgrounds slowly gained market share over rival firms that had less efficient ways of communicating both their reliability and that their personal honesty was under daily scrutiny.
Ethnic minorities are advantaged in the same way in business. Because of their extensive social interactions with each other because of their language or religious practices and inter-marriage, the costs of bad business behaviours are much higher due to the risk of social ostracism by everyone you know. This greater trustworthiness gives them a cost advantage in the marketplace even though they may be unaware of its source.
Privatisation screw-ups are the best case for privatisation
26 Mar 2014 2 Comments
in entrepreneurship, politics - New Zealand, privatisation, Public Choice Tags: government as business owners, government asset sales, government privatisations
Governments are so bad as business owners and so incapable of running a commercial process free of politics that governments cannot even sell a state-owned enterprise for a good price under the full glare of the media and public.
Anyone can sell an asset. It is the simplest task of ownership. Hire some consultants and go for the best price. Governments lack this ability.
Privatisations are often politicised, with discounts for small buyers from the middle class, for employees and other special interests. These messy privatisations are the best case out there against state ownership of businesses.
“No asset sales” was the Labour Party’s most coherent slogan in the 2011 general election in New Zealand. It cannot be claimed that the more recent privatisations in New Zealand were not subject to the maximum amount of public and parliamentary scrutiny possible in a democracy. The 2011 election was said to be a referendum on asset sales.
This inability to sell state-owned enterprises for a profit and free of politics calls into question the ability of governments to make complicated day-to-day business management and entrepreneurial judgements as owners of business enterprises. Imagine the quality of the day-to-day state-owned enterprise decision making that is further away from the glare of an election?
Private asset owners have a strong incentive to sell assets at a profit as it will otherwise hurt their share price and their personal wealth. Inferior entrepreneurs and owners are punished by losses. Any assets that inferior entrepreneurs either mismanaged or sell at a bargain price will, through further buying and selling, end up in the hands of more alert entrepreneurs and owners.
There are no similar feedback and error correction measures disciplining governments as asset owners and in their day-to-day monitoring of their business portfolios. Governments who own business assets have an inherently softer budget constraint.
Warren Buffett and other business owners
17 Mar 2014 Leave a comment
in entrepreneurship, market efficiency Tags: efficient markets hypothesis, Eugene Fama, Kerry Packer, luck versus skill, Rupert Murdoch, Warren Buffett
The father of the efficient markets hypothesis and a champion of the passive investment index-linked funds Eugene Fama considers Buffett to be more of a businessman than a portfolio investor. To Fama, the high returns by Buffett look great because entrepreneurs that do survive in market competition look good because we ignore the thousands that failed and lost everything.

You should compare Buffett with other businessmen such as Kerry Packer and Rupert Murdoch. These two Australian corporate giants started off with two TV stations and a rather ordinary afternoon newspaper, respectively.
Packer and Murdoch grew their businesses to a global level to move from being millionaires to billionaires. Bill Gates and Steve Jobs also built and ran big companies from scratch.
Packer, Murdoch, Gates and Jobs all had great returns because they were able to obtain a return of their unique management skills and entrepreneurial alertness.
Kaplan and Rauh in “It’s the Market: The Broad-Based Rise in the Return to Top Talent” Journal of Economic Perspectives 2013 found that most of those in the Forbes 400 did not grow up wealthy.
Most of the Forbes 400 are entrepreneurs who accessed education while young and then applied their skills to the technology, finance, and mass retail sectors. In these sectors, through ICT and other innovations, these entrepreneurs could apply their superior talents to larger and larger pools of resources and more and more firms to reach huge numbers of consumers on a national or global scale. They became superstars in terms of their productivity and pay because they could lever their talents so widely over so many firms, workers, consumers and countries.
But remember, hundreds of dot.com firms failed and lost everything for each one that made it big. These are businesses we remember. The dot.com firms that failed are quiz questions, if they are remembered at all.
What is left standing after all this blood letting must be extremely profitable if only to justify the ride for those that risked it all to have it all. Fama estimated that the dot.com bubble was justified if something like 1.4 more Microsofts were born as a result of it!
Frazzini, Kabiller and Pedersen in “Buffett’s Alpha” found that Buffet had “a higher Sharpe ratio than any stock or mutual fund with a history of more than 30 years”. The Sharpe Ratio describes how much excess return you are receiving for the extra volatility in your portfolio because your are holding a riskier asset
Buffett is a volatile investment as Frazzini, Kabiller and Pedersen noted: from July 1998 through February 2000, Berkshire lost 44% of its market value, while the overall share market gained 32%.
A key to Buffett’s success was Berkshire surviving these set-backs.
Both Packer and Murdoch too had a few lucky scraps with their bankers. Steven Jobs was fired by Apple in 1985 because he was no good as a CEO – he was sending the company broke and would not listen. Bill Gates is as good as his next product launch. Nokia shares initially fell by 90% in 2007 when Apple leap-frogged it with a phone that resembled a PC – the iPhone.
Buffett and Murdoch both run an internal capital market where they expect a certain minimum rate of return.
Both are hands-off. Buffett’s corporate head office has 24 employees to do the regulatory and compliance work.
Murdoch reputedly rings the chief executive of each of his companies once a month for one minute. If what the chief executive says is interesting, the call gets longer. This is the essence of entrepreneurial alertness. Noticing what others have not and grasping that opportunity before someone else beats you to it.
The economics of Dennis Lillee and Steve Jobs
15 Mar 2014 1 Comment
in cricket, entrepreneurship, human capital, labour economics Tags: Apple, Bill Gates, CEO pay, cricket, Dennis Lillee, Kerry Packer, regulatory capture, Steve Jobs, superstars, top 1%
Dennis Lillee was paid £1,200 to tour England in 1972 for five months. He was paid the same to tour for three months in 1975. Now a world-class fast bowling coach, he would probably not get out for bed for £1,200
When Kerry Packer bid for the Australian cricket rights in the 1970s, he offered $500,000 per year. That was about ten times what the ABC was paying at the time
The Australian cricket TV rights sold for over $500 million in 2013 for a 5-year deal.
Today’s international cricketers are millionaires – widely respected and beloved members of the top 1% of income earners. Most think it is great that top sports people make millions over their career. No plans for the Occupy Wall Street crowd to occupy the MCG, Wimbledon or the Olympics to complain about superstar sports salaries and prizes.
Lillee and other top athletes, celebrities, actors, musicians and entertainers are all paid much more for much the same reason that CEOs, money market managers, top lawyers and tech entrepreneurs are paid much more than in the past.
They are superstars who are able to leverage their talent through communications technology advances on a national and global level. They can apply ‘their talent to greater pools of resources and reach[ing] larger numbers of people thus becoming more productive and higher paid’.
- Why is there envy over the pay of businessmen but not for superstar entertainers and athletes?
- Did people boo World Series Cricket in 1977 because those cricketers could now make a decent living?
- Do people complain when musicians and actors make it big?
Why is Steve Jobs strangely immune from top 1% envy despite his cheapness and meanness to others while Bill Gates is reviled as some sort of monopolist despite his giving most of his wealth away?
Was Jobs worth his pay? Apple shares went up and down in billions on news of Steve Jobs’s health.
When Hewlett Packard’s CEO Mark Hurd resigned unexpectedly, the value of HP shares dropped by about $10 billion! This makes his $30 million in annual compensation a bargain for his shareholders. Oracle’s shares rose 6% on word of Mr. Hurd’s hiring as co-president on an annual base salary of $950,000 and being eligible for up to a $10 million annual bonus. Perhaps he is under-paid?
See Kaplan, Steven N., and Joshua Rauh. 2013. It’s the Market: The Broad-Based Rise in the Return to Top Talent, Journal of Economic Perspectives 2013 for more.
If you are so smart, why aren’t you rich? MITI version
14 Mar 2014 4 Comments
in entrepreneurship, human capital, Public Choice, Wall Street Tags: Deirdre McCloskey, efficient markets, MITI, picking winners, Wall Street, Wolf of Wall Street
If you are so smart, why aren’t you rich? This is the American question – asked of MIT’s Paul Cootner by a money market manager in the 1960s.
Why do investment advisors sell and often give away their sage advice? If their insights were any good, they could trade on the share market before others caught on and make a killing!
Deirdre McCloskey wrote a book about the limits of economic expertise. For a summary, see http://www.deirdremccloskey.com/docs/pdf/Article_168.pdf.

I will give a personal example based on the skills of bureaucracies in picking winners. The test of my hypothesis is based on the transferability of human capital across jobs.
My graduate school professors in Japan included many retired bureaucrats from the Ministry of Finance and MITI. These agencies were heralded by Joe Stiglitz and others for picking winners and guiding Japanese companies to choose the right technologies and what to export.
The skills that my graduate school professors learned at picking winners over their careers with the Ministry of Finance and MITI in the high-growth years in the 1970s would now be available to them in their retirements to trade on their own account.
My graduate school professors should quickly become very rich after retiring because of the skills they learned in picking winners while at the Ministry of Finance and MITI, which should cross over into their private share portfolios. The rich lists world-wide should be full of retired industry and finance ministry bureaucrats.
Instead, my graduate school professors took the train and bus to work and their families lived off their salaries in standard sized Japanese government apartments. All looked forward to their annual bonus of 5.15 months salary.
If governments are any good at picking winners, people should be willing to pay big time to get jobs at ministries of finance and ministries of international trade and industry to get access to their unique and highly secret skills they learn therein on how to pick winners. I am still waiting for that tell-all book by an insider on these skills. Why is there no Picking Winners for Dummies on Amazon kindle as yet?
P.S. McCloskey argued that the advising industry lives off 19th century case law on directors’ and trustees’ duties. If you take advice – from an accountant, a lawyer or an economist – and the business or investment still fails, it can’t be your fault. You took advice.
P.P.S. Cootner’s reply was “If you’re so rich, why aren’t you smart?” The answer to this was Wall Street investment brokers didn’t have to be smart to get rich; they can make money off fees and brokerage commissions even when their investment advice stank. Didn’t you watch The Wolf of Wall Street?
 Utopia, you are standing in it!

Recent Comments