The essence of macroeconomic forecasting by consultants
24 May 2015 Leave a comment
in applied price theory, business cycles, econometerics, economic growth, economic history, economics of media and culture, macroeconomics Tags: consultants, efficient markets hypothesis, forecasting errors
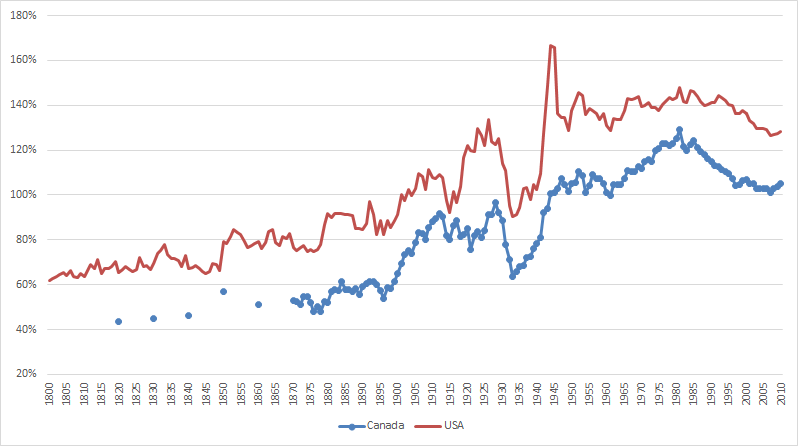
US and Canadian real GDP per capita as a percentage of British GDP per capita, 1800–2010
19 May 2015 Leave a comment
in economic growth, economic history, macroeconomics, politics - USA Tags: British economy, Canada, convergence
Figure 1: US and Canadian real GDP per capita are as percentage of British GDP per capita (1990 Int. GK$PPP), 1800 – 2010
Source: The Maddison-Project, http://www.ggdc.net/maddison/maddison-project/home.htm 2013 version.
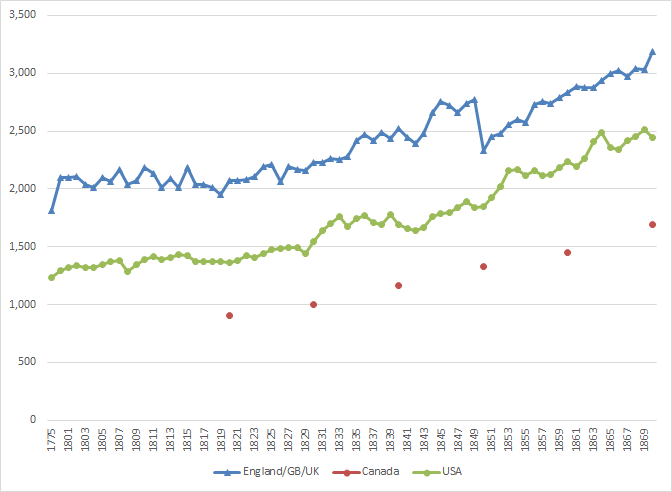
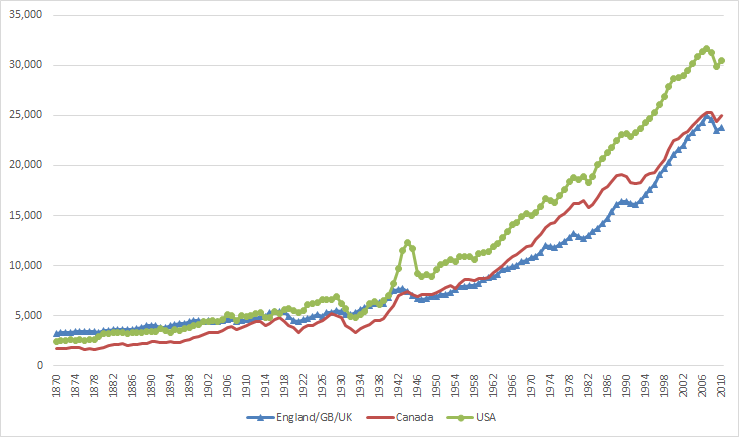
Colonial upstarts! British, American and Canadian real GDP per capita, 1775–2010
18 May 2015 Leave a comment
in economic growth, economic history, macroeconomics Tags: British economy, Canada, convergence, industrial revolution
The USA only overtook Britain in per capita GDP per capita in purchasing power parity terms early in the 20th century. Canada overtook the mother country in the post-war period.
Figure 1: British, American and Canadian GDP per capita (1990 Int. GK$PPP), 1775 – 2010

Source: The Maddison-Project, http://www.ggdc.net/maddison/maddison-project/home.htm 2013 version.
Figure 2: British, American and Canadian GDP per capita (1990 Int. GK$PPP), 1775 – 1870
Source: The Maddison-Project, http://www.ggdc.net/maddison/maddison-project/home.htm 2013 version.
Figure 3: British, American and Canadian GDP per capita (1990 Int. GK$PPP), 1870 – 2010
Source: The Maddison-Project, http://www.ggdc.net/maddison/maddison-project/home.htm 2013 version.
When did Down Under overtake the Mother Country? Real GDP Britain, Australia and New Zealand 1820–2010
17 May 2015 Leave a comment
in development economics, economic growth, economic history, growth disasters, growth miracles, macroeconomics Tags: Australia, British economy, convergence, lost decades, Maddison database, New Zealand
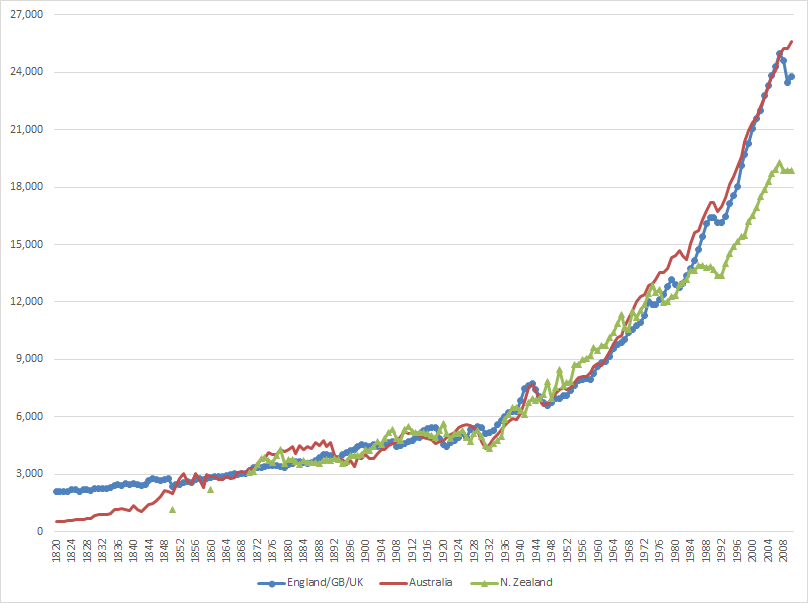
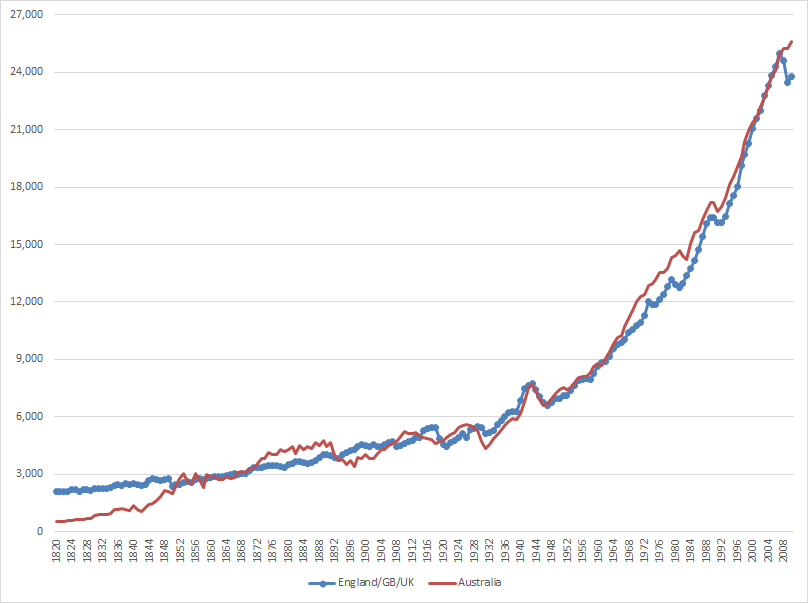
Pretty quickly according to figure 1. Britain, Australia and New Zealand quickly had similar standards of living in the middle of the 19th century until about 1880. Australia was richer for about 20 years until the great Federation drought took the wind out of its sails.
Figure 1: British, Australian and New Zealand GDP per capita (1990 Int. GK$PPP), 1820 – 2010
Source: The Maddison-Project, http://www.ggdc.net/maddison/maddison-project/home.htm 2013 version.
New Zealand then broke away at the end of the Second World War from both Australia and UK. In the mid-1960s circumstances changed with Australia drifting ahead of the UK and New Zealand drifting away to a lower standard of living.
Figure 2: British and Australian GDP per capita (1990 Int. GK$PPP), 1820 – 2010
Source: The Maddison-Project, http://www.ggdc.net/maddison/maddison-project/home.htm 2013 version.
Figure 2 shows that from about 1960 until 1990 Australia was richer than the UK. After that, the growth dividend of Thatchernomics allowed the British to catch up again to the Australians.
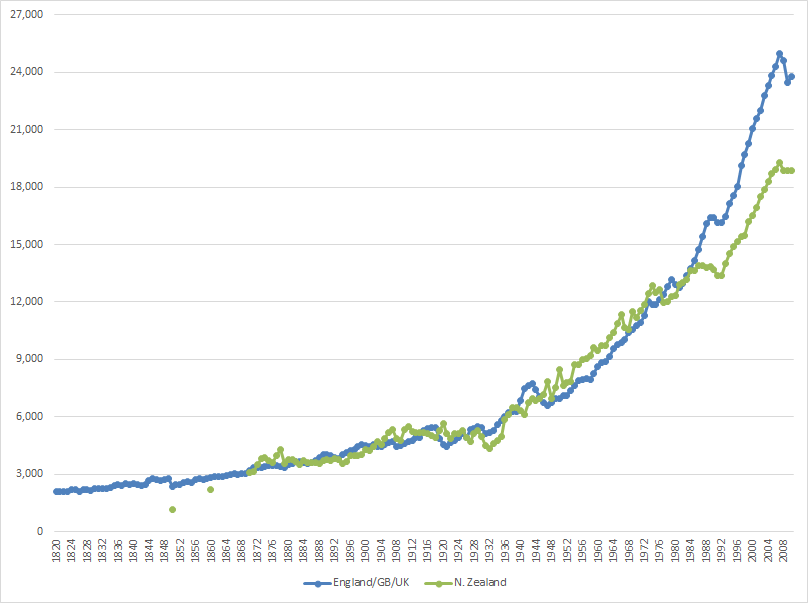
Figure 3: British and New Zealand GDP per capita (1990 Int. GK$PPP), 1820 – 2010
Source: The Maddison-Project, http://www.ggdc.net/maddison/maddison-project/home.htm 2013 version.
Figure 3 shows that New Zealand was richer than the UK in the mid-20th century. The lost decades in New Zealand from 1974 to 1992 let the sick man of Europe overtake New Zealand before Thatchernomics caused a growth spurt in the UK to take the British well ahead.
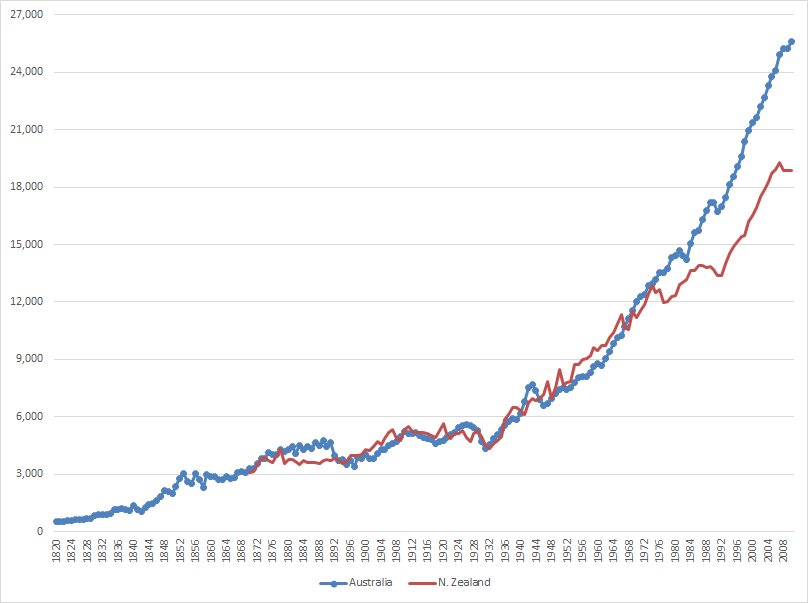
Figure 4: Australian and New Zealand GDP per capita (1990 Int. GK$PPP), 1820 – 2010
Source: The Maddison-Project, http://www.ggdc.net/maddison/maddison-project/home.htm 2013 version.
Figure 4 shows that New Zealand was richer than Australian in the first part of the post-war period. The divergence started with the onset of the lost decades in New Zealand in the early 1970s.
Is the Mother Country catching up with Down Under? Real GDP per working age New Zealander, British and Australian, detrended, 1956 –2013
15 May 2015 Leave a comment
in economic growth, economic history, macroeconomics, politics - Australia, politics - New Zealand Tags: Australia, British economy, lost decades
Figure 1: Real GDP per New Zealander, British and Australian aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1956-2013

Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
Figure 2: Real GDP per New Zealander, British and Australian aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended, 1956-2013
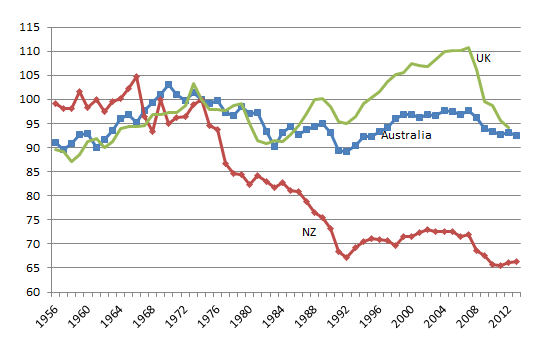
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
Annual hours worked per working age American, German and French, 1950–2013
12 May 2015 Leave a comment
in applied price theory, economic growth, economic history, great depression, labour economics, labour supply, macroeconomics, politics - USA, Public Choice, public economics, taxation Tags: Edward Prescott, Euroclerosis, France, Germany, labour supply, Robert Lucas, taxation and labour supply
Figure 1 shows that Americans work the same hours per year pretty much the entire post-war period. By contrast, there is been a long decline in hours worked in Germany and France. The large drop in 1992 was German unification.
Figure 1: annual hours worked per working age American, German and French, 1950 – 2013

Source: OECD StatExtract and The Conference Board Total Economy Database™,January 2014, http://www.conference-board.org/data/economydatabase/
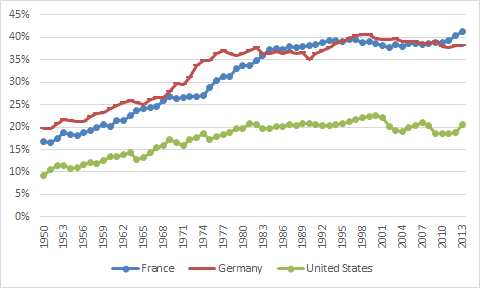
The long decline seemed to tally with the disproportionately sharp rise in the average tax rate on labour income, including social security contributions in France and Germany. When tax rates on labour income, including social security contributions stabilised in about 1980, hours worked stabilised in all countries.
Figure 2: average tax rate on labour income,USA, Germany and France, 1950 – 2013
Source: Source: Cara McDaniel.
Some pander to the great vacation theory of European labour supply. This is the hypothesis of a large increase in the preference for leisure in the European Union member states. That is, mass voluntary unemployment and mass voluntary reductions and labour supply by choice by Europeans. They just decided to work less.
This is not the first outing for the great vacation theory of labour supply. In the late 1970s, Modigliani dismissed the new classical explanation of Lucas and Rapping (1969) of the U.S. great depression in which the 1930s unemployment was voluntary unemployment – the great depression was just a great vacation – with the following remarks:
Sargent (1976) has attempted to remedy this fatal flaw by hypothesizing that the persistent and large fluctuations in unemployment reflect merely corresponding swings in the natural rate itself.
In other words, what happened to the U.S. in the 1930’s was a severe attack of contagious laziness!
I can only say that, despite Sargent’s ingenuity, neither I nor, I expect most others at least of the non-Monetarist persuasion, are quite ready yet. to turn over the field of economic fluctuations to the social psychologist!
As Prescott has pointed out, the USA in the Great Depression and France since the 1970s both had 30% drops in hours worked per adult. That is why Prescott refers to France’s economy as depressed. The reason for the depressed state of the French (and German) economies is taxes, according to Prescott:
Virtually all of the large differences between U.S. labour supply and those of Germany and France are due to differences in tax systems.
Europeans face higher tax rates than Americans, and European tax rates have risen significantly over the past several decades.
Countries with high tax rates devote less time to market work, but more time to home activities, such as cooking and cleaning. The European services sector is much smaller than in the USA.
Time use studies find that lower hours of market work in Europe is entirely offset by higher hours of home production, implying that Europeans do not enjoy more leisure than Americans despite the widespread impression that they do. Europeans did not work less. They worked more on activities that were not taxed.
A volatile depressed neighbour? Real American and Canadian GDP growth detrended, 1955-2013 – updated
11 May 2015 Leave a comment
in business cycles, economic growth, economic history, macroeconomics, politics - USA Tags: Canada, prosperity and depression
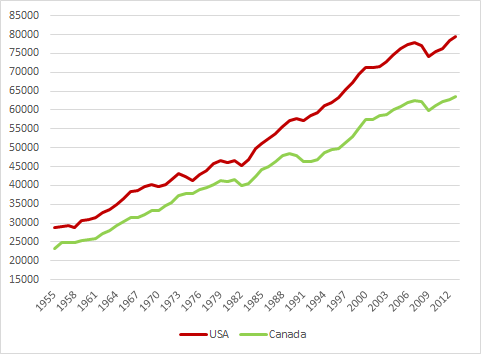
Figure 1: Real GDP per American and Canadian aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
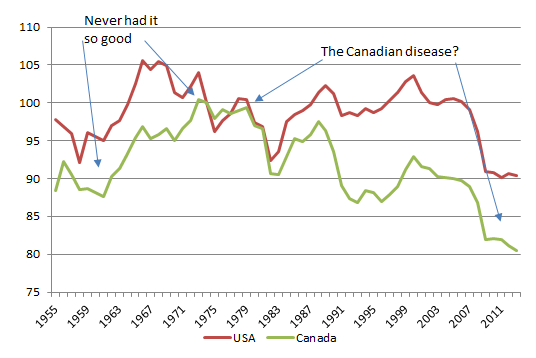
Figure 2: Real GDP per American and Canadian aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
A rising line in figure 2 is above trend rate growth; a flat line is trend growth of 1.9%; and a falling line is below trend growth.
Canada has a volatile ride in the post-war period after economic success up until 1975. Despite ups and downs the Canadian economy has been in a long-term decline since 1975. Growth as rarely being at trend and was often below, sometimes sharply below trend.
None of these depressed periods in the Canadian economy were long enough to count as a great depression. Instead there was just a long-term decline.
Canada is next door to the USA and a member of the North American Free Trade Area (NAFTA) and its antecedents so its cannot blame distance nor small size for its decline in economic performance as some do in New Zealand.
Relative to the USA, Rao et al. (2006) and Sharp (2003) attributed the gap between the USA and Canada to less capital per Canadian worker, an innovation gap as shown by lower R&D expenditure in Canada, a smaller and less dynamic high technology sector in Canada, less developed human capital at the top end of the Canadian labour market, and more limited scale and scope economies in Canada.
These factors have been put forward, at one time or another, as the proximate causes of the New Zealand productivity gap with the USA. Identifying the barriers to higher Canadian productivity may offer fresh insights into removing similar productivity barriers in New Zealand.
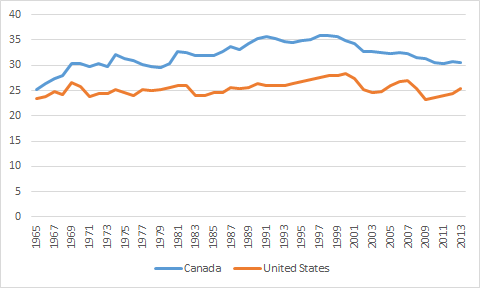
Figure 3 suggests that the increase in tax revenues as a percentage of GDP from 30% to 35% at the same time as the Canadian economic boom came to an end and its economic decline began is worthy of further scrutiny. The strong economic recovery from 1995 onwards also coincided with the decline tax revenues as a percentage of GDP.
Figure 3: tax revenue as a percentage of GDP
Source: OECD StatExtract
Where has all the productivity gone?
11 May 2015 Leave a comment
in business cycles, economic growth, Euro crisis, fiscal policy, global financial crisis (GFC), great depression, great recession, macroeconomics Tags: labour productivity, prosperity and depression, TFP
Britain has led most of the rich world in job creation, but badly lagged in productivity. on.wsj.com/1IiEjli http://t.co/URIFuFS9Il—
Sudeep Reddy (@Reddy) May 07, 2015
Land use regulation knocks 10 points of US GDP!
10 May 2015 Leave a comment
in economic growth, economics of regulation, income redistribution, macroeconomics, politics - New Zealand, politics - USA, rentseeking, urban economics Tags: Enrico Moretti, Green Left, housing affordability, Inner-city Left, labour mobility, land supply, land use planning, land use regulation, NIMBYs, regional mobility, RMA, zoning
Bloomberg Business highlighted a great new study by Enrico Moretti on power of the regulatory restrictions on land supply to destroy wealth.

Moretti focused on the impact that restrictions on land supply have on the ability of workers to move to higher productivity cities. Moretti is the second best urban economist working at the moment. The best is Ed Glaeser. Moretti concluded that
A limited number of American workers can have access to these very high-productivity cities
He concluded that a more efficient distribution would be “a general benefit for the entire economy.”
The secret of his analysis was to look at how different US cities, the high productivity cities, contributed to national economic growth. He then explore the implications of fewer and fewer workers been able to move to these cities to take advantage of the great productive potential. The barrier to them moving was high housing prices and high rents.
For example, labour productivity grew quickly in San Francisco, New York and San Jose overt 45-years. All of these cities are famous for their human capital-intensive industries including technology and finance. These cities weren’t America’s growth engine:
The reason is that the main effect of the fast productivity growth in New York, San Francisco, and San Jose was an increase in local housing prices and local wages, not in employment.
Despite the large difference in local GDP growth between New York, San Jose, and San Francisco and the Rust Belt cities, both groups of cities had roughly the same contribution to aggregate output growth.
The drivers of US growth between 1964 and 2009 were southern U.S. cities and 19 other large cities. These cities attracted many residents because of good weather and abundant supply of cheap housing.
The lesson both the US and for New Zealand, and Auckland in particular, is this reallocation of population away from the expensive cities with restricted land supply reduced national output because these population movements bring workers to cities "where the marginal product of labour is low."
In a technology boom town such as San Francisco, it is now what like New Zealand will be as Generation Rent runs its course – 65% of residents are renters:
Over the past year, the City and County of San Francisco boasted the second strongest labour market in the nation, adding 25,000 new jobs. Yet only 2,548 new housing units were permitted and even fewer were built.
Just think: 25,000 new workers and their families have been knocking on San Francisco doors, but there are new units for less than 10 percent of them. It is not surprising that apartment prices get bid up.
US and Canadian unemployment rates, 1956–2014
10 May 2015 Leave a comment
in business cycles, economic growth, job search and matching, labour economics, labour supply, macroeconomics, politics - USA, unemployment Tags: Canada, unemployment rates
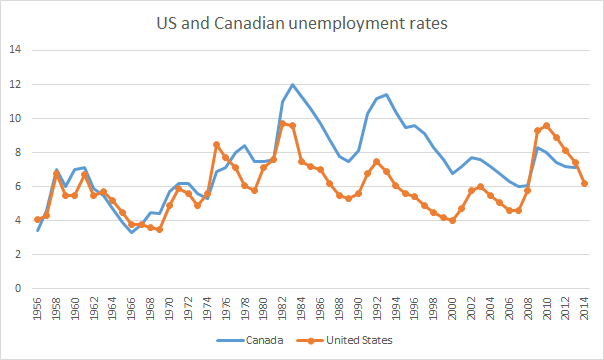
Source: OECD StatExtract
Unemployed people are defined as those who report that they are without work, that they are available for work and that they have taken active steps to find work in the last four weeks.
The ILO Guidelines specify what actions count as active steps to find work; these include answering vacancy notices, visiting factories, construction sites and other places of work, and placing advertisements in the press as well as registering with labour offices.
Unemployment isn’t much of an issue for the well educated in recessions
09 May 2015 Leave a comment
in business cycles, economic growth, economics of education, human capital, job search and matching, labour economics, labour supply, macroeconomics, occupational choice, unemployment Tags: labour demographics, prosperity and depression
#StayinSchool
April jobless rate for people 25+ with
B.A. or more: 2.7%
No h.s. diploma: 8.6%
on.wsj.com/1H63SHl http://t.co/UwzHjiaQz9—
Sudeep Reddy (@Reddy) May 08, 2015
April jobless rate by race/ethnicity:
Black 9.6%
Hispanic: 6.9%
White 4.7%
Asian 4.4%
on.wsj.com/1H619hg http://t.co/qgRWa7MB85—
Sudeep Reddy (@Reddy) May 08, 2015
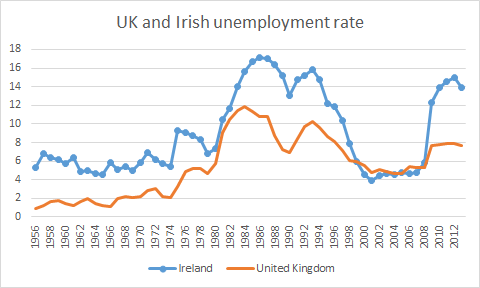
The sick men of Europe? British and Irish unemployment rates, 1956–2013
09 May 2015 Leave a comment
in economic growth, economic history, great depression, job search and matching, labour economics, labour supply, macroeconomics, unemployment Tags: British economy, Celtic Tiger, Ireland, prosperity and depression, sick man of Europe, unemployment rates
Source: OECD StatExtract
Ireland and Britain justly earned the name the sick man of Europe in the 1980s. Irish unemployment was in the mid teens much of the 1980s because the Irish economy was in a great depression from 1973 to 1992.
Unemployed people are defined as those who report that they are without work, that they are available for work and that they have taken active steps to find work in the last four weeks. The ILO Guidelines specify what actions count as active steps to find work; these include answering vacancy notices, visiting factories, construction sites and other places of work, and placing advertisements in the press as well as registering with labour offices.
Two booms, two depressions: British and Irish real GDP detrended, 1955–2013
07 May 2015 1 Comment
in business cycles, economic growth, economic history, entrepreneurship, global financial crisis (GFC), great depression, macroeconomics Tags: British disease, British economy, Celtic Tiger, Ireland, prosperity and depression, sick man of Europe
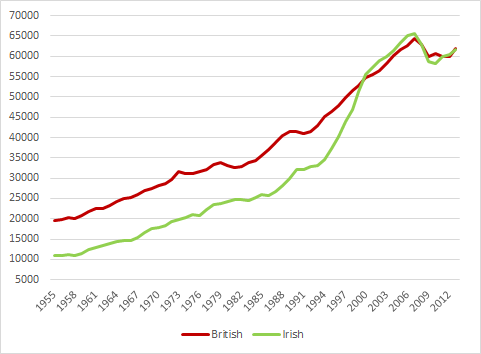
Figure 1: Real GDP per British and Irish aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
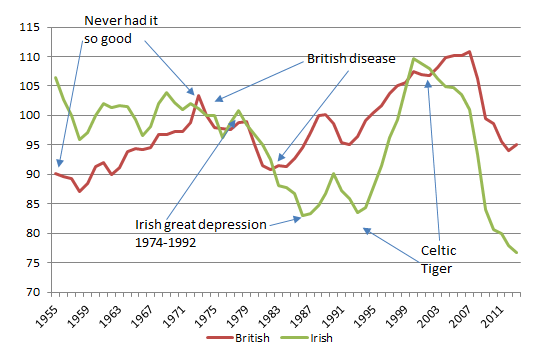
Figure 2 detrends British real GDP growth since 1955 by 1.9% and Irish real GDP growth by 3.6%. The US real GDP growth in the 20th century is used as the measure of the global technological frontier growing at trend rate of 1.9% in the 20th century. The Irish economy is more complicated story because its growth rate in figure 2 was detrended at a rate of 3.6% because it was catching up from a very low base. Trend GDP growth per working age Irish for 1960-73 was 3.6 per cent (Ahearne et al. 2006).
Figure 2: Real GDP per British and Irish aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended UK, 3.6% detrended Ireland, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
A flat line in figure 2 indicates growth at 1.9% for that year. A rising line in figure 2 means above-trend growth; a falling line means below trend growth for that year.
In the 1950s, Britain was growing quickly that the Prime Minister of the time campaigned on the slogan you never had it so good.
By the 1970s, and two spells of labour governments, Britain was the sick man of Europe culminating with the Winter of Discontent of 1978–1979. What happened? The British disease resulted in a 10% drop in output relative to trend in the 1970s, which counts as a depression – see figure 2 .
Prescott’s definition of a depression is when the economy is significantly below trend, the economy is in a depression. A great depression is a depression that is deep, rapid and enduring:
- There is at least one year in which output per working age person is at least 20 percent below trend; and
- there is at least one year in the first decade of the great depression in which output per working age person is at least 15 percent below trend; and
- There is no significant recovery during the period in the sense that there is no subperiod of a decade or longer in which the growth of output per working age person returns to rates of 2 percent or better.
The British disease in the 1970s bordered on a depression. There was then a strong recovery through the early-1980s with above trend growth from the early 1980s until 2006 with one recession in between in 1990. So much for the curse of Thatchernomics?
Figure 1 suggests a steady economic course in Ireland until the 1990s with a growth explosion growth with the Irish converged on British living standards up until the global financial crisis.
Figure 2 shows the power of detrending GDP growth and why Ireland was known as the sick man of Europe in the 1970s and 1980s with unemployment as high as 18% and mass migration again. The Irish population did not grow for about 60 years from 1926 because of mass migration.
Figure 2 shows that real GDP growth per working age Irish dropped below its 3.6 per cent trend for nearly 20 years from 1974 , but more than bounced back after 1992. The deepest trough was 18 per cent below trend and the final trough was in 1992 – see Figure 2.
The deviation from trend economic growth made the Irish depression from 1973 to 1992 comparable in depth and length to the 1930s depressions (Ahearne et al. 2006).
The Irish depression of 1973 to 1992 can be attributed to large increases in taxes and government expenditure and reduced productivity (Ahearne et al. 2006). There were two oil price shocks in the 1970s and many suspect Irish policy choices from 1973 to 1987.
There were three fiscal approaches: an aggressive fiscal expansion from 1977; tax-and-spend from 1981; and aggressive fiscal cuts from 1987 onwards. In the early 1980s, Irish CPI inflation at 21 per cent, public sector borrowing reached 20 per cent of GNP.
To rein in budget deficits, taxes as a share of GNP rose by 10 percentage points in seven years. The unemployment rate reached 17 per cent despite a surge in emigration. The rising tax burden raised wage demands, worsening unemployment. Government debt grew on some measures to 130 per cent of GNP in 1986 (Honohan and Walsh 2002).
From 1992, Ireland rebounded to resume catching-up with the USA. The Celtic Tiger was a recovery from a depression that was preceded by large cuts in taxes and government spending from the late 1980s (Ahearne et al. 2006). Others reach similar conclusions but avoid the depression word. Fortin (2002, p. 13) labelled Irish public finances in the 1970s and to the mid-1980s as a ‘black hole’.
Fortin (2002) and Honohan and Walsh (2002) disentangle the Irish recovery into a long-term productivity boom that had dated from the 1950s and 1960s, and a sudden short-term output and employment boom since 1993 following the late 1980s fiscal and monetary reforms.
Honohan and Walsh (2002) wrote of belated income and productivity convergence. The delay in income and productivity convergence came from poor Irish economic and fiscal policies in the 1970s and 1980s.
This was after economic reforms in the late 1950s and the 1960s that started a process of rapid productivity convergence after decades of stagnation and mass emigration; Ireland’s population was the same in 1926 and 1971. During the 1950s, up to 10 per cent of the Irish population migrated in 10 years.
In the 1990s, many foreign investors started invested in Ireland as an export platform into the EU to take advantage of a 12.5 per cent company tax rate on trading profits. Between 1985 and 2001, the top Irish income tax rate fell from 65 to 42 per cent, the standard company tax from 50 to 16 per cent and the capital gains tax rate from 60 to 20 per cent (Honohan and Walsh 2002).
What happened after the onset of the global financial crisis in Ireland and the UK are for a future blog posts.
Real GDP Portugal, Italy, Greece and Spain (PIGS) – 1955 to 2013
06 May 2015 Leave a comment
in currency unions, economic growth, Euro crisis, macroeconomics Tags: Eurosclerosis, Greece, Italy, PIGS, Portugal, Spain
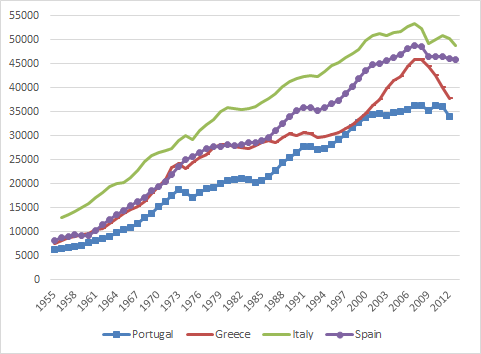
Figure 1: Real GDP per Portuguese, Italian, Greek and Spaniard aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
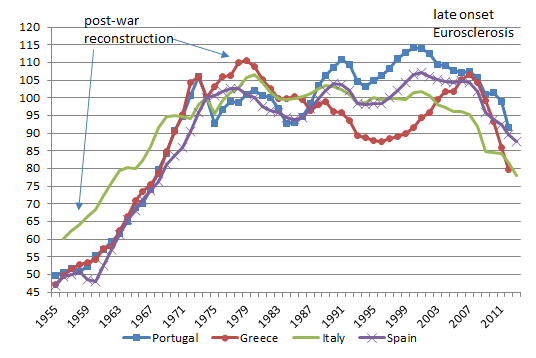
Figure 2: Real GDP per Portuguese, Italian, Greek an Spaniard aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
Note that a flat line in figure 2 is growth in real GDP for that year at 1.9%; a rising line is above trend rate of growth; and a falling line is below trend rate growth for that year.
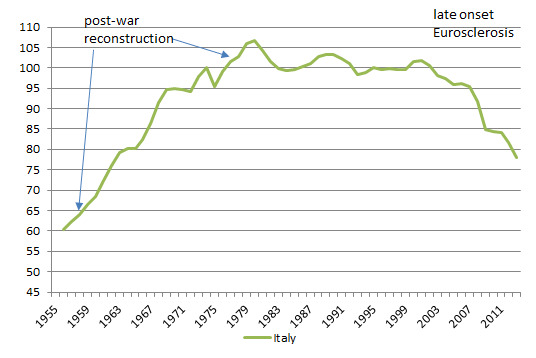
The PIGS had three distinct phases in their post-war growth. Rapid growth up until about the mid 70s. Growth at about the trend rate of growth of 1.9% until about 2000 in the case of Italy. This was followed by slow decline then rapid decline after the global financial crisis.
Figure 3: Real GDP per Italian aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
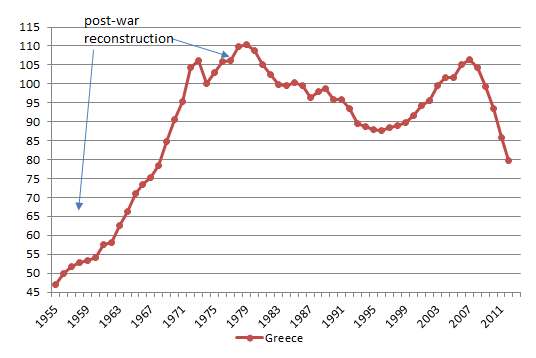
Greece had a different story with the long decline between 1979 to 1995. This was followed by 10 good years of growth followed by sharp decline with the onset of the global financial crisis.
Figure 4: Real GDP per Greek aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
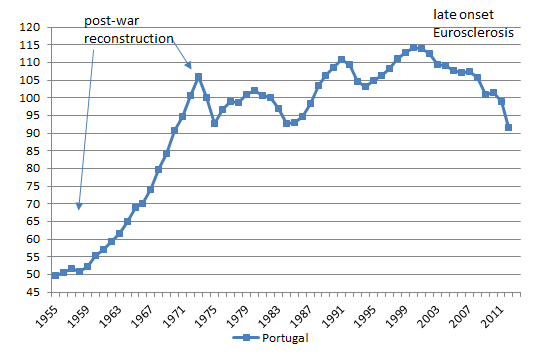
Portugal was in a boom In the 1980s and 1990s followed by what borders on a depression since about 2000.
Figure 5: Real GDP per Portuguese aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
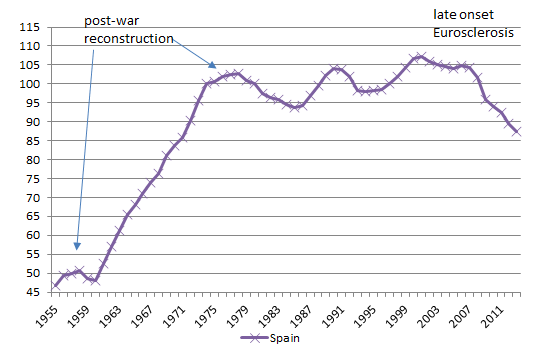
Spain had a pretty good run from the mid-1980s until the eve of the global financial crisis with somewhat above trend growth after a period of decline in the 1970s.
Figure 6: Real GDP per Spaniard aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended, 1955-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
Post-war reconstruction then Eurosclerosis – Germany, Italy and France 1950-2013
04 May 2015 Leave a comment
in currency unions, economic growth, economic history, Euro crisis, macroeconomics Tags: Eurosclerosis, France, Germany, Italy, post-war reconstruction
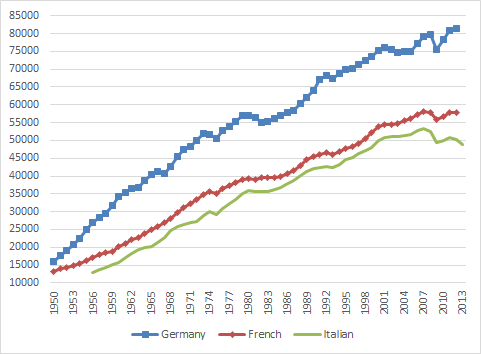
Figure 1: Real GDP per German, Italian and French aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1950-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
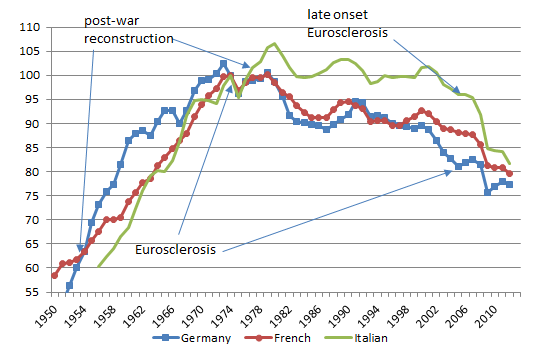
Figure 2: Real GDP per German, Italian and French aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1.9 per cent detrended, 1950-2013
Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
A flat line in figure 2 means real GDP growth of 1.9% per year, which is trend growth. A rising line means growth that is higher than trend rate; a falling line means growth at below the trend rate of 1.9%. 1.9% is the trend rate of growth of the USA in the 20th century. Figure 2 shows that:
- Germany, Italy and France all boomed until the mid-1970s;
- the French and German economies went into a long-term decline from that time; and
- the Italian economy stopped growing at anything more than the trend rate of growth between the mid-1970s and the mid-1990s and then went into a sharp decline that borders on the depression.


Recent Comments