Recent New Zealand economic growth
06 Apr 2015 Leave a comment
in business cycles, economic growth, fiscal policy, global financial crisis (GFC), macroeconomics, politics - USA Tags: GFC, great recession, recessions and recoveries
Trans-Tasman trends in real equivalised mean household income since 1982
04 Apr 2015 Leave a comment
in business cycles, economic growth, global financial crisis (GFC), macroeconomics, politics - Australia, politics - New Zealand Tags: GFC, Rogernomics, Trans-Tasman income gap
@JimRose69872629 @JohnQuiggin @pagdavidson Largest fall in real mean incomes in NZ was in the early 1990s http://t.co/DDVgeMIGsj—
Peter Whiteford (@WhitefordPeter) April 04, 2015
Real household mean incomes rose during Rogernomics; fell during the deep recession at the beginning of the early 1990s; then rose strongly until 2009 and the onset of the Global Financial Crisis.
Recent New Zealand economic growth compared
31 Mar 2015 Leave a comment
in economic growth, macroeconomics, politics - Australia, politics - New Zealand, politics - USA
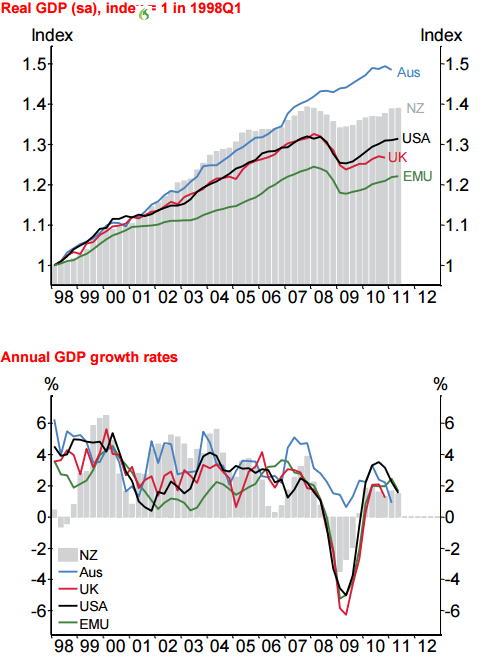
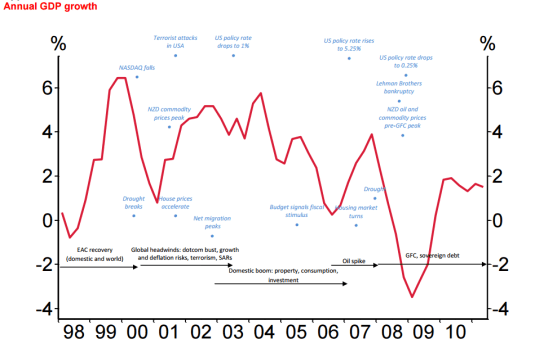
The impact of drought on the 1998 mild New Zealand recession
31 Mar 2015 Leave a comment
in business cycles, economic growth, macroeconomics, politics - New Zealand Tags: 1998 recession, drought, real business cycles
Reserve Bank of New Zealand has these conclusions about the contribution of drought to the business cycle in the late 1990s in New Zealand and in particular the mild 1998 recession:
a back-of-the-envelope estimate of the impact of the drought-induced fall in supply would suggest a contribution from the agricultural sector to production GDP for the March quarter of 1998 of around -0.4 percentage points out of the total 1 per cent fall in production GDP. In the June quarter of 1998, the contribution from these sectors was close to zero.
Figure 27:

In 1998, agricultural and hunting industry contributed per cent of real GDP. . That included the production of livestock, wool, dairy, horticulture, and crops, as well as the provision of agricultural contracting services and hunting. In the same year, the primary food manufacturing industry contributed 3 per cent of GDP. This category covers the processing of meat and dairy products for export and local markets.
Blaming droughts on Rogernomics? Droughts and the New Zealand real business cycle
28 Mar 2015 Leave a comment
in economic growth, economic history, macroeconomics, politics - New Zealand
While feuding on another blog about the ups and downs of the New Zealand economy since the 1970s, I pointed out that a long economic boom followed the Ruth Richardson “Mother of all Budgets” in 1991:

My interlocutor quickly replied to blame Rogernomics, in particular, inflation targeting and its administration by Don Brash for a severe recession in New Zealand in 1998:
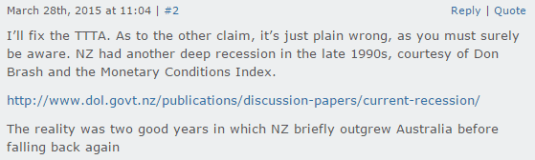
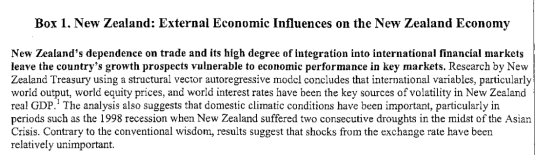
The mild recession in New Zealand in 1998 was a result of the combination of two severe droughts and the effects of the Asian financial crisis.
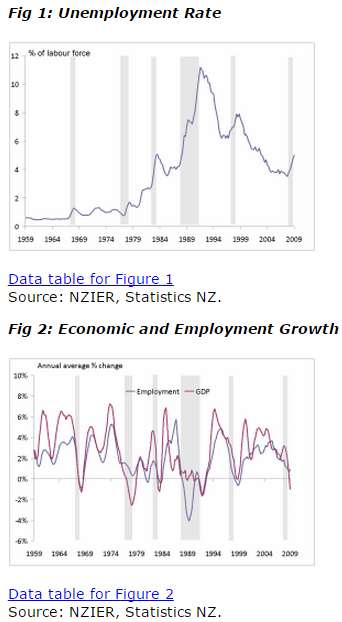
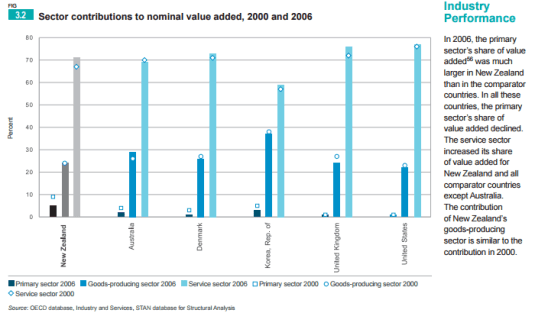
Drought is a major factor in the New Zealand business cycle because of the large size of the farming sector. Indeed, the ups and downs of a monopoly dairy exporter that accounts for 7% of GDP, Fonterra, are so central that a single dirty pipe at a milk factory that put the quality of its milk exports in question lead the Treasury to revise its economic forecasts for that year.
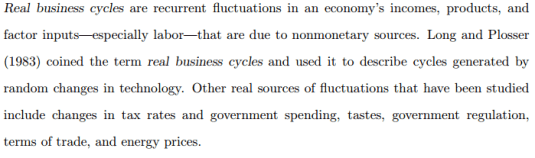
There is growing evidence that a substantial part of business cycle volatility can be explained by real business cycle theory (RBC). RBC claims that a good majority of economic volatility is caused by changes on the supply side: tax and regulatory changes, bad weather in farm economies, spikes in oil prices and technology shocks. Real business cycle models have enjoyed success in replicating most of the observed characteristics of, for example, U.S. aggregate economic activity.
Over the last 15 years, a number of papers at the Treasury and Reserve Bank of New Zealand have explored the role of droughts in the New Zealand business cycle, such as the drought in 1997.
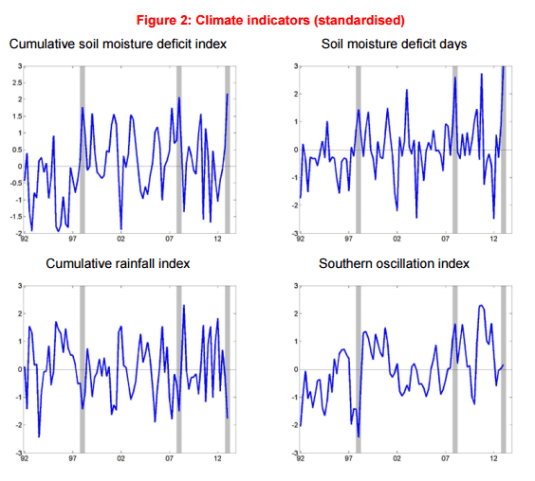
The 1998 recession was preceded by a severe drought that may have knocked a half percentage point off GDP or more. As the Treasury explained in 2008:
Given the importance of the primary sector in New Zealand, climatic conditions have always been a significant driver of GDP volatility in New Zealand. There is strong evidence that the 1998 drought triggered or precipitated the onset of the last recession in the late-90s.
In 2008, the dry conditions in New Zealand led the Treasury to revise its forecasts as follows:
current dry conditions are likely to trim GDP growth by around 0.5% for the 2008 calendar year.
In 2013, the Reserve Bank made similar pessimistic forecasts about the implications of drought for economic prospects. New Zealand was suffering its worst drought in decades:

It was simply mistaken to blame the 1998 recession in New Zealand as the spawn of Rogernomics. There was a drought, a big one, big enough drought to shake the New Zealand business cycle in a country with a large farming sector.

The most important aspect of monetary strategy is timing
28 Mar 2015 Leave a comment
in business cycles, economic growth, economics of information, macroeconomics, Milton Friedman, monetarism, monetary economics, Robert E. Lucas Tags: Keynesian macroeconomics, lags on monetary policy, monetary policy
The simplest statement to make about the lags in monetary policy is they are long and variable. This simple statement is also the key insight to understanding the actual implementation of monetary policy. Hence, how many months or years in advance must a central bank forecast to achieve its monetary goals? In 1994, the Economist said:
But [central banks] cannot afford to wait until inflation is actually rising before they act. Monetary policy does not change the speed of the economy instantly: it can take 18 months or more for a rise in interest rates to have its full impact on inflation. The target of policy ought therefore to be future not current inflation, in order to prevent a surge in 1996. The earlier interest rates are raised, the better the chances of engineering a smooth slowdown to a sustainable rate of growth before slack in the economy is exhausted.
Economists differ about the length of those lags. Uncertainty about the average length of those lags and the variability of those lags makes discretion most difficult. Activist policy can improve welfare only if the information about economic structure and economists’ ability to forecast is sufficiently accurate.

Friedman is the most famous and persuasive critic of Keynesianism on the grounds of lags. He has two main arguments: first, that there are “long and variable lags” between the identification of a problem and the effects of the designed remedy; second, that activist policy often itself becomes a source of instability since policy itself becomes a variable that the market must guess.
Friedman’s critique does not depend on the quantity theory of money. Keynesian policies do not necessarily follow even if the Keynesian theory of the business cycle were conclusively proved.
It must also be demonstrated that the government has the ability and willingness of the government to act as the theory prescribes. We are therefore further assuming that central banks have the incentive to stabilise the economy. If the government lacks the information required to stabilise the economy, issues of public choice incentives become fully redundant. Incentives to pursue an objective do not matter if the objective itself is unattainable.
Competing visions of central banking
25 Mar 2015 1 Comment
in business cycles, economic growth, inflation targeting, macroeconomics, Milton Friedman, monetarism, monetary economics, Robert E. Lucas Tags: Keynesian macroeconomics, monetary policy

The competing visions of central banks over monetary policy have been defined by Franco Modiglani and Milton Friedman respectively. Modiglani considers the Keynesian vision of macroeconomic policy to be:
a market economy is subject to fluctuations which need to be corrected, can be corrected, and therefore should be corrected.
The Keynesian claim implies that central banks have sufficient knowledge of the structure of the economy to be able to choose the policy mix appropriate to a given set of circumstances. It is possible to target unemployment, interest rates and inflation in such a way that they can be maintained (and hence made predictable) by constant adjustment of policy instruments to new shocks.
The Keynesian approach assumes that the economy can slip into recessions for all sorts of reasons (Barro 1989). Business fluctuations result from shocks to aggregate demand. The principal source of these shocks are expectations induced shifts in investment demand. The role of the central bank is to make prompt, frequent policy responses to counteract this instability.
The task of government is to discover the particular monetary and fiscal polices which can eliminate shocks emanating from the private sector. A key finding of recent macroeconomic research is that anticipated monetary policy has very different effects to unanticipated monetary policy.
The Keynesian vision thus presuppose that government can foresee shocks which are invisible to the private sector but at the same time it is unable to reveal this advance information in a credible way and hence defusing the shock because it is no longer unanticipated. In addition, the counter cyclical monetary policies of governments must themselves be unforeseeable by private agents, but at the same time systematically related to the state of the economy (Lucas and Sargent 1979)
Of course, the Keynesian view of central banking is also premised on a goodwill theory of government. Governments pursue policies that are in the public interest. That is a public interest that is well-defined and is free of conflicts over income distribution, electoral success and power the could lead policy-makers to pursue goals other than full employment, stable prices and efficiency. Thus, if the latest forecast is a recession, additional stimulus is the usual prescription. However, since most Keynesian economists accept the permanent income and natural rate hypotheses, more stimulus implies less later at some unknown time.
Friedman’s vision of central banking is far more circumspect:
The central problem is not designing a highly sensitive [monetary] instrument that offsets instability introduced by other factors[in the economy], but preventing monetary arrangements becoming a primary source of instability (Milton Friedman 1959).
Friedman considers that a key element in the case for policy discretion is whether the sufficient information is available that can be used to reduce variability and assist the economy’s adjustment the unforeseen. A well intentioned policy-maker will destabilise if he is mislead by incomplete or incorrect information.

From the monetarist standpoint, price stability can be approximately attained under a well chosen and predictable monetary policy rule. Under this view, the unemployment and interest rates are unpredictable and can manipulated only at a prohibitive cost. The Keynesian and monetarist views are mutually incompatible and lead to very different policy recommendations (Lucas 1981).
Why Portugal, Italy, Greece and Spain are called the PIGS
23 Mar 2015 Leave a comment
in economic growth, economic history, Euro crisis, macroeconomics

HT: Finn Kydland
Roberts Solow on the British disease and Eurosclerosis
21 Mar 2015 Leave a comment
in currency unions, economic growth, economics of regulation, Euro crisis, fiscal policy, job search and matching, labour economics, labour supply, macroeconomics Tags: British disease, Euroland, European Union, Eurosclerosis, Robert Solow
HT: Brad Delong
Why is it so expensive to eat in Europe as compared to America?
21 Mar 2015 Leave a comment
in applied welfare economics, economic growth, politics - USA
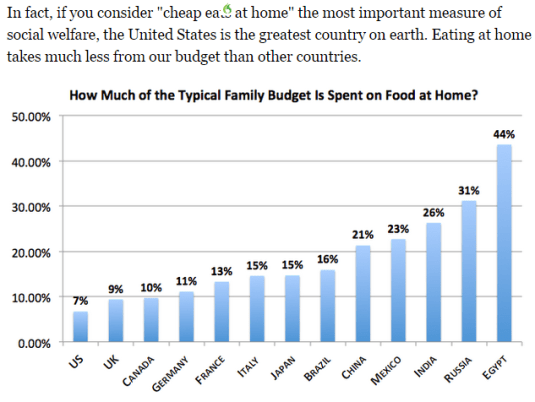
The Entire Global Economy in 1 Slide – Bloomberg Business
19 Mar 2015 Leave a comment
in business cycles, economic growth, Euro crisis, politics - Australia, politics - New Zealand, politics - USA Tags: global economic integration

Paul Samuelson on where he disagreed with Milton Friedman on macroeconomic policy
19 Mar 2015 Leave a comment
in budget deficits, business cycles, economic growth, fiscal policy, inflation targeting, macroeconomics, Milton Friedman, monetarism, monetary economics Tags: fiscal policy, monetary policy, Paul Samuelson, rules versus discretion, stabilisation policy
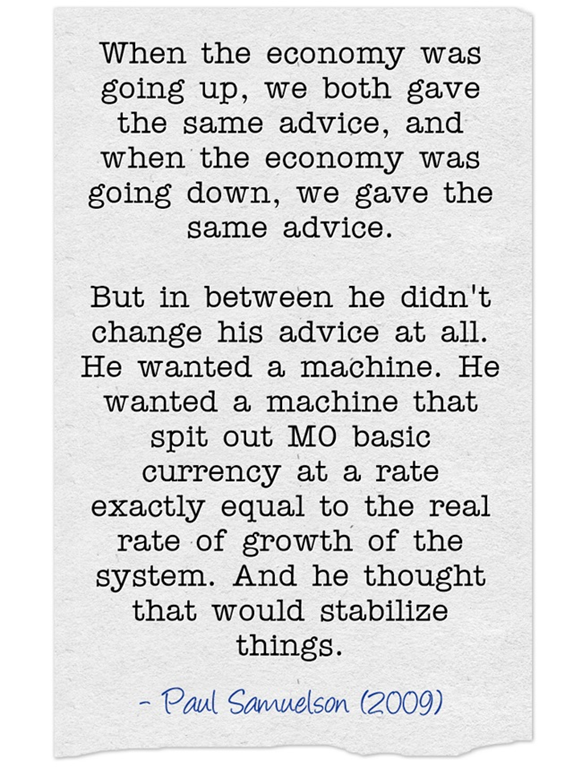
via Samuelson vs. Friedman, David Henderson | EconLog | Library of Economics and Liberty and An Interview With Paul Samuelson, Part One — The Atlantic.
 Utopia, you are standing in it!

Recent Comments