Milton Friedman on what presidents can do to increase the economic growth rate
28 Jun 2014 1 Comment
in economic growth, macroeconomics, Milton Friedman Tags: Milton Friedmand, The fatel conceit, The pretense to knowledge
First of all, I don’t think the president has a great deal to do with keeping the economy going…
I think presidents have a great deal to do with keeping the economy from growing…
I think the economy is largely independent of the government, and what keeps it going is its own internal development.
However, you can short-circuit that internal development. If you impose very high taxes, and eliminate the incentive to innovate, to improve, to take risks, and do things, you’ll kill the economy. And that’s what’s happened over and over again in other countries around the world.
Are you now or have you ever been a monetarist?
26 Jun 2014 Leave a comment
in macroeconomics, Milton Friedman, monetarism Tags: Milton Friedman, monetarism, The Fed

Milton Friedman argued that no member of the Fed would have ever answered yes to that question.
Milton Friedman on the future of the Euro
23 Jun 2014 Leave a comment
in currency unions, Euro crisis, macroeconomics, Milton Friedman Tags: Euro, optimal currency areas
I think the euro is in its honeymoon phase. I hope it succeeds, but I have very low expectations for it.
I think that differences are going to accumulate among the various countries and that non-synchronous shocks are going to affect them. Right now, Ireland is a very different state; it needs a very different monetary policy from that of Spain or Italy.
You know, the various countries in the euro are not a natural currency trading group. They are not a currency area. There is very little mobility of people among the countries.
They have extensive controls and regulations and rules, and so they need some kind of an adjustment mechanism to adjust to asynchronous shocks—and the floating exchange rate gave them one. They have no mechanism now.
If we look back at recent history, they’ve tried in the past to have rigid exchange rates, and each time it has broken down. 1992, 1993, you had the crises. Before that, Europe had the snake, and then it broke down into something else.
So the verdict isn’t in on the euro. It’s only a year old. Give it time to develop its troubles (2000)
AND
The drive for the Euro has been motivated by politics not economics.
The aim has been to link Germany and France so closely as to make a future European war impossible, and to set the stage for a federal United States of Europe.
I believe that adoption of the Euro would have the opposite effect.
It would exacerbate political tensions by converting divergent shocks that could have been readily accommodated by exchange rate changes into divisive political issues.
The order brought about by the mutual adjustment of many individuals in a market
21 Jun 2014 Leave a comment
in applied price theory, comparative institutional analysis, F.A. Hayek, Milton Friedman Tags: Adam Smith, FA Hayek, Milton Friedman, Pete Boetkke, spontaneous order

Pete Boettke has written extensively about how The Wealth of Nations is about social order among strangers. The market is a social order much larger than our span of moral sympathy.
In civilized society [man] stands at all times in need of the co-operation and assistance of great multitudes, while his whole life is scarce sufficient to gain the friendship of a few persons. In almost every other race of animals each individual, when it is grown up to maturity, is entirely independent, and in its natural state has occasion for the assistance of no other living creature.
But man has almost constant occasion for the help of his brethren, and it is in vain for him to expect it from their benevolence only. He will be more likely to prevail if he can interest their self-love in his favour, and show them that it is for their own advantage to do for him what he requires of them.
Whoever offers to another a bargain of any kind, proposes to do this. Give me that which I want, and you shall have this which you want, is the meaning of every such offer; and it is in this manner that we obtain from one another the far greater part of those good offices which we stand in need of.
To realize this social cooperation, Boettke argues that social institutions must be in place such as private property, keeping promises through contract, and the acceptance of the legitimacy of the transfer of property by consent. The division of labour is the key to the ability of the market system to produce social cooperation among distant and different anonymous actors.
The civilising influence of commerce is well-known as is it as the key to peace. We fear neither Russia nor China because of extensive economic interdependencies makes war pointless for all. The common market ended war in Western Europe.
The co-operation and peace is a spontaneous product of Hayek’s concept of catallaxy which is
the order brought about by the mutual adjustment of many individual economies in a market
The youtube clip is Milton Friedman’s discussion of the famous essay I, Pencil and how strangers cooperated in peace and harmony in the market even though they might hate each other if they ever met. I, Pencil details the complexity of its own creation and the numerous people involved is the absence of a master mind, of anyone dictating or forcibly directing these countless actions. Instead, we find the invisible hand at work.
Capitalism is a system which enables cooperation between millions of strangers so that they may jointly pursue their diverse goals.
Machiavelli, Mises, Milton Friedman, W.H. Hutt and Walsingham’s Manual on practical public policy advising
21 Jun 2014 1 Comment
in constitutional political economy, James Buchanan, Ludwig von Mises, Milton Friedman, Murray Rothbard, Public Choice Tags: Machiavelli, W.H. Hutt, Walsingham's Manual

Ludwig Von Mises worked as an economic-policy advisor to the Vienna Chamber of Commerce from 1909 to 1934. As Richard Ebeling notes:
What comes out from reading Mises’s policy writings from this period of his European career is that if you had asked him a fiscal, or monetary, or regulatory-policy question in the context of his role as analyst at the Chamber of Commerce, he would not have said, and did not simply say, "laissez-faire" — abolish the central bank, deregulate the economy, and eliminate taxes.
Mises accepted the context of which his policy options must be worked out. Ebeling went on to note that Mises seemed to think in three policy horizons:
- The most optimal institutional and policy arrangements in society for the fostering of the classical-liberal ideal of freedom and prosperity, based on the knowledge that he thought sound economic theory could provide;
- the actual circumstances of the present, but focused on the intermediary goals that would be leading in the direction of that more distant, "optimal" horizon; and
- current situation and the immediate future
In the 1970s, Rothbard criticised Milton Friedman for advocating indexation of prices and wages as a method to reduce some of the negative effects from an on-going inflation. Rothbard regarded this as a sell-out.
Richard Nixon’s responses to Milton Friedman were rather more flattering in terms of his policy purity:
I don’t care what Milton Friedman says, he’s not running for re-election.
In 1922, during the worsening Great Austrian Inflation, Mises proposed indexation of wages and prices. Ebeling explained Mises as follows:
- what was inefficient and unnecessary in the three-tiered Austrian bureaucratic system of federal, provincial, and municipal regulators and taxing authorities;
- what specific reforms should be introduced, how they could be experimented with in smaller regions of Austria; and
- how best to overcome the resistance of those in the bureaucracy fearful of losing their jobs
Milton Friedman was purer than this – always the first best advice:
The role of the economist in discussions of public policy seems to me to be to prescribe what should be done in the light of what can be done, politics aside, and not to predict what is ‘politically feasible’ and then recommend it.
Little wonder that Friedman had little time for those economists who promised more than they could deliver and warned less than they should of the hazards and difficulties that may lie ahead the particular policies that were being considered:
A major problem of our time is that people have come to expect policies to produce results that they are incapable of producing. …
we economists in recent years have done vast harm—to society at large and to our profession in particular—by claiming more than we can deliver.
We have thereby encouraged politicians to make extravagant promises, inculcate unrealistic expectations in the public at large, and promote discontent with reasonably satisfactory results because they fall short of the economists’ promised land.
W.H. Hutt steered the middle course that I favour:
In our judgment, the best you will be able to get away with is programme A along the following lines; but if you could find a convincing way of really explaining the issue to the electorate, our advice would have to be quite different.
We should have to recommend programme B, along the following lines.
James Buchanan emphases political realities in a similar way:
We start from here, from where we are, and not from some idealized world peopled by beings with a different history and with utopian institutions. Some appreciation of the status quo is essential before discussion can begin about prospects for improvement.
Ebeling ends by saying:
Even as that uncompromising and principled proponent of individual liberty and the free market, Mises was called upon in his role as policy analyst and advocate to sometimes devise "second-" and "third-best" policy proposals in an imperfect world dominated by collectivist and interventionist ideas and practices.
for those who have sometimes asked, "Well, but how do you apply Austrian Economics to the ‘real world’ of public policy?" here is the answer by the economist who has been considered the most original, thoroughgoing, and uncompromising member of the Austrian School over the last one hundred years! His policy analyses provide us with warning signs and guideposts to assist us in thinking about and designing better policies for our own time.
In The Prince, Machiavelli said in a chapter on how to choose wise advisors and avoid flatterers.
Therefore a wise prince ought to hold a third course by choosing the wise men in his state, and giving to them only the liberty of speaking the truth to him, and then only of those things of which he inquires, and of none others; but he ought to question them upon everything, and listen to their opinions, and afterwards form his own conclusions.
With these councillors, separately and collectively, he ought to carry himself in such a way that each of them should know that, the more freely he shall speak, the more he shall be preferred; outside of these, he should listen to no one, pursue the thing resolved on, and be steadfast in his resolutions. He who does otherwise is either overthrown by flatterers, or is so often changed by varying opinions that he falls into contempt…
A prince, therefore, ought always to take counsel, but only when he wishes and not when others wish; he ought rather to discourage every one from offering advice unless he asks it; but, however, he ought to be a constant inquirer, and afterwards a patient listener concerning the things of which he inquired; also, on learning that any one, on any consideration, has not told him the truth, he should let his anger be felt.
I think Mises read less of Machiavelli and more of the now 400 year old book written by an French courter called not to A Practical Guide for Ambitious Politicians, or Walsingham’s Manual which Gordon Tullock republished in 1961.
I have a copy of this rare book republished in 1961 which was translated again in 2007 under the title Treatise on the Court. The Early Modern Management Classic on Organizational Behaviour.
For Mises to survive and prosper as a policy advisor as he struggled for position within a small elite group amidst fierce competition, he had to know how organisations worked, how to find the levers of power and press them. That is why is pitched his advice in light of the immediate,medium term or long term policy horizon horizon as set out in the dot points above.
Walsingham’s Manual has a whole chapter on when the courtier should warn of the hazards and difficulties that may lay ahead and when he should humour the prince in his inclinations that mesh well with what Mises did. There is another chapter on how to deal with rival courtiers that made Sir Humphrey proud:
Those who feel compelled to compete with you will not be won over by shows of respect or veneration. You can, however, coax them onto a different path by
- encouraging them to aim for a goal more ambitious than yours,
- helping them achieve this goal,
- offering to help advance their ambitions, and
- playing down your own goal as being too insignificant for them to aspire to.
Imply that you have no choice but to pursue your goal because you aren’t capable of competing (as they are) for anything better. By way of contrast, praise your competitors’ reputation, power, abilities and merit: suggest that they can do far better than you and should set their sights higher.
If ever you come to fear that a competitor may get ahead of you, raise doubts and insecurities in his mind about what he wants to do. Discuss the pros and cons of the matter, but always in a way that reinforces why he should give up and look elsewhere.
Your best and quickest course, though, is to disguise or hide your objective until it’s too late for anyone to compete with you or block you.
Pushing an ambitious plan too openly may repel the very people who would have helped you if you’d been more discreet, making your task more difficult and damaging your chances of success.
Then, if you do prevail, you’ll attract more envy than you would have otherwise, and if you fail, you’ll look that much more foolish. Your safest course is to do as rowers do, turning your back on your objective and showing every sign of having some other destination.
Double standards watch: was Milton Friedman a double secret communist agent?
20 Jun 2014 Leave a comment
in development economics, growth miracles, Milton Friedman Tags: Chile, China, double standards, Milton Friedman, tinpot dictatorships, totalitarian dictatorships


In March 1975, Friedman had a 45-minute meeting with Pinochet while he was on a private visit to Chile. Friedman later wrote a letter to that tin-pot military dictator proposing some economic remedies. That advice was the same advice he gave to countries all around the world such as to the government of India in 1955 .
Friedman advocated quick and severe cuts in government spending and inflation, deregulation, a floating exchange rate and more open international trade policy and to
provide for the relief of any cases of real hardship and severe distress among the poorest classes.
Milton Friedman first visited China in 1980. According to Ronald Coase’s book on Chinese economic reform, as part of that visit, Friedman gave a week long seminar to Chinese government officials. Friedman met with the leadership of this totalitarian dictatorship. Friedman returned again as a guest of the Chinese government in 1988 and 1993:
Milton Friedman and his wife Rose visited China in 1980 and 1988 to learn about the economic reform that was taking place there and to share their economic knowledge and insights with the Chinese people.
Friedman gave lectures in numerous cities and held discussions with government officials, managers, bankers, students, professors and even with ordinary people in their homes and on the streets.
In their second visit they met with Zhao Ziyang… General Secretary of the Chinese Communist Party, to discuss China’s economic reform.

In his meetings with the Chinese leaders when he first visited China in 1980, Friedman strongly emphasised
the importance of unfettered markets, pointing to China’s neighbour, Hong Kong, as a model to be followed by mainland China.
Steven Cheung wrote about those visits and the extremely sophisticated discussions Friedman had with top Chinese officials and their economic advisers in 1988 with Cheung as his translator. The only two points they disagreed on was the control that the Communist Party had over the society and when to loosen exchange-rate controls. Cheung said that Zhao’s rationale for delay deserved a good grade in any graduate exam. Following Friedman’s meetings with Zhao, he said the general secretary
was the best economist I have ever met from a socialist country
Subsequent to his 1988 meeting with Zhao Ziyang, Milton Friedman wrote him a letter that gave much the same advice that he gave to Pinochet. Friedman also advised the Chinese against following the market socialism model of Yugoslavia because although it would work for a while before further economic growth required privatisation.
Why is it wrong to have one 45 minute meeting with the tin-pot dictator and yet give seminars and detailed policy advice to a totalitarian dictatorship. Friedman would spend the rest of his life being defamed as an accomplice to evil for meeting Pinochet for 45 minutes. Friedman later noted that he gave communist dictatorships the same advice he gave Pinochet:
It’s curious. I gave exactly the same lectures in China that I gave in Chile. I have had many demonstrations against me for what I said in Chile.
Nobody has made any objections to what I said in China. How come?
If the same standard of evidence is applied to all people who visit dictatorships, Friedman must be a Communist agent or at least a collaborator and responsible for all the horrors that took place in China before and after he visited: the Great Leap Forward and the cultural revolution would be examples. Friedman also visited Yugoslavia: market socialism is his fault as well.

Margaret Thatcher, Hayek & Friedman | Margaret Thatcher Foundation
19 May 2014 Leave a comment
in Austrian economics, F.A. Hayek, macroeconomics, Milton Friedman Tags: credibility, gradualism, Margaret Thatcher, neoliberalism, Thomas Sargent
Thatcher read Hayek’s Road to Serfdom as an undergraduate at Oxford. She took away two key lessons for her life: you cannot compromise with socialism, even the mild social democratic forms; and she saw her own party was doing just that, which put her deeply at odds with its leadership.

After she became Leader of the Opposition, Thatcher cut short a leftish member of her own Conservative Party Research Department by showing him a copy of The Constitution of Liberty, slamming it down on the table declaring “this is what I believe”.
Thatcher’s relationship with Milton Friedman was different to that of Hayek and not as long standing. Friedman met Thatcher for the first time at a dinner in 1978.
After Thatcher came to office in 1979, Friedman was a critic of the monetary regime of the Thatcher government, questioning her monetary policy targets, questioning the raising of the value added tax to finance income tax cuts, and urging deeper spending cuts in the 1979 budget. Friedman was also a strong critic of the monetary policies of the Fed at that time as well, arguing that they lacked credibility, transparency and were very erratic.
In a letter to the Times on 3 March 1980 Friedman stated that he opposed “fine-tuning” and strongly preferred:
a steady monetary and fiscal policy announced long in advance and strictly adhered to
Hayek disagreed with Friedman about the role of gradualism in a letter to the Times on 26 March 1980:
The chief practical issue today is how fast inflation can be and ought to be stopped.
On this, I am afraid, my difference from Friedman makes me take an even more radical position.
The reason is that I believe that the artificial stimulus which inflation gives to business and employment lasts only so long as inflation accelerates, that is, so long as prices turn out to be higher than expected.
Inflation clearly cannot accelerate indefinitely, but as soon as it ceases to accelerate, all the windfalls due to prices turning out higher than expected, which kept unprofitable businesses and employment going, disappear.
Every slowing down of inflation must therefore produce temporary conditions of extensive failures and unemployment.
No inflation has yet been terminated without a “stabilization crisis”.
To advocate that inflation should be slowed down gradually over a period of years is to advocate a long period of protracted misery. No government could stand such a course.
Milton Friedman’s general views on Britain when Thatcher first came to office were clear-cut and were also stated in his letter to the Times on 3 March 1980:
…while monetary restraint is a sufficient condition for controlling inflation, it is a necessary but not sufficient condition for improving Britain’s productivity – the fundamental requirement for restoring Britain to full economic health.
That requires measures on a broader front to restore and improve incentives, promote productive investment, and give a greater scope for private enterprise and initiative.
Both Hayek and Friedman wrote privately about the Thatcher policies of the early 1980s, decrying them as gradualism. So much for the retired professors as the ring masters of neo-liberalism and Thatcher as their pawn.
Friedman and Hayek disagreed with each other, in important respects, about both gradualism in monetary policy and macroeconomics in general.
Thatcher did not follow their conflicting policy advice to her. At best, Thatcher was a wayward disciple of squabbling prophets.
Friedman was a strong critic of Austrian macroeconomics and its supposed role in the 1930s policy response or lack of a response to the Great Depression:
I think the Austrian business-cycle theory has done the world a great deal of harm.
If you go back to the 1930s, which is a key point, here you had the Austrians sitting in London, Hayek and Lionel Robbins, and saying you just have to let the bottom drop out of the world.
You’ve just got to let it cure itself. You can’t do anything about it. You will only make it worse. You have Rothbard saying it was a great mistake not to let the whole banking system collapse.
I think by encouraging that kind of do-nothing policy both in Britain and in the United States, they did harm.
Hayek was equally critical of the macroeconomics of Milton Friedman and his methodology in general:
I do indeed regard the abandonment of the whole macroeconomics nonsense as very important, but it is for me a very delicate matter and I have for some time avoided stating my views too bluntly and would not have time to state them adequately.
The source of the difficulty is the constant danger that the Mont Pelerin society might split into a Friedmanite and a Hayekian wing.
I have long regretted my failure to take time to criticise Friedman’s Positive Economics almost as much as my failure to return to the critique of Keynes General Theory after I had dealt with his Treatiese.
It still seems to me paradoxical that Keynes, who was rather contemptuous of econometrics, should have become the main source of the revival of macroeconomics – which incidentally was also the reason why Milton was for a time a Keynesian.
I believe a good and detailed critical analysis of macroeconomics would be very desirable.
Brad Delong pointed out in 2000 that the New Keynesian macroeconomic research program was developed in the 20th century monetarist tradition mostly in the work of Milton Friedman.
Tom Sargent argued in 1981 that Thatcher’s medium term economic strategy was gradualism, and the sustained budget deficits would result in unpleasant monetarist arithmetic:
…In order that the current British plan be viewed as credible it is necessary that the large prospective government deficits over the next several years be counterbalanced by prospective surpluses further down the line.
It is difficult to point to much either in current legislation, or equally importantly, in the general British political climate that could objectively support such an outlook.
…Gradualism invites speculation about future reversals with U-turns in policy.
Large contemporary government deficits unaccompanied by concrete prospects for future government surpluses promote realistic doubts about whether monetary restraint must be abandoned sooner or later to help finance the deficits.
Such doubts not only call into question the likelihood that the plan can successfully permanently reduce inflation, but also can induce high real cost in terms of depressed industry and lengthened unemployment in response to what may be viewed as only temporary downward movements in nominal aggregate demand that the monetary restraint induces.
What did Thatcher actually do?
by discrediting socialism so thoroughly, she prompted in due course the adoption by the Labour Party of free market economics, and so, as she wryly confessed in later years, “helped to make it electable”.
The archives of the Margaret Thatcher foundation has released extensive correspondence and other documents about Thatcher, Hayek and Friedman.
The end of the great inflation in Australia in 1990 was a policy accident
02 May 2014 Leave a comment
in macroeconomics, Milton Friedman, politics - Australia Tags: current account deficits, inflation, monetary policy
No one under 40 has an adult memory of inflation in Australia. They have forgotten what high inflation was like.

Those older than 40 have forgotten how inflation was tamed.
Edward Nelson’s paper ‘Monetary policy neglect and the Great Inflation in Canada, Australia, and New Zealand‘ is good on this. His paper trawls through the press reports of the 1970s onwards to document exactly what the views of the day were of the causes of inflation:
- Policy-makers at least from 1971 viewed inflation as resulting from factors beyond their control, not as a consequence of their monetary policy decisions;
- Policy-makers embraced non-monetary approaches against inflation in a manner that defied political classification; and
- Highly interventionist strategies of compulsory wage and price controls was adopted by the traditionally more anti-interventionist of the major political parties;
The Governments and Reserve Bank of the 1970s and 1980s attributed the double-digit inflation of that time to a range of causes other than loose monetary policy.
1988 witnessed a major monetary policy tightening in Australia.
The tightening itself was motivated by balance-of-payments rather than inflation considerations. It was that old bogey, the current account deficit. The current account is the most pernicious statistic published.
The fall in inflation to 3% in 1991 transformed the views of policymakers and observers about the role of monetary policy in inflation control.
As late as 1990, the Governor of the Reserve Bank rejected central-bank inflation targeting as infeasible in Australia, and cited the need to use other tools such as wages policy.
When inflation fell below 3% in early 1991—clearly a response to the period of monetary restraint – I can assure you that none of the briefings to ministers at that time forecasted inflation to fall so rapidly.
Policy attitudes changed all through brute experience; no neo-liberal conspiracies here. Milton Friedman was still a swear word back then and the idea that inflation was a monetary phenomenon was still career limiting.
Gruen and Stevens (2000) record that in the 1990s, “the main insight of two centuries of monetary economics… that monetary policy ultimately determined inflation” convinced the authorities that non-monetary approaches to inflation control should be abandoned in favour of central-bank inflation targeting.
The current account did not change much as a result of the deep recession designed to bring it under control. The current account deficit as a major policy problem was quietly forgotten.
You’re an ideologue; no, you’re the ideologue!
30 Apr 2014 Leave a comment
in applied welfare economics, constitutional political economy, economics, Milton Friedman Tags: Alan Blinder, critical discussion, honest disagreement, Karl Popper, Lester Thurow, Milton Friedman, Peter Drucker, William Baumol
I find that people who call out other people and opposing analysis as ideological are themselves ideologues. They cannot see political differences as other than ideological cat fights.

This is rather than an honest difference of opinion over the effectiveness of different options to achieve a common end as Milton Friedman explained:
I venture the judgment, however, that currently in the Western world, and especially in the United States, differences about economic policy among disinterested citizens derive predominantly from different predictions about the economic consequences of taking action – differences that in principle can be eliminated by the progress of positive economics – rather than from fundamental differences in basic values, differences about which men can ultimately only fight.
Hayek attributed to his opponents nothing more than intellectual error. Hayek (1948) believed that:
we must recognize that it may be genuine error which leads the well-meaning and intelligent people who occupy those key positions in our society to spread views which to us appear a threat to our civilization. Nothing could be more important than to try to understand the sources of this error in order that we should be able to counter it.
Hayek (1968) continues:
The worst mistake a fighter for our ideals can make is to ascribe to our opponents dishonest or immoral aims. I know it is sometimes difficult not to be irritated into a feeling that most of them are a bunch of irresponsible demagogues who ought to know better…
we ought to realize that their conceptions derive from serious thinkers whose ultimate ideals are not so very different from our own and with whom we differ not so much on ultimate values, but on the effective means of achieving them.
William Baumol and Alan Blinder described the role of economics in policy debates as follows:
While economic science can contribute the best theoretical and factual knowledge there is on a particular issue, the final decision on policy questions often rests either on information that is not currently available or on tastes and ethical opinions about which people differ (the things we call ‘value judgments’), or on both.
Lester Thurow said that differences in the valuation of outcomes is at the basis of most disagreements:
Liberal and conservative economists most frequently disagree on who ought to be hurt and who ought to be helped. Their technical disagreements on who will be hurt and who will be helped are much less frequent.
Karl Popper argued that who made an argument is of little value. He said that the growth of knowledge depended not on the ethics of the individual scientists but on the critical spirit to scientific community as a whole. The critical scrutiny of others polices the truth:
The genuine rationalist does not think that he or anyone else is in possession of the truth; nor does he think that mere criticism as such helps us achieve new ideas.
But he does think that, in the sphere of ideas, only critical discussion can help us sort the wheat from the chaff.
He is well aware that acceptance or rejection of an idea is never a purely rational matter; but he thinks that only critical discussion can give us the maturity to see an idea from more and more sides and to make a correct judgement of it.
Peter Drucker championed a business rule of never making a decision until there is disagreement; only then do you know what you are planning to do:
Unless one has considered alternatives, one has a closed mind.
This above all, explains why effective decision-makers deliberately disregard the second major command of the textbooks on decision-making and create dissension and disagreement, rather than consensus.
Decisions of the kind the executive has to make are not made well by acclamation.
They are made well only if based on the clash of conflicting views, the dialogue between different points of view, the choice between different judgments.
The first rule in decision-making is that one does not make a decision unless there is disagreement
Alfred P. Sloan said at a meeting of one of his top management committees:
“Gentlemen, I take it we are all in complete agreement on the decision here.” Everyone around the table nodded assent.
“Then,”continued Sloan, “I propose we postpone further discussion of this matter until our next meeting to give ourselves time to develop disagreement and perhaps gain some understanding of what the decision is all about”.
The Great Liberator – Larry Summer’s Obituary for Milton Friedman
30 Apr 2014 Leave a comment
in economics, liberalism, Milton Friedman

Milton Friedman explains Director’s Law of of Public Expenditure
29 Apr 2014 Leave a comment
in Milton Friedman, Public Choice Tags: Aaron Director
Milton Friedman – links to all of his on-line papers, filmed and taped lectures, TV shows and TV interviews
19 Apr 2014 Leave a comment
see Rose and Milton Friedman at the Hoover Institution for everything on-line in every possible modern and old fashioned media format. For example, if you missed it, watch his ten-part television series Free to Choose and his 46-minute appearance on the Phil Donahue Show

The web page is hard to find through Google unless you know it is already there. Just managed to remembered that it was at the Hoover Institution.
Macroeconomic forecasting has had a turbulent history
16 Apr 2014 Leave a comment
in global financial crisis (GFC), great recession, macroeconomics, Milton Friedman Tags: data mining, Edward Leamer, forecasting, lags on monetary policy
Most early discussions argued against econometric forecasting in principle:
- Forecasting was not properly grounded in statistical theory,
- It presupposed that causation implies predictability, and
- The forecasts themselves were invalidated by the reactions of economic agents to them.
A long tradition argued that social relationships were too complex, too multifarious and too infected with capricious human choices to generate enduring, stable relationships that could be estimated.
These objections came before Hayek’s point that much of all social knowledge is not capable of summation in statistics or even language.
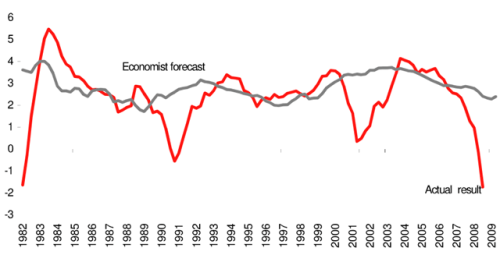
The limitations of forecasting are well-known. Forecasts are conditional on a number of variables; there are important unresolved analytical differences about the operation of the economy; and large uncertainties about the size and timing of responses to macroeconomic changes. Shocks to the output, prices, employment and other variables are partly permanent and partly transitory.
At the practical level, forecasting requires that there are regularities on which to base models, such regularities are informative about the future and these regularities are encapsulated in the selected forecasting model.
We have very little reliable information about the distribution of shocks or about how the distributions change over time. Forecast errors arise from changes in the parameters in the model, mis-specification of the model, estimation uncertainty, mis-measurement of the initial conditions and error accumulation.
In the 1980s, data mining and publications bias were so strong and statistical inferences were so fragile that Ed Leamer’s 1983 Let’s Take the Con out of Econometrics paper made up-and-coming applied economists despair for their professional field and for their own careers:
The econometric art as it is practiced at the computer terminal involves fitting many, perhaps thousands, of statistical models. One or several that the researcher finds pleasing are selected for reporting purposes.
This search for a model is often well intentioned, but there can be no doubt that such a specification search invalidates the traditional theories of inference….
[A]ll the concepts of traditional theory…utterly lose their meaning by the time an applied researcher pulls from the bramble of computer output the one thorn of a model he likes best, the one he chooses to portray as a rose.
… This is a sad and decidedly unscientific state of affairs we find ourselves in.
Hardly anyone takes data analyses seriously.
Or perhaps more accurately, hardly anyone takes anyone else’s data analyses seriously.
Like elaborately plumed birds who have long since lost the ability to procreate but not the desire, we preen and strut and display our t-values [which measure statistical significance].
Leamer still doubts the progress towards techniques that separate sturdy from fragile inferences. Economists by and large simply do not want to hear that they cannot make major conclusions from the data sets. But not that they really do, but that is for a forthcoming post.
Before the great moderation spread wide, Brunner and Meltzer found that in the 1970s and 1980s, the 95% confidence intervals on next year’s forecasts for Gross Domestic Product and the Consumer Price Index are such that government and private forecasters in the USA and Europe could not distinguish between a recession and a boom, nor say whether inflation will be zero or ten per cent.
A review this week by Ahir and Lounganishows found that recent forecasting by the private and public sector has not improved:
none of the 62 recessions in 2008–09 was predicted as the previous year was drawing to a close.
Figure 1. Number of recessions predicted by September of the previous year

Source: Ahir and Loungani 2014, “There will be growth in the spring”: How well do economists predict turning points?” http://www.voxeu.org/
A policy-maker who adjusts policy based on forecasts for the following year has little reason to be confident that he has changed policy in the right direction.
While at graduate school, I wrote what was published as Official Economic Forecasting Errors in Australia 1983-96.
Australian Treasury forecasting errors were so large relative to the mean annual rate of change in real GDP and the inflation rate that, on average, forecasters could not distinguish slow growth from a deep recession or stable prices from moderate inflation.
The biography of Paul Keating by Edwards suggested that the Government of the day was well aware of the poor value of forecasts. So much so that forecasts may not have actually played a significant role in monetary policy making in Australia in the late 1980s onwards. John Stone said this to Keating when he assumed office as Treasurer in 1983:
As you know, we (and I in particular) have never had much faith in forecasting.
Not infrequently, our forecasts turn out to be seriously wrong.
… We simply do the best we can, in as professional manner as we can — and, if it is any consolation, no one seems to be able to do any better, at least in the long haul.
We always emphasize the uncertainties that attach to the forecasts — but we cannot ensure that such qualifications are heeded and plainly they often are not
To cast my results in Milton Friedman’s nomenclature for monetary lags, the recognition lag on a forecasting based monetary policy appears to be infinite because forecasters do not know if there will be a recession or 10% inflation afoot when their monetary policy changes take hold in 18 to 24 months.


Recent Comments