@GreenpeaceUSA @Oxfam some people are just never happy
02 Feb 2016 Leave a comment
in development economics, economic history, growth miracles
Review of #TheBigShort including of the movie
02 Feb 2016 Leave a comment
in applied price theory, business cycles, economic history, entrepreneurship, financial economics, global financial crisis (GFC), great recession, macroeconomics, monetary economics, movies Tags: bank runs, financial crises
About the only time the Hollywood Left oozes with patriotism is when getting stuck into Wall Street. Hollywood must get its revenge for all those times investors did not back their film pitches, trimmed budgets and get the lion’s share of merchandising royalties and syndication profits. As Larry Ribstein explained:
American films have long presented a negative view of business…. it is not business that filmmakers dislike, but rather the control of firms by profit-maximizing capitalists… this dislike stems from filmmakers’ resentment of capitalists’ constraints on their artistic vision.
The Big Short is still a good film despite the left-wing populism, worth going to see. Its limitations in not discussing the monetary policy of The Fed or regulations that encouraged lending to high risk borrowers are justified poetic license and editing.
The film is already 120+ minutes long despite frequent resorts to breaking the fourth wall to explain technical terms, who was what and what they were doing, past and present. The Big Short is a film designed it make money at the box office, not a semester long documentary.
The Big Short is well acted, funny, insightful and still a good story despite the documentary element that was impossible to do without.
The Big Short highlights that its protagonists had skin in the game. They were investing in mortgages or shorting the same in the expectation of a crash. There were no windbags and armchair critics in The Big Short talking gloom and doom on the horizon without investing their own money to profit from their forecasts. That said, the protagonists betting on a sub-prime mortgages crash, bar two of them, were a little bit nutty.
I do not know any of the critics of the economics of the film’s explanation of the sub-prime crisis who suggested how they could fix these gaps in its economics without making the film much, much longer.
These critics fall into the exact same trap that the Big Short was not about. The Big Short was about investors to put their money where their mouth is. The critics of the film should put their script doctoring skills where their mouths are at least of The Big Short.
Source: What ‘The Big Short’ Gets Right, and Wrong, About the Housing Bubble – The New York Times.
Getting stuck into the role of the Fed and regulatory mandates on the banks regarding their level of sub-prime mortgages is for another film. Plenty of people warned of dark days ahead. An essay anyone can read with profit is Ross Levine’s “An Autopsy of the U.S. Financial System: Accident, Suicide, or Negligent Homicide?“
Other films, correctly documentaries, place the blame for the sub-prime crisis and the Great Recession directly on the Fed:
The financial mess we’re still climbing out of can be laid directly at the feet of the Fed, whose misguided advocacy, under Greenspan, of a borrow-and-spend economy rather than a focus on savings and investment has created a situation where, as the title implies, money is disconnected from any underlying value.
There are plenty of points that could be added to the economics of The Big Short if it was a film of more or less unlimited length:
Krugman and friends like the film because it leaves out any discussion of the main culprit behind the financial crisis, which was not Wall Street “greed” but bad monetary and credit policies from the Federal Reserve and the federal government. The movie barely hints at any exogenous factors behind the boom or bust. (This FEE report by Peter Boettke and Steven Horwitz fills in the missing information.) So the pro-regulation crowd is cheering. Viewers are given no understanding of the real causal factors and hence fill in the missing data with a feeling that banks just love ripping people off. To be sure, if you approach this movie with some knowledge of economics and monetary policy, the rest of the narrative makes sense. Of course Wall Street got it wrong, given Washington’s policies on mortgage lending!
To add to the brew, Edward Prescott points out the Great Recession can be explained through productivity shocks. Specifically, a collapse in investment and in particular investment in intangibles such as intellectual property in 2007 in anticipation of more taxes and more regulation.
The Great Recession had many of the same features of the 1990s technology boom but in reverse. The boom in the 1990s and bust in 2007 were somewhat inexplicable because major sources of volatility were unmeasured, specifically, investment in intangible capital.
V.V. Chari also points out that the extent of the financial crisis was overstated. This is because the typical firm can finance its capital expenditures from retained earnings so it was hard to see how financial market disruptions could directly affect investment.
What Chari disputed was that bank lending to non-financial corporations and individuals has declined sharply, that interbank lending is essentially non-existent; and commercial paper issuance by non-financial corporations declined sharply, and rates have risen to unprecedented levels.
John Taylor argues that we should consider macroeconomic performance since the 1960: There was a move toward more discretionary policies in the 1960s and 1970s; A move to more rules-based policies in the 1980s and 1990s; and back again toward discretion in recent years.
These policy swings are correlated with economic performance—unemployment, inflation, economic and financial stability, the frequency and depths of recessions, the length and strength of recoveries. Less predictable, more interventionist, and more fine-tuning type macroeconomic policies have caused, deepened and prolonged the current recession. Robert Hetzel puts it this way:
The alternative explanation offered here for the intensification of the recession emphasizes propagation of the original real shocks through contractionary monetary policy. The intensification of the recession followed the pattern of recessions in the stop-go period of the late 1960s and 1970s, in which the Fed introduced cyclical inertia in the funds relative to changes in economic activity.
Finn Kydland considers fiscal policy to be at the heart of the slow recovery. Instead of restructuring and investing more prudently, Western countries faced with budget shortfalls will seek to increase taxes:
- The U.S. economy isn’t recovering from the Great Recession of 2008-2009 with the anticipated strength.
- A widespread conjecture is that this weakness can be traced to perceptions of an imminent switch to a regime of higher taxes.
- The fiscal sentiment hypothesis can account for a significant fraction of the decline in investment and labor supply in the aftermath of the Great Recession, relative to their pre-recession trends.
- The perceived higher taxes must fall almost exclusively on capital income. People must suspect that the tax structure that will be implemented to address large fiscal imbalances will be far from optimal.
Now imagine trying to incorporate all the above points into a film and keeping it at its current two-hour length?
Remember these canteen prices?
02 Feb 2016 Leave a comment
in economic history, economics of media and culture Tags: good old days
From 1950, Japan doubled their standard of living every 8 years
02 Feb 2016 Leave a comment
in development economics, economic history, growth miracles Tags: East Asian Tigers, Japan
NZ households spending 30% plus of disposable income on housing, 1988–2013
01 Feb 2016 Leave a comment
in economic history, economics of regulation, urban economics
The importance of correctly measuring income growth over the decades
31 Jan 2016 Leave a comment
in applied welfare economics, economic history Tags: measurement error
US, UK Australian and New Zealand measles vaccination rates since 1980
31 Jan 2016 Leave a comment
in economic history, health economics Tags: measles, vaccinations, vaccines
The USA led the way in measles vaccinations. Herd immunity is a 93% vaccination rate. Countries have been coming close to measles immunity immunity only in recent years.
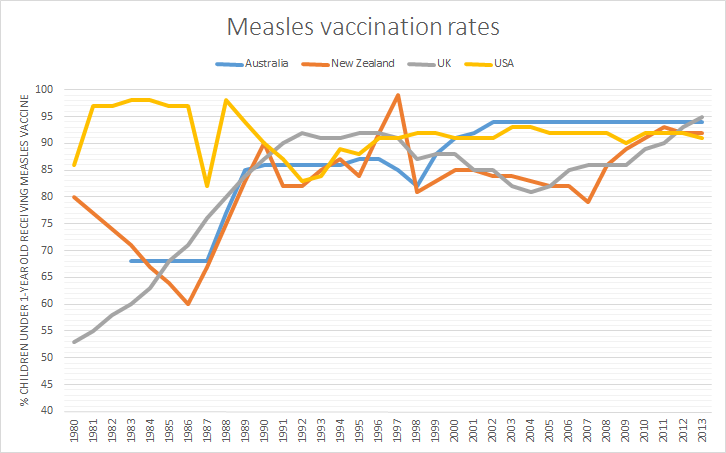
Source: OECD Health Statistics.
@TrevorMallard what next for #TPPANoWay? Repeal CER?
31 Jan 2016 Leave a comment
in economic history, international economics, International law, law and economics, politics - Australia, politics - New Zealand, Public Choice, television, TV shows Tags: CER, closer economic relations, Hollywood economics, ISDS, preferential trading agreements, rational irrationality, single market, TPPA, Twitter left
New Zealand filmmakers have used trade treaties to pry open access to foreign markets by challenging failures to honour promises of nondiscrimination in trade and investment in the Federal Court of Australia.
This should please the Twitter Left because they are also a film going left as are most members of the educated middle class as a point of identity and snobbery.
Back in the day, New Zealand television programming was sold cheaply into the Australian market. Many cultural and other products are exported into foreign markets and sold for whatever they can get above the price of shipping or digital transmission. What else explains all that rubbish on cable TV?
Under the Closer Economic Relations agreement that creates a single market between Australia and New Zealand, New Zealand made television programming content must be treated the same way as Australian content so it was included in their 50% local content rules for commercial television back from whenever I remember this story from.
There was a Federal Court of Australia case that ruled that New Zealand television programming was Australian content programming for the purposes of the relevant media regulations because of Closer Economic Relations.
From the late 1990s, with revival of the New Zealand film and television industry, New Zealand content was starting to flood the Australian market, especially in the off-season in the summer when stations were looking for cheap content to fill a low ratings period.
Naturally, this Kiwi invasion did not please the rent seeking Australian television programme production industry and many a mendicant actor, writer and producer
Where there is a will, where there is a way: minimum quality standards are introduced into the Australian content rules defined by price – a price that happen to be above what the television stations used to pay for New Zealand made programming in the off-season.
This court victory in favour of various New Zealand film industry in enforcing a trade and investment treaty puts the Twitter left in a bit of a conundrum. Which is more important? The New Zealand film industry or their hatred of globalisation and the rule of law.
Unions are not the cause of our 40 hour workweek
31 Jan 2016 Leave a comment
in applied price theory, applied welfare economics, economic history, labour economics, labour supply, unions Tags: 40 hour week, hours worked, living standards, union power, union wage premium, working hours, working week
% of American children living with a single parent
31 Jan 2016 Leave a comment
in economic history, economics, economics of love and marriage, gender, labour economics, labour supply, population economics
Share market losses during previous financial crises in the USA and UK
31 Jan 2016 Leave a comment
in business cycles, economic history, fisheries economics, global financial crisis (GFC), great depression, great recession, macroeconomics Tags: banking crises, financial crises, sovereign debt crises, sovereign defaults
Indirect taxes as % of US, UK, Danish, Australian and New Zealand GDPs
30 Jan 2016 Leave a comment
in economic history, fiscal policy, public economics
There are big differences between the USA, between the USA and Australia and the rest with a mild exception for the UK.
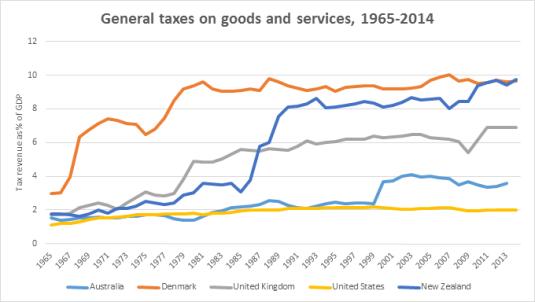
Data extracted on 30 Jan 2016 03:05 UTC (GMT) from OECD.Stat.


Recent Comments