The new reserve bank governor was talking about how rising wages may increase inflation. The horror, the horror!
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
15 May 2018 1 Comment
in business cycles, macroeconomics, Milton Friedman, monetarism, monetary economics Tags: cost-push
The new reserve bank governor was talking about how rising wages may increase inflation. The horror, the horror!
11 Aug 2017 Leave a comment
in business cycles, economics, inflation targeting, macroeconomics, monetarism, monetary economics Tags: monetary policy
24 May 2017 1 Comment
in business cycles, economic history, great depression, macroeconomics, monetarism, monetary economics
15 Oct 2016 Leave a comment
in economic history, fiscal policy, great depression, history of economic thought, macroeconomics, Milton Friedman, monetarism, monetary economics Tags: fiscal stimulus
30 Sep 2016 Leave a comment
in business cycles, economic growth, macroeconomics, Milton Friedman, monetarism, monetary economics, politics - Australia Tags: central banks, conspiracy theories, lags on monetary policy, monetary policy, rules versus discretion, The fatal conceit, The pretense to knowledge
Milton Friedman visited Australia in 1975. He spoke with government officials and appeared on the TV show Monday Conference. Apparently, that was enough for him to take over Australian monetary policy setting for the foreseeable future.
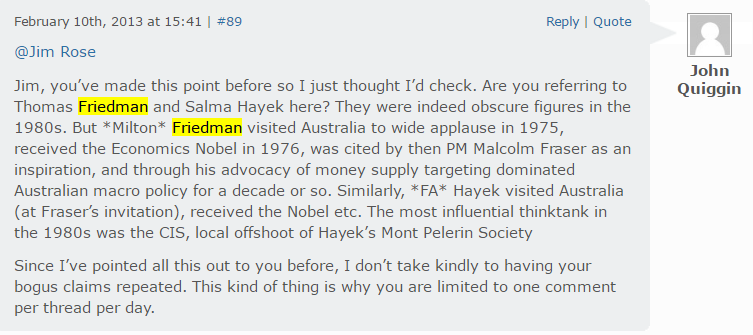
When working at the next desk to the monetary policy section in the late 1980s, I heard not a word of Friedman’s Svengali influence:
See Ed Nelson’s (2005) Monetary Policy Neglect and the Great Inflation in Canada, Australia, and New Zealand who used contemporary news reports from 1970 to the early 1990s to uncover what was and was not ruling monetary policy. For example:
“As late as 1990, the governor of the Reserve Bank rejected central-bank inflation targeting as infeasible in Australia, and cited the need for other tools such as wages policy (AFR, October 18, 1990).”
Bernie Fraser was still sufficiently deprogrammed in 1993 to say that “…I am rather wary of inflation targets.” Easy to then announce one in the same speech when inflation was already 2-3%.
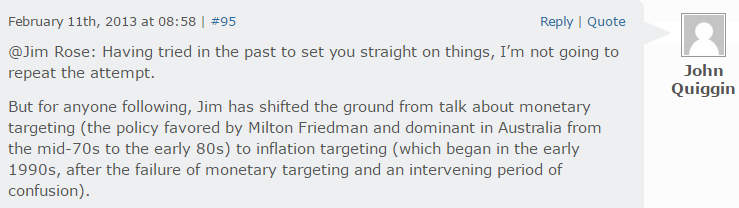
When as a commentator on a Treasury seminar paper in 1986, Peter Boxhall – fresh from the US and 1970s Chicago educated – suggested using monetary policy to reduce the inflation rate quickly to zero, David Morgan and Chris Higgins almost fell off their chairs. They had never heard of such radical ideas.
In their breathless protestations, neither were sufficiently in-tune with their Keynesian educations to remember the role of sticky wages or even the need for the monetary growth reductions to be gradual and, more importantly, credible as per Milton Freidman and as per Tom Sargent’s End of 4 big and two moderate inflations papers.
I was far too junior to point to this gap in their analytical memories about the role of sticky wages, and I was having far too much fun watching the intellectual cream of the Treasury senior management in full flight. At a much later meeting, another high flying deputy secretary was mystified as to why 18% mortgage rates were not reining in the current account in 1989.
Friedman’s Svengali influence did not extend to brainwashing in the monetarist creed that the lags on monetary policy were long and variable. The 1988 or 1989 budget papers put the lag on monetary policy at 1 year, which is short and rapier, if you ask me.
27 Sep 2016 3 Comments
in business cycles, economic history, macroeconomics, monetarism, monetary economics, politics - Australia Tags: central banks, monetary policy, The Great Inflation
Australian policymakers from at least 1971 viewed inflation as not a consequence of their monetary policy decisions. There were repeated references by them to wage-price spirals and both unsuccessful (1977) and successful attempts (1981) at wage freezes.
The prices and incomes accord from 1983 onwards was just another 1970s wage tax trade-off. An Incomes policy attributes inflation to non-monetary factors, as did Fraser and Lynch regularly.
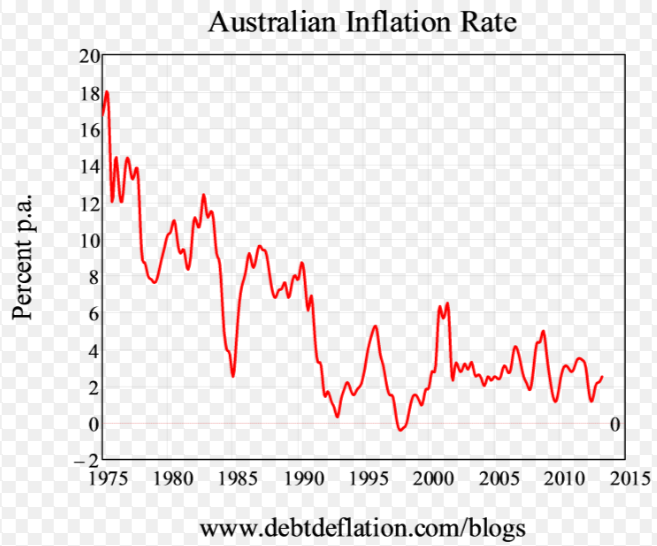
• It was not until 1980 that the Fraser government’s monetary policy became genuinely anti-inflationary. With a lag, these changes halved inflation to the mid-single digits by 1983. The implementation lag on the 1975 Monday conference programme must have been long and variable and lasted for a three year window!? Three years out of 20 is hardly a monetarist hegemony!
• Australia had lower CPI inflation in the 1980s than the 1970s, but this was marred by rebounds in 1985–86 and 1988–90 to near 9%.
The monetary policy regime change in the late 1980s was triggered by factors besides rising inflation: a demonic view of currant account.
After several years of high interest rates, the budget papers forecasted a moderate slowing:
• The budget GDP forecast for 1990-91 was 2% with an actual of minus 0.4%; for inflation the actual and forecast were 5.3% versus 6.5%; 1989-90 inflation rate was 8% with GDP growth of 3.3%.
• In 1991-92, the budget GDP forecast was 1.5% with an actual of 2.1%; for inflation the actual and forecast were 1.9% versus 3.8%.
• In 1992-93, the budget papers forecast for inflation 3% for an actual of 1%.
• In 1993-94, the budget forecast for inflation 3.5% for an actual of 1.8%.
The monetarists in the Treasury, entranced as they were by Friedman’s 1975 visit, still had not clicked to the link between a tight monetary policy and low inflation as late as 1993. Australia pursued a stop-go monetary policy from 1971 to the early 1990s.
I worked in the next desk to the monetary policy section in the Prime Minister’s Department in the 1980s. They were determined that market set interest rates, not monetary policy.
I suggest you read the biography of keating by john edwards(?) – his economic advisor in the late 1980s.
Edwards quotes from numerous Treasury briefings to Keating. the Treasury remembered their Keynesian educations well, as did those at DPMC. the prices and incomes accord was very Keynesian: inflation as a non-monetary phenomenon
Mentioning Friedman’s name in the 1980s at job interviews would have been extremely career limiting. Not much better in the early 1990s. Back in the late 1980s, Friedman was graduating from ‘a wild man in the wings’ to just a suspicious character in policy circles.
If you name dropped Hayek in the 1980s and 1990s, any sign of name recognition would have indicated that you were been interviewed by people who were very widely read.
25 Jun 2016 Leave a comment
in business cycles, economics, F.A. Hayek, macroeconomics, Milton Friedman, monetarism, monetary economics
28 May 2016 Leave a comment
in business cycles, F.A. Hayek, history of economic thought, macroeconomics, Milton Friedman, monetarism, monetary economics Tags: Keynesian macroeconomics
24 May 2016 1 Comment
in macroeconomics, Milton Friedman, monetarism, monetary economics Tags: American Civil War, inflation
04 Feb 2016 Leave a comment
in business cycles, currency unions, Euro crisis, global financial crisis (GFC), great recession, inflation targeting, macroeconomics, monetarism, monetary economics Tags: central banks, liquidity trap, monetary policy
03 Nov 2015 Leave a comment
in economic history, macroeconomics, monetarism, monetary economics Tags: forecasting errors, Paul Krugman, public intellectuals
03 Oct 2015 Leave a comment
in business cycles, macroeconomics, monetarism, monetary economics, politics - USA Tags: central banks, economics of central banking, monetary policy, rules and discretion, Taylor rule, The Fed
Yellen vs. Congress: The Fed's independence is under attack despite economic rebound bloom.bg/1HM9c0A http://t.co/NQ6548yGJK—
Bloomberg VisualData (@BBGVisualData) August 10, 2015
17 Sep 2015 1 Comment
in business cycles, history of economic thought, inflation targeting, macroeconomics, managerial economics, monetarism, monetary economics, organisational economics Tags: Alan Blinder, Alan Greenspan, credible commitments, Greg Mankiw, modern macroeconomics, monetary policy, neo-Keynesian macroeconomics, new classical macroeconomics, The Fed, timing inconsistency
Two of my brothers studied economics in the early 1970s and then went on to different paths in law and computing respectively. If Greg Mankiw is right, my two older brothers could happily conduct a conversation with a modern central banker. Their 1970s macroeconomics, albeit batting for memory, would be enough for them to hold their own.
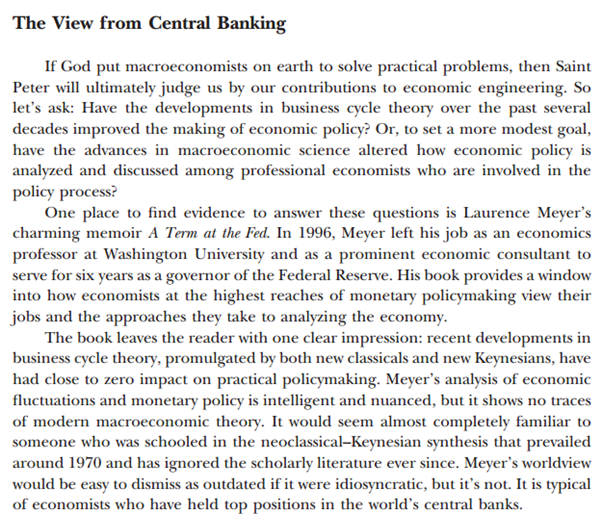
Source: AEAweb: JEP (20,4) p. 29 – The Macroeconomist as Scientist and Engineer – Greg Mankiw (2006).
I would spend my time arguing with a central banker that Milton Friedman may be right and central banks should be replaced with a computer. The success of inflation targeting is forcing me to think more deeply about that position. In particular the rise of pension fund socialism means that most voters are very adverse to inflation because of their retirement savings and that is before you consider housing costs are much largest proportions of household budgets these days.
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
A History of the Alt-Right
Econ Prof at George Mason University, Economic Historian, Québécois
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Scholarly commentary on law, economics, and more
Beatrice Cherrier's blog
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
A rural perspective with a blue tint by Ele Ludemann
DPF's Kiwiblog - Fomenting Happy Mischief since 2003
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
The world's most viewed site on global warming and climate change
Tim Harding's writings on rationality, informal logic and skepticism
A window into Doc Freiberger's library
Let's examine hard decisions!
Commentary on monetary policy in the spirit of R. G. Hawtrey
Thoughts on public policy and the media
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Politics and the economy
A blog (primarily) on Canadian and Commonwealth political history and institutions
Reading between the lines, and underneath the hype.
Economics, and such stuff as dreams are made on
"The British constitution has always been puzzling, and always will be." --Queen Elizabeth II
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
WORLD WAR II, MUSIC, HISTORY, HOLOCAUST
Undisciplined scholar, recovering academic
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Res ipsa loquitur - The thing itself speaks
In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”
Researching the House of Commons, 1832-1868
Articles and research from the History of Parliament Trust
Reflections on books and art
Posts on the History of Law, Crime, and Justice
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Exploring the Monarchs of Europe
Cutting edge science you can dice with
Small Steps Toward A Much Better World
“We do not believe any group of men adequate enough or wise enough to operate without scrutiny or without criticism. We know that the only way to avoid error is to detect it, that the only way to detect it is to be free to inquire. We know that in secrecy error undetected will flourish and subvert”. - J Robert Oppenheimer.


 Utopia, you are standing in it!

Recent Comments