Lunch and Conversation with Thomas J. Sargent
18 Mar 2016 Leave a comment
in economic growth, economics, Euro crisis, fiscal policy, global financial crisis (GFC), great recession, job search and matching, macroeconomics, monetary economics, Public Choice Tags: Thomas Sargent
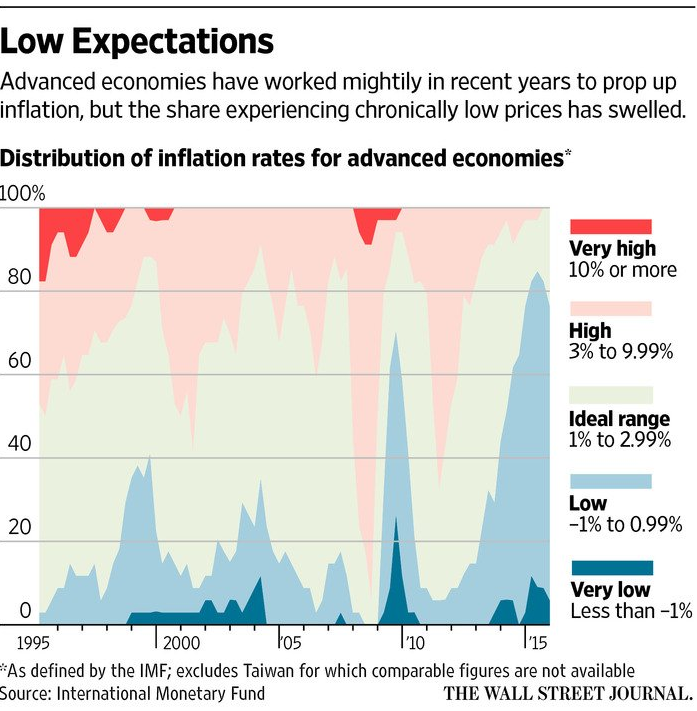
There is not a lot of inflation out there
17 Mar 2016 Leave a comment
in macroeconomics, monetary economics Tags: deflation, inflation rate, liquidity trap, monetary policy
.
% of New Zealand mortgages that were fixed and floating since 2004
16 Mar 2016 Leave a comment
in economic history, economics of information, economics of regulation, monetary economics, politics - USA Tags: antimarket bias, libertarian paternalism, monetary policy, mortgage interest rates, New Zealand Labour Party, Other people are stupid fallacy, rational irrationality, The fatal conceit, The pretence to knowledge
Despite the best efforts of the libertarian paternalists to sell the other people are stupid fallacy, ordinary New Zealanders are quite nimble at moving between fixed and floating rates depending upon their forecasts of the future of interest rates. Price controls on floating rate mortgages, as suggested by the New Zealand Labour Party, would make this more difficult, not easier.
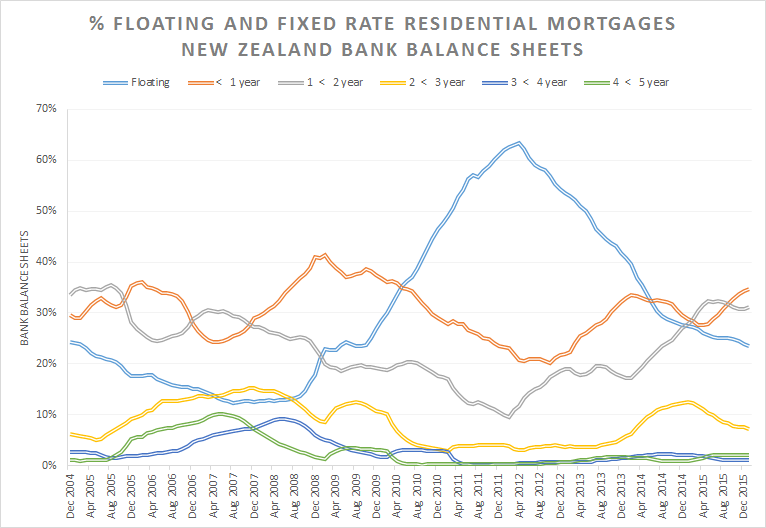
Source: S8 Banks: Mortgage lending ($m) – Reserve Bank of New Zealand.
Percentage of fixed and floating mortgages in New Zealand
16 Mar 2016 Leave a comment
in economics of regulation, industrial organisation, monetary economics, politics - New Zealand Tags: antimarket bias, mortgage interest rates, New Zealand Greens, New Zealand Labour Party, price controls, rational irrationality
I did not know so many people were on a fixed rate mortgage. Labour is risking its economic credibility on regulating the rates for a minority of mortgages.

Source: S8 Banks: Mortgage lending ($m) – Reserve Bank of New Zealand.
Capped mortgages cannot be linked to the current official cash rate of the Reserve Bank of New Zealand because they are based on expected future interest rates over an up to 5 year span, not current interest rates.
An important motivation for going onto a floating rate is you can repay faster. Fixed rate mortgages have penalties for early repayment.

Source: Price Controls: Price Floors and Ceilings, Illustrated.
In consequence, price controls linking floating rate mortgages to the official cash rate of the Reserve Bank would benefit better off mortgagees expecting to repay quickly. A typical policy of the modern Labour Party.
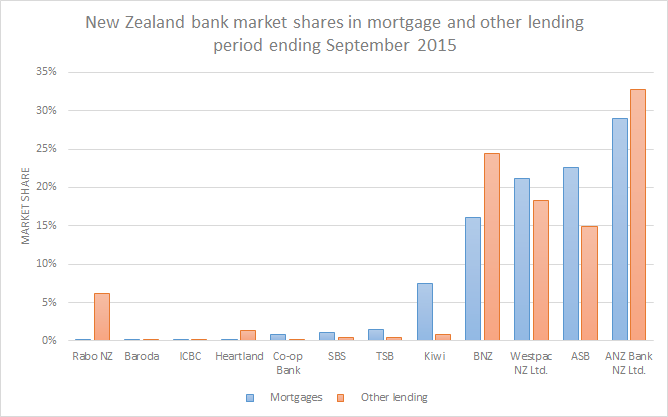
New Zealand bank market shares in mortgage and other lending, 2015
15 Mar 2016 Leave a comment
in financial economics, industrial organisation, law and economics, monetary economics, politics - New Zealand Tags: competition law, competition policy, economics of banking, state owned enterprises
New Zealand Post (incl. Kiwibank) dividends
15 Mar 2016 Leave a comment
in industrial organisation, monetary economics, politics - USA, public economics Tags: economics of banking, government ownership, KiwiBank, network industries, New Zealand Greens, New Zealand Post, rational irrationality, state owned enterprises
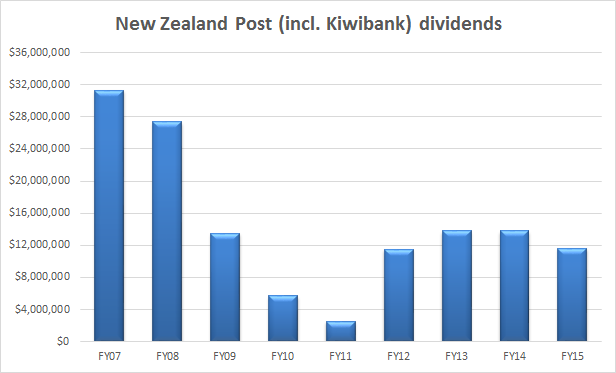
Source: New Zealand Treasury – data released under the Official Information Act.
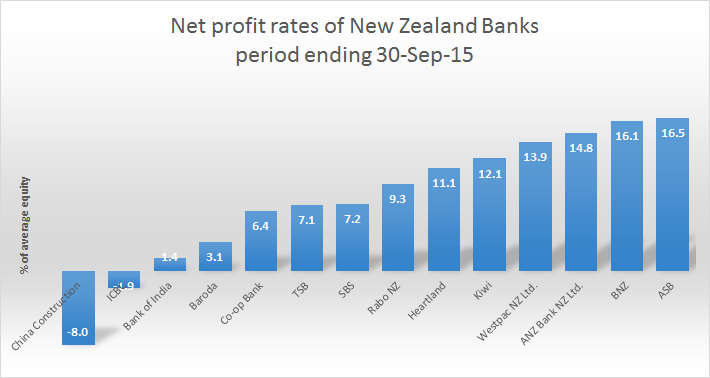
Profit rates of New Zealand banks, 2015
15 Mar 2016 Leave a comment
in industrial organisation, law and economics, monetary economics, politics - New Zealand, survivor principle Tags: competition law, competition policy, economics of banking, state owned enterprises
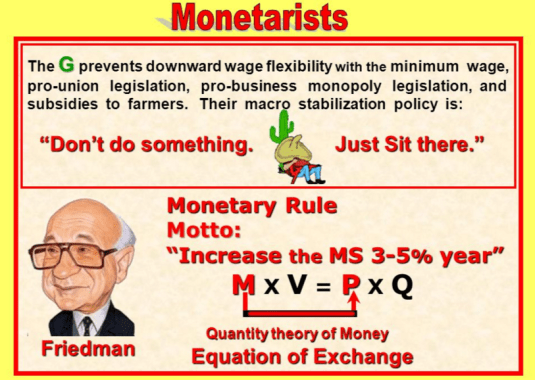
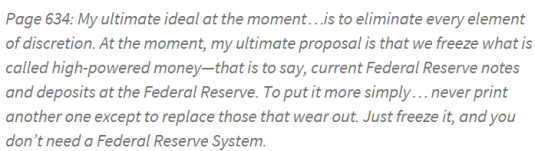
Peter Lyons does not know what monetarism is – the antithesis of discretion, fine tuning
11 Mar 2016 Leave a comment
in history of economic thought, macroeconomics, Milton Friedman, monetary economics Tags: monetary rules, rules versus discretion
Peter Lyons teaches Economics at St Peter’s College in Epsom and has written several economics texts.
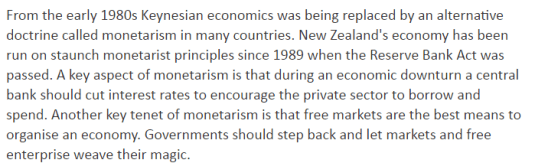
Source: Peter Lyons: Free market doctrine’s bubble about to burst – Economy – NZ Herald News.
Source: Milton Friedman (1984).
Inflation targeting explained
06 Feb 2016 Leave a comment
in economics of bureaucracy, macroeconomics, monetary economics
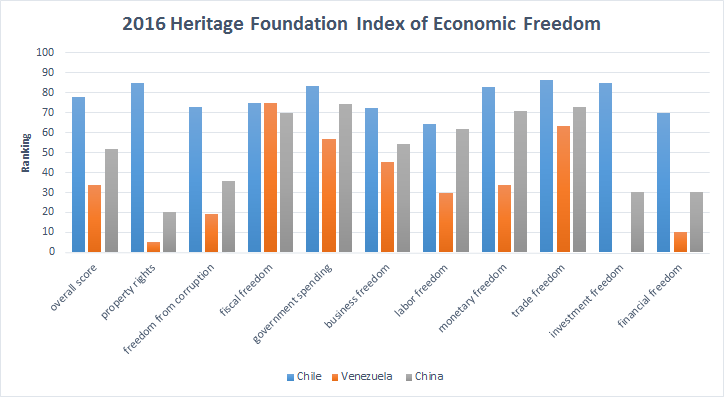
@OwenJones84 @K_Niemietz Venezuelan, Chilean and Chinese index of economic freedom rankings 2016
06 Feb 2016 Leave a comment
in development economics, economics of regulation, entrepreneurship, fiscal policy, growth disasters, growth miracles, industrial organisation, labour economics, law and economics, macroeconomics, monetary economics, property rights, public economics Tags: capitalism and freedom, Chile, China, The Great Escape, Venezuela
% industrialised countries at zero or near zero central bank interest rates
04 Feb 2016 Leave a comment
in business cycles, currency unions, Euro crisis, global financial crisis (GFC), great recession, inflation targeting, macroeconomics, monetarism, monetary economics Tags: central banks, liquidity trap, monetary policy
Review of #TheBigShort including of the movie
02 Feb 2016 Leave a comment
in applied price theory, business cycles, economic history, entrepreneurship, financial economics, global financial crisis (GFC), great recession, macroeconomics, monetary economics, movies Tags: bank runs, financial crises
About the only time the Hollywood Left oozes with patriotism is when getting stuck into Wall Street. Hollywood must get its revenge for all those times investors did not back their film pitches, trimmed budgets and get the lion’s share of merchandising royalties and syndication profits. As Larry Ribstein explained:
American films have long presented a negative view of business…. it is not business that filmmakers dislike, but rather the control of firms by profit-maximizing capitalists… this dislike stems from filmmakers’ resentment of capitalists’ constraints on their artistic vision.
The Big Short is still a good film despite the left-wing populism, worth going to see. Its limitations in not discussing the monetary policy of The Fed or regulations that encouraged lending to high risk borrowers are justified poetic license and editing.
The film is already 120+ minutes long despite frequent resorts to breaking the fourth wall to explain technical terms, who was what and what they were doing, past and present. The Big Short is a film designed it make money at the box office, not a semester long documentary.
The Big Short is well acted, funny, insightful and still a good story despite the documentary element that was impossible to do without.
The Big Short highlights that its protagonists had skin in the game. They were investing in mortgages or shorting the same in the expectation of a crash. There were no windbags and armchair critics in The Big Short talking gloom and doom on the horizon without investing their own money to profit from their forecasts. That said, the protagonists betting on a sub-prime mortgages crash, bar two of them, were a little bit nutty.
I do not know any of the critics of the economics of the film’s explanation of the sub-prime crisis who suggested how they could fix these gaps in its economics without making the film much, much longer.
These critics fall into the exact same trap that the Big Short was not about. The Big Short was about investors to put their money where their mouth is. The critics of the film should put their script doctoring skills where their mouths are at least of The Big Short.
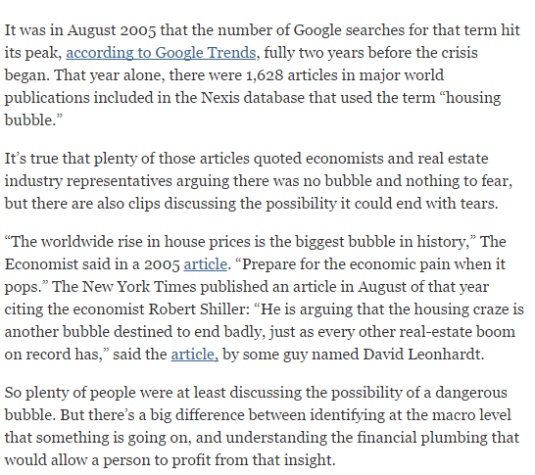
Source: What ‘The Big Short’ Gets Right, and Wrong, About the Housing Bubble – The New York Times.
Getting stuck into the role of the Fed and regulatory mandates on the banks regarding their level of sub-prime mortgages is for another film. Plenty of people warned of dark days ahead. An essay anyone can read with profit is Ross Levine’s “An Autopsy of the U.S. Financial System: Accident, Suicide, or Negligent Homicide?“
Other films, correctly documentaries, place the blame for the sub-prime crisis and the Great Recession directly on the Fed:
The financial mess we’re still climbing out of can be laid directly at the feet of the Fed, whose misguided advocacy, under Greenspan, of a borrow-and-spend economy rather than a focus on savings and investment has created a situation where, as the title implies, money is disconnected from any underlying value.
There are plenty of points that could be added to the economics of The Big Short if it was a film of more or less unlimited length:
Krugman and friends like the film because it leaves out any discussion of the main culprit behind the financial crisis, which was not Wall Street “greed” but bad monetary and credit policies from the Federal Reserve and the federal government. The movie barely hints at any exogenous factors behind the boom or bust. (This FEE report by Peter Boettke and Steven Horwitz fills in the missing information.) So the pro-regulation crowd is cheering. Viewers are given no understanding of the real causal factors and hence fill in the missing data with a feeling that banks just love ripping people off. To be sure, if you approach this movie with some knowledge of economics and monetary policy, the rest of the narrative makes sense. Of course Wall Street got it wrong, given Washington’s policies on mortgage lending!
To add to the brew, Edward Prescott points out the Great Recession can be explained through productivity shocks. Specifically, a collapse in investment and in particular investment in intangibles such as intellectual property in 2007 in anticipation of more taxes and more regulation.
The Great Recession had many of the same features of the 1990s technology boom but in reverse. The boom in the 1990s and bust in 2007 were somewhat inexplicable because major sources of volatility were unmeasured, specifically, investment in intangible capital.
V.V. Chari also points out that the extent of the financial crisis was overstated. This is because the typical firm can finance its capital expenditures from retained earnings so it was hard to see how financial market disruptions could directly affect investment.
What Chari disputed was that bank lending to non-financial corporations and individuals has declined sharply, that interbank lending is essentially non-existent; and commercial paper issuance by non-financial corporations declined sharply, and rates have risen to unprecedented levels.
John Taylor argues that we should consider macroeconomic performance since the 1960: There was a move toward more discretionary policies in the 1960s and 1970s; A move to more rules-based policies in the 1980s and 1990s; and back again toward discretion in recent years.
These policy swings are correlated with economic performance—unemployment, inflation, economic and financial stability, the frequency and depths of recessions, the length and strength of recoveries. Less predictable, more interventionist, and more fine-tuning type macroeconomic policies have caused, deepened and prolonged the current recession. Robert Hetzel puts it this way:
The alternative explanation offered here for the intensification of the recession emphasizes propagation of the original real shocks through contractionary monetary policy. The intensification of the recession followed the pattern of recessions in the stop-go period of the late 1960s and 1970s, in which the Fed introduced cyclical inertia in the funds relative to changes in economic activity.
Finn Kydland considers fiscal policy to be at the heart of the slow recovery. Instead of restructuring and investing more prudently, Western countries faced with budget shortfalls will seek to increase taxes:
- The U.S. economy isn’t recovering from the Great Recession of 2008-2009 with the anticipated strength.
- A widespread conjecture is that this weakness can be traced to perceptions of an imminent switch to a regime of higher taxes.
- The fiscal sentiment hypothesis can account for a significant fraction of the decline in investment and labor supply in the aftermath of the Great Recession, relative to their pre-recession trends.
- The perceived higher taxes must fall almost exclusively on capital income. People must suspect that the tax structure that will be implemented to address large fiscal imbalances will be far from optimal.
Now imagine trying to incorporate all the above points into a film and keeping it at its current two-hour length?
% global GDP with negative central bank interest rates
30 Jan 2016 Leave a comment
in economic history, global financial crisis (GFC), monetary economics
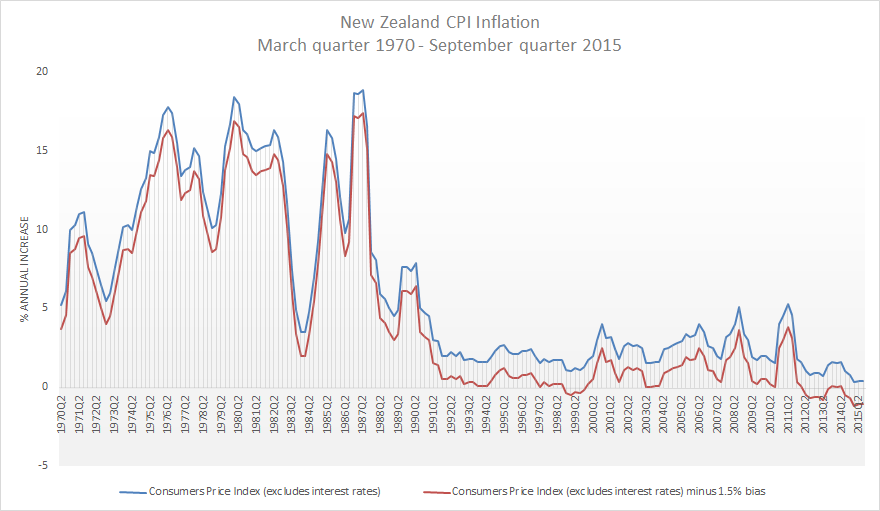
New Zealand inflation rate adjusted for CPI measurement bias since 1970
20 Jan 2016 Leave a comment
in applied price theory, business cycles, economic growth, economic history, macroeconomics, monetary economics, politics - New Zealand Tags: CBI bias, inflation rate, measurement error, price indexes
1% to 1.5% is the usual estimate of bias in the consumer price index because of the introduction of new groups and quality upgrades in existing goods. I have adjusted the consumer price index inflation rate back to 1970 in New Zealand by 1.5% to see how long ago prices became stable. I know this is a rough adjustment, but it is still informative. If anything, the bias in the consumer price index from new goods and product upgrades is increasing rather than decreasing.
Source: Reserve Bank of New Zealand.
Prices have been stable or falling in New Zealand’s for at least three years now once bias in the consumer price index is taken into account. Despite this deflation, the economy seems to be getting along pretty well. There is also a long period of more or less stable prices in the 1990s once bias is taken into account in the measurement of consumer prices by the Statistics New Zealand.
 Utopia, you are standing in it!

Recent Comments