Shawshank Redemption — Money in Prison
15 Sep 2016 Leave a comment
in applied price theory, monetary economics Tags: Shawshank Redemption
NZ inflation rate since 1991 with 1% CPI bias adjustment
13 Sep 2016 Leave a comment
in economic history, inflation targeting, macroeconomics, monetary economics, politics - New Zealand Tags: CPI bias, inflation rate
The inflation rate is overstated by about 1% each year because of difficulties in measuring new goods entering the consumer price index and improvements in the quality of existing goods in the consumer price index. With that adjustment of 1% in the chart below, a common measure of that bias, New Zealand has had zero to negative inflation for four years
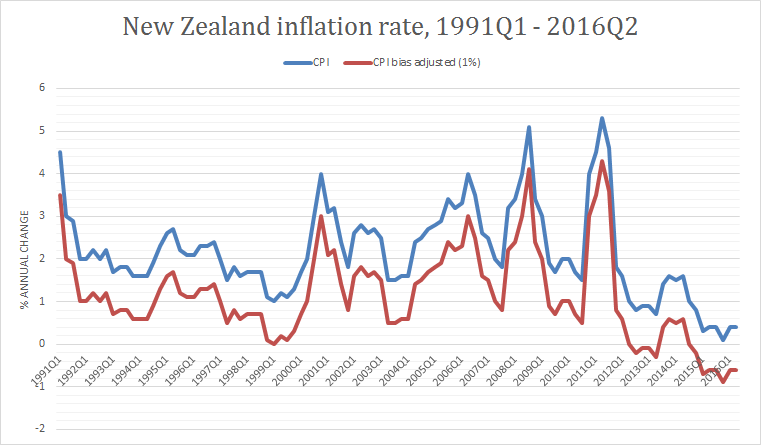
Source: Reserve Bank of New Zealand Key Statistics.
One of the reasons for an inflation target band of 1 to 3% is an inflation rate of 1% is actually an inflation rate of 0%.
Four Reasons Financial Intermediaries Fail
28 Jul 2016 Leave a comment
in applied price theory, business cycles, macroeconomics, monetary economics Tags: bank panics, banks runs
Hayek on Milton Friedman and Monetary Policy
25 Jun 2016 Leave a comment
in business cycles, economics, F.A. Hayek, macroeconomics, Milton Friedman, monetarism, monetary economics
@NZGreens @jamespeshaw forgot how much NZ’s deposit insurance recently cost taxpayers
22 Jun 2016 Leave a comment
in applied price theory, monetary economics, politics - New Zealand
The Greens co-leader James Shaw has today called for New Zealand to re-introduce deposit insurance saying that
“It would be a small levy placed on the banks, which would go into an insurance fund. It’s been operating successfully in many, many other countries.” But Mr Shaw said the Government and Reserve Bank keep putting off the change, saying customers can choose the bank they believe is most stable. “Consumers are not well educated about the stability of banks, so what that means is they tend to flow to the really big Australian-owned banks.”
Deposit insurance has a long history of promoting banking instability and irresponsible lending. It has not operated successfully in other countries nor in New Zealand. The Green Party announcement made no mention of New Zealand’s recent experience with deposit insurance
At the height of the global financial crisis and in the final days of the 2008 general election, New Zealand not only extended a deposit guarantee to its banks it also did so to finance companies. As the Auditor-General recorded in her recent report
On Sunday 12 October 2008, at the peak of the global financial crisis, the Government decided that it needed to implement a form of retail deposit guarantee scheme to avoid a flight of funds from New Zealand institutions to those in Australia. It needed to do this urgently: The Crown Retail Deposit Guarantee Scheme (the Scheme) was designed and announced that same day.
The deposit guarantee was extended to finance companies. Money flooded into previously high risk investments as investors had nothing to lose and everything to gain from the higher returns.
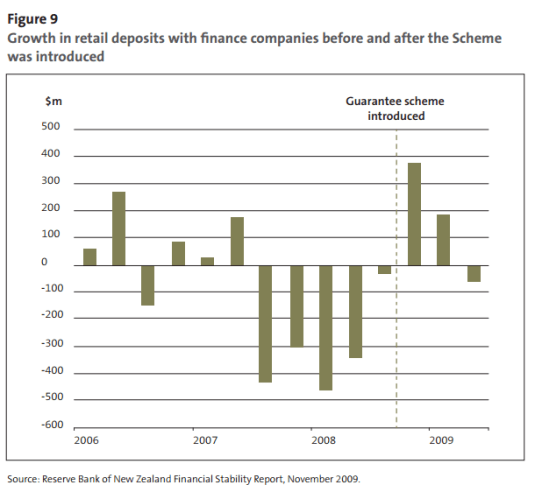
As the Auditor-General noted in a 2015 recent report reviewing the scheme
From the outset, the advice from officials recognised that the decision to include finance companies in the Scheme carried significant risk. Once deposits with these companies were guaranteed, depositors could safely move investments to where they would get the highest return, irrespective of the risk of company failure.
The finance companies also had less reason to minimise risk in their investment activity. The Crown was carrying much of this risk. During 2009, the Treasury watched some of that behaviour eventuate. Deposits with finance companies under the Scheme grew, in some instances significantly. We saw one example where a finance company’s deposits grew from $800,000 to $8.3 million after its deposits were guaranteed. At South Canterbury Finance Limited, the deposits grew by 25% after the guarantee was put in place.
The flood of deposits into finance company after the deposit guarantee somewhat undermines the low opinion the Greens have of depositors as investors sensitive to risk
On blunting incentives, otherwise known as ‘moral hazard’, Bill English can’t seriously expect everyday savers to analyse the loan books of banks to assess their credit risk when they open their accounts, let alone do this on a six-monthly basis.
At its height, the bank and finance company guarantees totalled over $133 billion. Ninety-six institutions were covered by the scheme – 60 non-bank deposit takers, 12 banks and 24 collective investment schemes. All guarantees had ended by December 2011.
To put context on the risk that the taxpayer, this $133 billion underwritten by the taxpayer return for little or no insurance fee was nearly twice the amount the Government spends in a year, or about 2/3rd of GDP.
If a financial institution in the Scheme failed, taxpayers would repay all of the money that eligible people had deposited or invested, up to a cap of $1 million each.
Nine finance companies out of the 30 accepted into the scheme failed. This resulted in payments by the taxpayer to the investors of $2 billion. Expected recoveries are currently estimated at about $0.9 billion after the completion of the various receiverships of these institutions according to the recent report on the scheme by the Auditor-General.
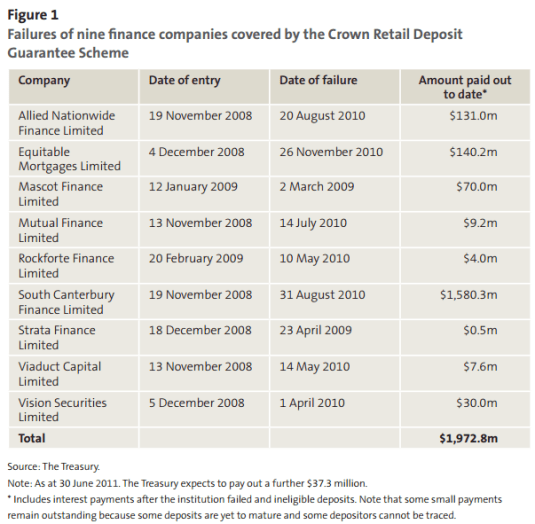
The deposit guarantee was extended to the finance companies despite 28 such companies failing between 2006 and 2008. This included some larger finance companies such as Bridgecorp Finance (New Zealand) Limited, Provincial Finance Limited, and Hanover Finance Limited.
FDR was initially opposed to deposit insurance in the USA in 1933 because it would encourage greater risk taking by banks. Sam Peltzman in the mid-1960s found that U.S. banks in the 1930s halved their capital ratios after the introduction of federal deposit insurance.
If you want to make banks safer, increase their capital ratios and require them to have more subordinated debt in their capital requirements.
Any form of deposit insurance requires extensive regulation of insured bank portfolios to prevent excessive risk-taking. The Kareken and Wallace model of deposit insurance which is based on moral hazard, predicts that if a government sets up deposit insurance and doesn’t regulate bank portfolios to prevent them from taking too much risk, the government is setting the stage for a financial crisis. The Kareken-Wallace model makes you very cautious about lender-of-last-resort facilities and very sensitive to the risk-taking activities of banks.
Kareken and Wallace called for much higher capital reserves for banks and more regulation to avoid future crises. It is much easier to require banks to put up more capital than to not take risks with the monies invested in them by depositors.
Hayek Lecture 2016: Price Stability and Financial Stability without Central Banks
19 Jun 2016 Leave a comment
in applied welfare economics, Austrian economics, comparative institutional analysis, macroeconomics, monetary economics Tags: free banking
Tom Sargent on Macroeconomic Theory and the Crisis
12 Jun 2016 Leave a comment
in business cycles, currency unions, economics, Euro crisis, fiscal policy, global financial crisis (GFC), great recession, macroeconomics, monetary economics Tags: Tom Sargent
Hayek on Friedman as a Keynesian
28 May 2016 Leave a comment
in business cycles, F.A. Hayek, history of economic thought, macroeconomics, Milton Friedman, monetarism, monetary economics Tags: Keynesian macroeconomics
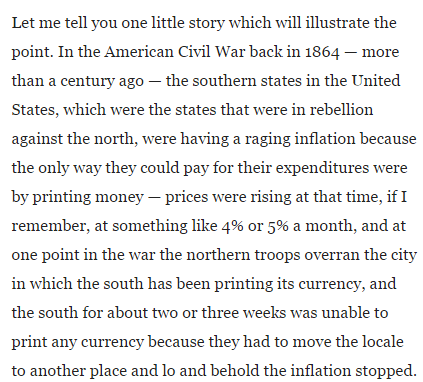
Milton Friedman on inflation as a monetary phenomena
24 May 2016 1 Comment
in macroeconomics, Milton Friedman, monetarism, monetary economics Tags: American Civil War, inflation
What 3 skills do public policy analysts need?
27 Apr 2016 Leave a comment
in applied price theory, business cycles, economics of bureaucracy, economics of regulation, fiscal policy, macroeconomics, monetary economics Tags: anti-market bias, antiforeign bias, expressive voting, lags on monetary policy, makework bias, rational rationality, tax incidence, The fatal conceit, The pretense to knowledge
I used to argue that the quality of public policy making would double if public policy analysts remembered the first 6 weeks of microeconomics 101 but on reflection more than that is required.
Could we economists today ever show such self-restraint about our own expert recommendations? https://t.co/2UE12JuIgn—
William Easterly (@bill_easterly) November 24, 2015
I picked up my initial insight out when working as a graduate economist in the Australian Department of Finance. That was a few years ago.
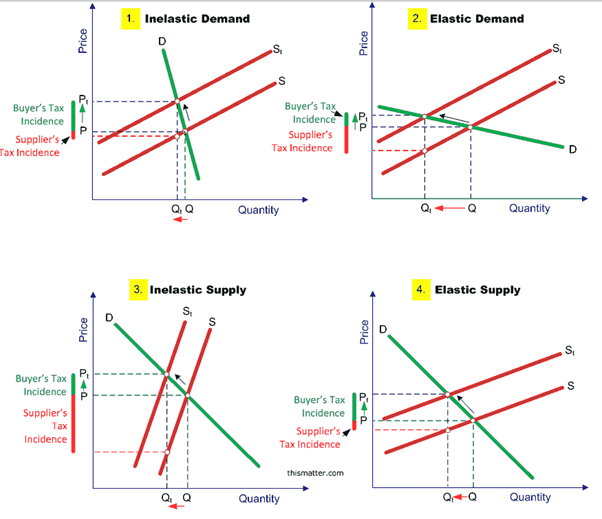
I am now concluded that policy analysts also need to know the basics of the economics of tax incidence. Who pays the tax depends on the elasticities of supply and demand rather than who writes the check to the taxman.
The number of times that I have read media and public policy analysis saying who pays the tax is the writer of the cheque to the taxman is beyond counting.
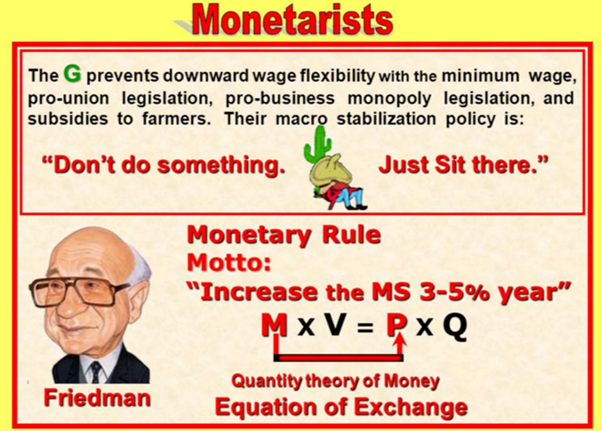
There is also what to do about unemployment and inflation. Do not just do something, sit there might be good advice on most occasions. As Tim Kehoe and Gonzalo Fernandez de Cordoba explain in the context of first do no harm:
Looking at the historical evidence, Kehoe and Prescott conclude that bad government policies are responsible for causing great depressions.
In particular, they hypothesize that, while different sorts of shocks can lead to ordinary business cycle downturns, overreaction by the government can prolong and deepen the downturn, turning it into a depression.
Deposit insurance
11 Apr 2016 Leave a comment
in applied price theory, business cycles, economic history, economics, economics of regulation, global financial crisis (GFC), macroeconomics, monetary economics, Public Choice, rentseeking Tags: bank runs, banking crises, banking panics, deposit insurance, Thomas Sargent
Many of the key issues about what modern macroeconomics has to say on global financial crises and deposit insurance are discussed in a 2010 interview with Thomas Sargent
Sargent said that two polar models of bank crises and what government lender-of-last-resort and deposit insurance do to arrest or promote them were used to understand the GFC. They are polar models because:
- in the Diamond-Dybvig and Bryant model of banking runs, deposit insurance and other bailouts are purely a good thing stopping panic-induced bank runs from ever starting; and
- in the Kareken and Wallace model, deposit insurance by governments and the lender-of-last-resort function of a central bank are purely a bad thing because moral hazard encourages risk taking unless there is regulation or there is proper surveillance and accurate risk-based pricing of the deposit insurance.
In the Diamond-Dybvig and Bryant model, if there is government-supplied deposit insurance, people do not initiate bank runs because they trust their deposits to be safe. There is no cost to the government for offering the deposit insurance because there are no bank runs! A major free lunch.
Tom Sargent considers that the Bryant-Diamond-Dybvig model has been very influential, in general, and among policy makers in 2008, in particular.
Governments saw Bryant-Diamond-Dybvig bank runs everywhere. The logic of this model persuaded many governments that if they could arrest the actual or potential runs by convincing creditors that their loans were insured, that could be done at little or no eventual cost to taxpayers.
In 2008, the Australian and New Zealand governments announced emergency bank deposit insurance guarantees. In Bryant-Diamond-Dybvig style bank panics, these guarantees ward off the bank run and thus should cost nothing fiscally because the deposit insurance is not called upon. These guarantees and lender of last resort function were seen as key stabilising measures. These guarantees were called upon in NZ to the tune of $2 billion.
- 1. The Diamond-Dybvig and Bryant model makes you sensitive to runs and optimistic about the ability of deposit insurance to cure them.
- The Kareken and Wallace model’s prediction is that if a government sets up deposit insurance and doesn’t regulate bank portfolios to prevent them from taking too much risk, the government is setting the stage for a financial crisis.
- The Kareken-Wallace model makes you very cautious about lender-of-last-resort facilities and very sensitive to the risk-taking activities of banks.
Kareken and Wallace called for much higher capital reserves for banks and more regulation to avoid future crises. This is not a new idea.
Sam Peltzman in the mid-1960s found that U.S. banks in the 1930s halved their capital ratios after the introduction of federal deposit insurance. FDR was initially opposed to deposit insurance because it would encourage greater risk taking by banks.

Late on Friday afternoon, Stuff posted an op-ed piece calling for the introduction of a (funded) deposit insurance scheme in New Zealand. It was written by Geof Mortlock, a former colleague of mine at the Reserve Bank, who has spent most of his career on banking risk issues, including having been heavily involved in the handling of the failure, and resulting statutory management, of DFC.
As the IMF recently reported, all European countries (advanced or emerging) and all advanced economies have deposit insurance, with the exception of San Marino, Israel and New Zealand. An increasing number of people have been calling for our politicians to rethink New Zealand’s stance in opposition to deposit insurance. I wrote about the issue myself just a couple of months ago, in response to some new material from the Reserve Bank which continues to oppose deposit insurance.
Different people emphasise different arguments in making the case for New Zealand to…
View original post 1,963 more words
@NZGreens expand KiwiBank into wrong market to cut mortgage rates @JulieAnneGenter
03 Apr 2016 1 Comment
in industrial organisation, monetary economics, politics - New Zealand, survivor principle Tags: economics of banking, government ownership, KiwiBank, New Zealand Greens, offsetting behaviour, privatisation, rational irrationality, state owned enterprises, The fatal conceit
The Greens want to cut mortgage rates by having KiwiBank expand in business lending. Wrong market.
This expansion into a market that is not the mortgage market is to be underwritten by a capital injection as the Greens explain:
- Inject a further $100 million of capital in KiwiBank to speed its expansion into commercial banking;
- Allow KiwiBank to keep more of its profits to help it grow faster; and,
- Give KiwiBank a clear public purpose to lead the market in passing on interest rate cuts.
Note well that the $100 million capital injection is to expand in to commercial banking. More aggressive passing on of interest rate cuts may jeopardise credit ratings if this lowers the profitability of KiwiBank. KiwiBank has an A- rating
The bigger hole in the policy is the more aggressive mortgage rate setting by KiwiBank will be done by keeping more of its profits and paying fewer dividends to its parent company Kiwi Post and through that to the taxpayer. There are next to no dividends currently to stop distributing to fund a more aggressive mortgage rate setting policy.
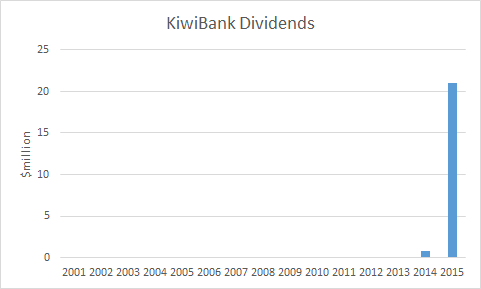
Source: KiwiBank pays its first dividend of $21 million to Government | Stuff.co.nz.
KiwiBank paid its first dividend last year. Prior to that, the bank kept all profits to allow it to expand its lending base. $20 million in foregone dividends does not go far given the actual size of all lending markets in New Zealand.
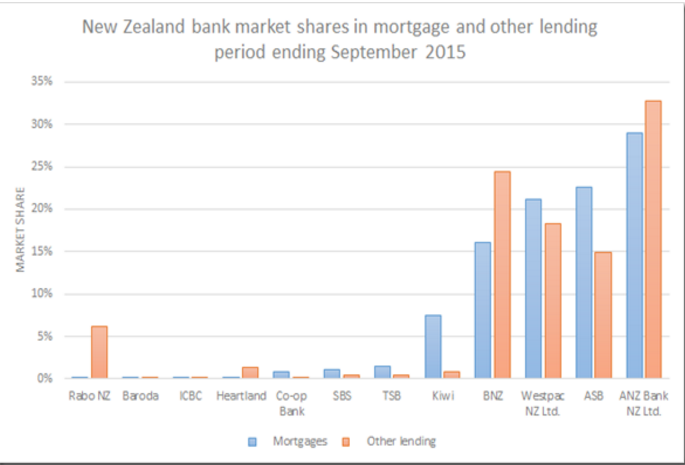
Source: G1 Summary information for locally incorporated banks – Reserve Bank of New Zealand.
KiwiBank is minnow in the mortgage market and a pimple in commercial lending. Rapid business expansion is risky in any market, much less in banking.
The government has declined further capital injections so profits were retained to meet capital adequacy ratios. The government in 2010 earmarked NZ$300 million for an uncalled capital facility for NZ Post to help maintain its credit rating and KiwiBank’s growth.
Saving the best for last, KiwiBank last year announced plans to borrow up to $150 million through an issue of BB- perpetual capital notes to be used to bolster the bank’s regulatory capital position.
The Margin for the Perpetual Capital Notes has been set at 3.65% per annum and the interest rate will be 7.25% per annum for the first five years until the first reset date of 27 May 2020. Kiwi Capital Funding Limited is not guaranteed by KiwiBank, New Zealand Post nor the New Zealand Government.
The Perpetual Capital Notes have a BB- credit rating compared to KiwiBank which has an A- rating. These capital notes were issued in addition to prior subordinate debt in the form of CHF175 million (about NZ$233 million) worth of 5-year bonds.
I doubt that KiwiBank can raise capital through subordinated debt under normal commercial conditions if it does not plan to seek profits in the same way as other commercial banks do. The current issue of Perpetual Capital Notes are already rated as junk bonds:
An issue of $150 million of perpetual capital notes from KiwiBank with a speculative, or "junk", credit rating have been priced at the bottom of their indicative margin range.
The closest the prospectus for these Perpetual Capital Notes got to complementing KiwiBank changing from a normal business to being a public good is the following risk statement:
Kiwibank’s banking activities are subject to extensive regulation, mainly relating to capital, liquidity levels, solvency and provisioning.
Its business and earnings are also affected by the fiscal or other policies that are adopted by various regulatory authorities of the New Zealand Government.
The interest rate on this subordinate debt will go up to offset the additional risk of aggressive lending and aggressive expansion, which will cancel out many of the advantages of not having to pay for dividends and the capital injection.
That discipline is one of the purposes of subordinate debt in the regulatory capital of banks. This is to provide another pair of eyes and ears to watch the performance of the bank and through rising costs of lending and risk ratings, signal trouble of imprudent lending and lack of cost control.
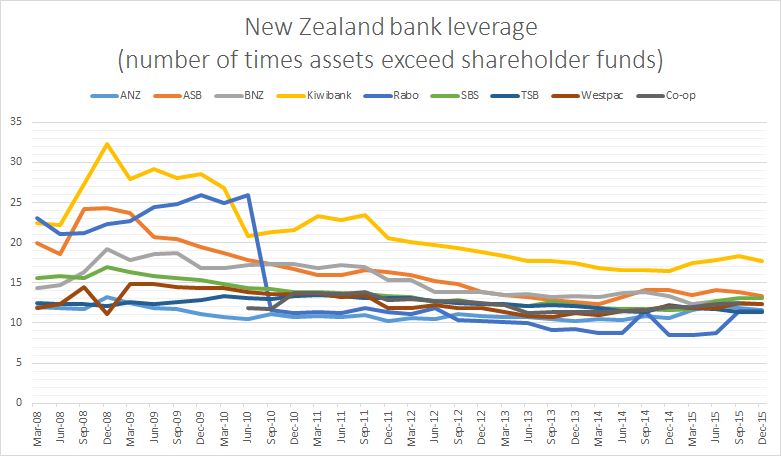
The proposal to use KiwiBank to lower mortgage rates does not add up. KiwiBank does not pay much in the way of dividends to fund such a foray. KiwiBank is already far more leveraged than any other New Zealand major bank.
 Utopia, you are standing in it!

Recent Comments