The impact of drought on the 1998 mild New Zealand recession

Reserve Bank of New Zealand has these conclusions about the contribution of drought to the business cycle in the late 1990s in New Zealand and in particular the mild 1998 recession:

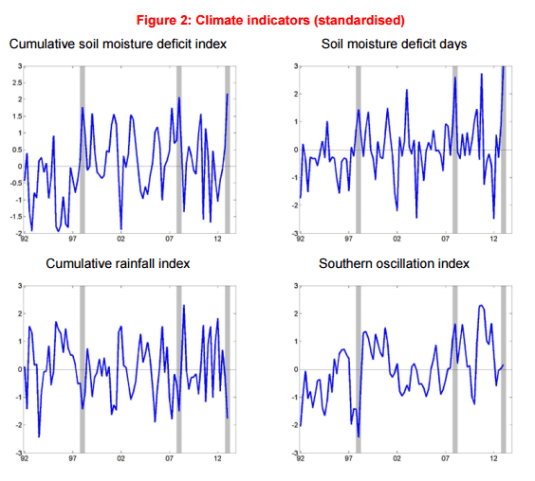
a back-of-the-envelope estimate of the impact of the drought-induced fall in supply would suggest a contribution from the agricultural sector to production GDP for the March quarter of 1998 of around -0.4 percentage points out of the total 1 per cent fall in production GDP. In the June quarter of 1998, the contribution from these sectors was close to zero.

Figure 27:

0096149_files/business-cycle-developments-since-1996-for-submission-to-monetary-policy-review-final-version-placed-on-web-27.jpg


In 1998, agricultural and hunting industry contributed per cent of real GDP. . That included the production of livestock, wool, dairy, horticulture, and crops, as well as the provision of agricultural contracting services and hunting. In the same year, the primary food manufacturing industry contributed 3 per cent of GDP. This category covers the processing of meat and dairy products for export and local markets.

The Tobin tax or @RobinHoodTax makes those monetary cranks in the social credit movement look credible!

Sweden led the way with Tobin taxes in 1986: a 0.5% tax on the purchase or sale of an equity security. The revenues from the Tobin tax were initially expected to be 1,500 million Swedish kronor per year.

The actual revenues collected did not amount to more than 80 million Swedish kronor in any year and the average was closer to 50 million. Bond trading fell by more than 80 percent and the options market died. A lesson never learned by Tobin tax advocates. As taxable trading volumes fell, so did revenues from capital gains taxes, entirely offsetting the revenues from the equity transactions tax.

During the first week of the Swedish tax, the volume of bond trading fell by 85%; futures trading fell by 98%; and the options trading market disappeared. Trading for over 50% of Swedish equities moved to London by 1990. A true Robin Hood tax: the Tobin tax robbed from the Swedish capital gains taxman and gave to the British stamp duty taxman.

The Tobin tax is named after U.S. economist James Tobin who in 1972 suggested taxing foreign-exchange trades to limit currency speculation.

The Tobin tax on foreign-exchange transactions was to provide a disincentive for traders to make so many international transfers of money. Tobin in 1978 wrote that currency speculation can have ‘serious and painful internal economic consequences’. Tobin said his Tobin tax idea was unfeasible in practice.

Tobin and his idea of taxing of currency speculation improves market efficiency is total nonsense in theory as Milton Friedman explained:

The empirical generalization about the prevalence of destabilizing speculation, which is what gives the theoretical proposition its interest, seems to be one of those propositions that has gained currency the way a rumour does— each man believes it because the next man does, and despite the absence of any substantial body of well documented evidence for it.

Is the Tobin tax designed to raise 35 billion euros in revenue, as promised by EU Tax Commissioner Algirdas Semeta, or is it designed to curb speculation as was the original motivation by James Tobin to propose this tax?

Many have extolled such a tax as a potential source of earmarked revenues for a variety of purposes. Both left-wing and right wing populists have advocated the Tobin tax or Robin Hood tax to replace existing taxes or raise additional  revenue.

Both types of populist advocate replacing or augmenting the income tax with a stamp duty. Enough people are familiar when stamp duties to realise that such a tax won’t raise much revenue. But if you call the stamp duty a Robin Hood tax, the media release suspends critical judgement  and cheers them on.

Advocates of the Robin Hood tax blithely assert that the revenue raised will approximately equal 0.5% of the existing share and foreign exchange market turnover with few changes in behaviour or speculative activity, despite the imposition of a tax designed to curb speculation and reduce the total number of transactions significantly.

The $3.7 trillion-a-year Eurobond market came into being after JFK imposed an interest-equalization tax in 1963 to reduce investment in foreign securities by U.S. investors and to ease a so called balance of payments deficit.

What is the point of a Tobin tax if you already have a capital gains tax?. New Zealand doesn’t have a capital gains tax but it does have a tax on assets bought with the intention of resale rather than long-term income.

Why do share markets fall after the announcement of a Tobin tax? Trading in a more stable market should be value enhancing and increase share prices? Ditto exporters and more stable currency prices etc.? Exporter share prices should increase because of less need to hedge? Numerous studies find a significant reduction in equity turnover following a stamp duty introduction.

I am sure that with the City of London as a global financial centre, the British are cheering on efforts of other EU members to sabotage their own financial markets with a Tobin tax. FX turnover in the City of London reached over $1.8 trillion every day in 2010, accounting for 36.7% of the global total. About half of European investment banking activity is conducted through London.

Ed Prescott estimates a large quantity of intermediated borrowing-lending between households – several times GDP.  A large amount of resources is used in this intermediation – a conservative estimate is 4% of GNP.

Prescott also argued that the cost of transferring financial assets has fallen dramatically – from 2% towards zero on Vanguards Indexed ETF. The spread between borrowing and lending by households down – the spread on home mortgages was 3% in 1960s – now about 2%. None of these trends bode well for either a large tax base or growing tax base.

Another way to think about a Tobin tax is to consider it to be a tax on ATM withdrawals. There was such a debits tax on bank withdrawals of $.20 in my home State of Tasmania  in the 1980s.

Naturally, a Tobin tax on ATM withdrawals is not a tax on any sort of real economic activity. People would simply make fewer ATM withdrawals and look for other ways to not use ATMs. It is routine for cash balances to respond to the time and other costs of replenishing money balances, and the fixed cost of using deposits for purchases.

HT: Does a Tobin Tax Make Sense?

How Obamacare affected employment

Blaming droughts on Rogernomics? Droughts and the New Zealand real business cycle

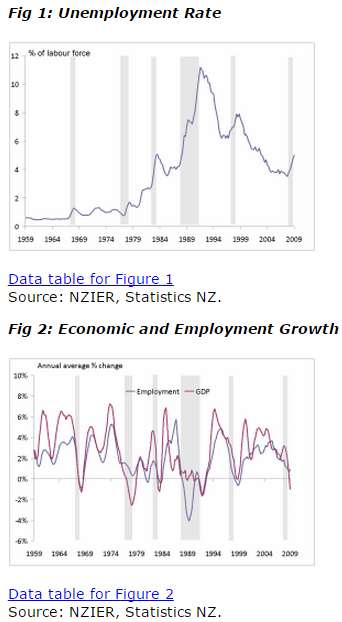
While feuding on another blog about the ups and downs of the New Zealand economy since the 1970s, I pointed out that a long economic boom followed the Ruth RichardsonMother of all Budgets” in 1991:

My interlocutor quickly replied to blame Rogernomics, in particular, inflation targeting and its administration by Don Brash for a severe recession in New Zealand in 1998:

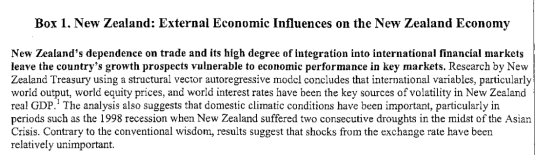
The mild recession in New Zealand in 1998 was a result of the combination of two severe droughts and the effects of the Asian financial crisis.

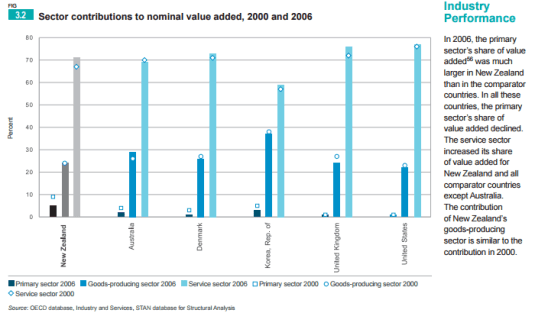
Drought is a major factor in the New Zealand business cycle because of the large size of the farming sector. Indeed, the ups and downs of a monopoly dairy exporter that accounts for 7% of GDP, Fonterra, are so central that a single dirty pipe at a milk factory that put the quality of its milk exports in question lead the Treasury to revise its economic forecasts for that year.

There is growing evidence that a substantial part of business cycle volatility can be explained by real business cycle theory (RBC). RBC claims that a good majority of economic volatility is caused by changes on the supply side: tax and regulatory changes, bad weather in farm economies, spikes in oil prices and technology shocks. Real business cycle models have enjoyed success in replicating most of the observed characteristics of, for example, U.S. aggregate economic activity.

Over the last 15 years, a number of papers at the Treasury and Reserve Bank of New Zealand have explored the role of droughts in the New Zealand business cycle, such as the drought in 1997.

The 1998 recession was preceded by a severe drought that may have knocked a half percentage point off GDP or more. As the Treasury explained in 2008:

Given the importance of the primary sector in New Zealand, climatic conditions have always been a significant driver of GDP volatility in New Zealand. There is strong evidence that the 1998 drought triggered or precipitated the onset of the last recession in the late-90s.

In 2008, the dry conditions in New Zealand led the Treasury to revise its forecasts as follows:

current dry conditions are likely to trim GDP growth by around 0.5% for the 2008 calendar year.  

In 2013, the Reserve Bank made similar pessimistic forecasts about the implications of drought for economic prospects. New Zealand was suffering its worst drought in decades:

It was simply mistaken to blame the 1998 recession in New Zealand as the spawn of Rogernomics. There was a drought, a big one, big enough drought to shake the New Zealand business cycle in a country with a large farming sector.

The most important aspect of monetary strategy is timing

The simplest statement to make about the lags in monetary policy is they are long and variable. This simple statement is also the key insight to understanding the actual implementation of monetary policy. Hence, how many months or years in advance must a central bank forecast to achieve its monetary goals? In 1994, the Economist said:

But [central banks] cannot afford to wait until inflation is actually rising before they act. Monetary policy does not change the speed of the economy instantly: it can take 18 months or more for a rise in interest rates to have its full impact on inflation. The target of policy ought therefore to be future not current inflation, in order to prevent a surge in 1996. The earlier interest rates are raised, the better the chances of engineering a smooth slowdown to a sustainable rate of growth before slack in the economy is exhausted.

Economists differ about the length of those lags. Uncertainty about the average length of those lags and the variability of those lags makes discretion most difficult. Activist policy can improve welfare only if the information about economic structure and economists’ ability to forecast is sufficiently accurate.

Early_sample

Friedman is the most famous and persuasive critic of Keynesianism on the grounds of lags. He has two main arguments: first, that there are “long and variable lags” between the identification of a problem and the effects of the designed remedy; second, that activist policy often itself becomes a source of instability since policy itself becomes a variable that the market must guess.

Friedman’s critique does not depend on the quantity theory of money. Keynesian policies do not necessarily follow even if the Keynesian theory of the business cycle were conclusively proved.

It must also be demonstrated that the government has the ability and willingness of the government to act as the theory prescribes. We are therefore further assuming that central banks have the incentive to stabilise the economy. If the government lacks the information required to stabilise the economy, issues of public choice incentives become fully redundant. Incentives to pursue an objective do not matter if the objective itself is unattainable.

EU corporate tax “around 20%”? Nah!

Image

Competing visions of central banking

Economics: A Million Mutinies Now, Part Two - feat. image

The competing visions of central banks over monetary policy have been defined by Franco Modiglani and Milton Friedman respectively. Modiglani considers the Keynesian vision of macroeconomic policy to be:

a market economy is subject to fluctuations which need to be corrected, can be corrected, and therefore should be corrected.

The Keynesian claim implies that central banks have sufficient knowledge of the structure of the economy to be able to choose the policy mix appropriate to a given set of circumstances. It is possible to target unemployment, interest rates and inflation in such a way that they can be maintained (and hence made predictable) by constant adjustment of policy instruments to new shocks.

The Keynesian approach assumes that the economy can slip into recessions for all sorts of reasons (Barro 1989). Business fluctuations result from shocks to aggregate demand. The principal source of these shocks are expectations induced shifts in investment demand. The role of the central bank is to make prompt, frequent policy responses to counteract this instability.

The task of government is to discover the particular monetary and fiscal polices which can eliminate shocks emanating from the private sector. A key finding of recent macroeconomic research is that anticipated monetary policy has very different effects to unanticipated monetary policy.

The Keynesian vision thus presuppose that government can foresee shocks which are invisible to the private sector but at the same time it is unable to reveal this advance information in a credible way and hence defusing the shock because it is no longer unanticipated. In addition, the counter cyclical monetary policies of governments must themselves be unforeseeable by private agents, but at the same time systematically related to the state of the economy (Lucas and Sargent 1979)

Of course, the Keynesian view of central banking is also premised on a goodwill theory of government. Governments pursue policies that are in the public interest. That is a public interest that is well-defined and is free of conflicts over income distribution, electoral success and power the could lead policy-makers to pursue goals other than full employment, stable prices and efficiency. Thus, if the latest forecast is a recession, additional stimulus is the usual prescription. However, since most Keynesian economists accept the permanent income and natural rate hypotheses, more stimulus implies less later at some unknown time.

Friedman’s vision of central banking is far more circumspect:

The central problem is not designing a highly sensitive [monetary] instrument that offsets instability introduced by other factors[in the economy], but preventing monetary arrangements becoming a primary source of instability (Milton Friedman 1959).

Friedman considers that a key element in the case for policy discretion is whether the sufficient information is available that can be used to reduce variability and assist the economy’s adjustment the unforeseen. A well intentioned policy-maker will destabilise if he is mislead by incomplete or incorrect information.

From the monetarist standpoint, price stability can be approximately attained under a well chosen and predictable monetary policy rule. Under this view, the unemployment and interest rates are unpredictable and can manipulated only at a prohibitive cost. The Keynesian and monetarist views are mutually incompatible and lead to very different policy recommendations (Lucas 1981).

Income from selling citizenships now 16% of Malta’s budget

Image

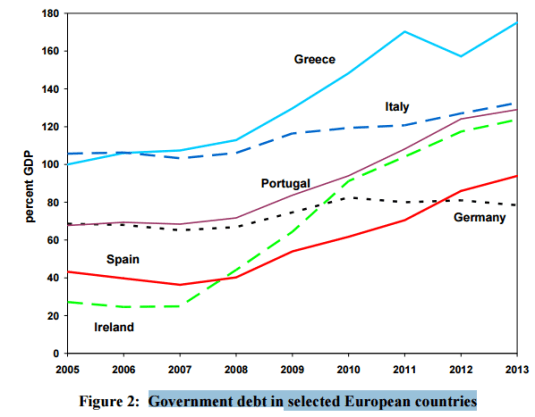
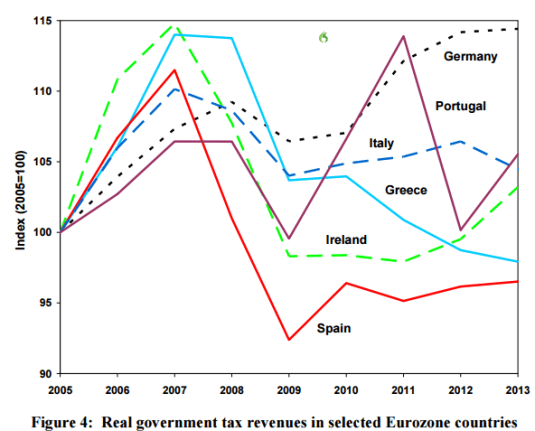
The macroeconomy of Euroland – the good, the bad, and the ugly

Via Gambling for Redemption and Self-Fulfilling Debt Crises | Federal Reserve Bank of Minneapolis.

Why Portugal, Italy, Greece and Spain are called the PIGS

HT: Finn Kydland

The industries where personal connections matter the most in getting a job – The Washington Post

via The industries where personal connections matter the most in getting a job – The Washington Post.

Roberts Solow on the British disease and Eurosclerosis

Robert Solow amateur psychology

HT: Brad Delong

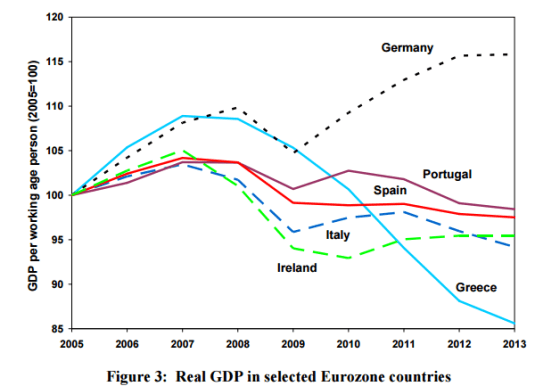
Greece’s Great Depression

Image

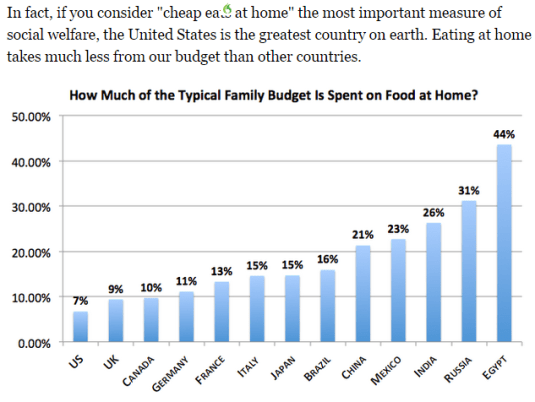
Why is it so expensive to eat in Europe as compared to America?

Via Cheap Eats: How America Spends Money on Food — The Atlantic.

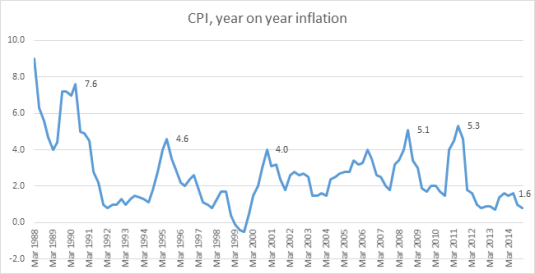
The fall and rise and fall of inflation in New Zealand

After the high inflation rates in the 70s and 80s, inflation disappeared by the end of the century. There is the occasional spike in the 2000s but now inflation is effectively zero. Measurement error in the consumer price index for increases in product quality and new goods means an inflation rate of about 2% rounds down the inflation rate to zero.

Source: Reserve Bank of New Zealand.

Previous Older Entries Next Newer Entries

David Andolfatto

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Monetary Non-Neutrality

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Reason Magazine

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Coyote Blog

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Thoughts from the North

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Fardels Bear

A History of the Alt-Right

Vincent Geloso

Econ Prof at George Mason University, Economic Historian, Québécois

Bassett, Brash & Hide

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Truth on the Market

Scholarly commentary on law, economics, and more

The Undercover Historian

Beatrice Cherrier's blog

Matua Kahurangi

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Temple of Sociology

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Velvet Glove, Iron Fist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Why Evolution Is True

Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.

NoTricksZone

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Homepaddock

A rural perspective with a blue tint by Ele Ludemann

Kiwiblog

DPF's Kiwiblog - Fomenting Happy Mischief since 2003

The Dangerous Economist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Watts Up With That?

The world's most viewed site on global warming and climate change

The Logical Place

Tim Harding's writings on rationality, informal logic and skepticism

Doc's Books

A window into Doc Freiberger's library

The Risk-Monger

Let's examine hard decisions!

Uneasy Money

Commentary on monetary policy in the spirit of R. G. Hawtrey

Barrie Saunders

Thoughts on public policy and the media

Liberty Scott

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Point of Order

Politics and the economy

James Bowden's Blog

A blog (primarily) on Canadian and Commonwealth political history and institutions

Science Matters

Reading between the lines, and underneath the hype.

Peter Winsley

Economics, and such stuff as dreams are made on

A Venerable Puzzle

"The British constitution has always been puzzling, and always will be." --Queen Elizabeth II

The Antiplanner

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Bet On It

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

History of Sorts

WORLD WAR II, MUSIC, HISTORY, HOLOCAUST

Roger Pielke Jr.

Undisciplined scholar, recovering academic

Offsetting Behaviour

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

JONATHAN TURLEY

Res ipsa loquitur - The thing itself speaks

Conversable Economist

In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”

The Victorian Commons

Researching the House of Commons, 1832-1868

The History of Parliament

Articles and research from the History of Parliament Trust

Books & Boots

Reflections on books and art

Legal History Miscellany

Posts on the History of Law, Crime, and Justice

Sex, Drugs and Economics

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

European Royal History

Exploring the Monarchs of Europe

Tallbloke's Talkshop

Cutting edge science you can dice with

Marginal REVOLUTION

Small Steps Toward A Much Better World

NOT A LOT OF PEOPLE KNOW THAT

“We do not believe any group of men adequate enough or wise enough to operate without scrutiny or without criticism. We know that the only way to avoid error is to detect it, that the only way to detect it is to be free to inquire. We know that in secrecy error undetected will flourish and subvert”. - J Robert Oppenheimer.