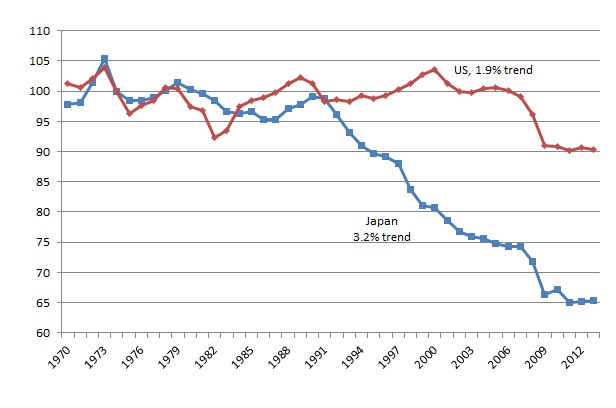
Real GDP per Japanese and American aged 15-64, 2013 price level, updated 2005 EKS PPP, detrended, 1970-2013

image

Source: Computed from OECD StatExtract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics.

Note: When the line is flat, the economy is growing at its trend growth rate. A falling line means below trend growth; a rising line means of above trend growth. Detrended with values used by Edward Prescott.

The Japanese decline after 1992 are the Lost Decades. Japan recently returned to its 3.2% trend growth rate of the 1970s and 1980s for working age Japanese.

It could be argued that Japan is now on a permanently lower growth rate that implies no further catch up with the USA.

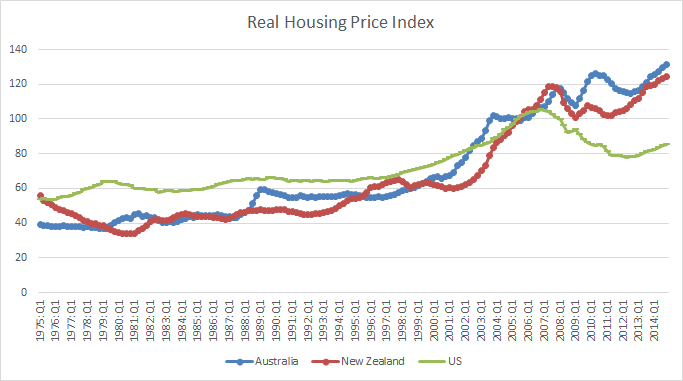
New Zealand, Australian and US real housing price index, 1975–2014, 2005 base

The housing spikes in Australia and New Zealand preceded the global financial crisis, starting in about 1999, and were largely unaffected by the GFC. Housing prices in the USA were pretty calm except in the lead up to the GFC, and took a dive with the onset of the global financial crisis and great recession.

image

Source: Dallas Fed; Housing prices deflated by personal consumption expenditure (PCE) deflator.

.

The ease of enforcing contractual rights in Europe

Employment losses after recent financial crises

How can New Zealand blamed distance for its woes when international technology diffusion is speeding up

The Great Escape compared to the threat of global warming

Unemployment in the UK since 1860

https://twitter.com/MaxCRoser/status/582820401446715392

Image

Diego Comin — Why New Technologies Do Not Make Poor Countries Rich

Recent New Zealand economic growth

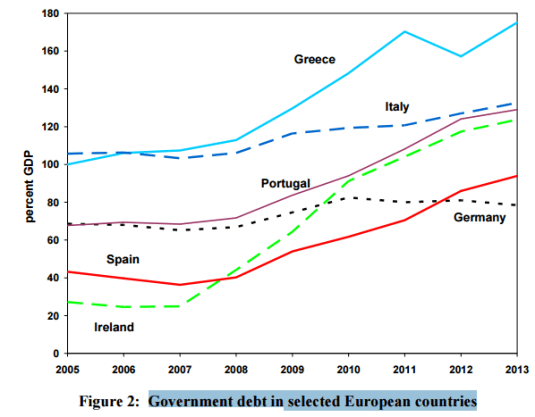
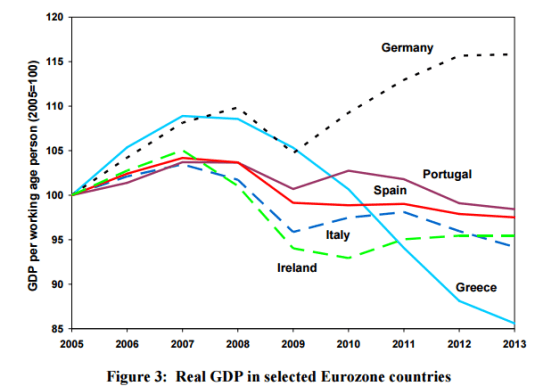
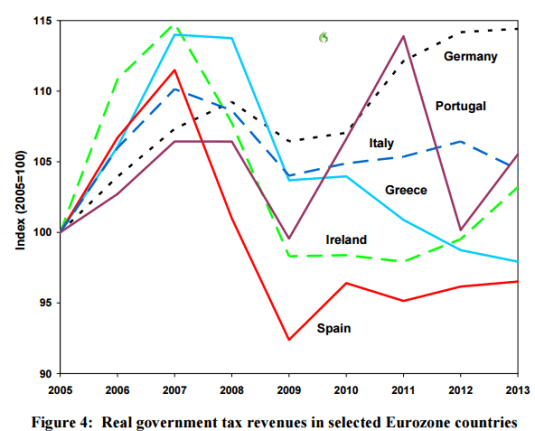
The macroeconomy of Euroland – the good, the bad, and the ugly

Via Gambling for Redemption and Self-Fulfilling Debt Crises | Federal Reserve Bank of Minneapolis.

Trans-Tasman trends in real equivalised mean household income since 1982

Real household mean incomes rose during Rogernomics; fell during the deep recession at the beginning of the early 1990s; then rose strongly until 2009 and the onset of the Global Financial Crisis.

Skyscrapers in the business cycle

A very British recovery

Image

The three lags on monetary policy

There are large uncertainties about the size and timing of responses to changes in monetary policy. There is a close and regular relationship between the quantity of money and nominal income and prices over the years. However, the same relation is much looser from month to month, quarter to quarter and even year to year. Monetary changes take time to affect the economy and this time delay is itself highly variable. The lags on monetary policy are three in all:

  1. The lag between the need for action and the recognition of this need (the recognition lag)

  2. The lag between recognition and the taking of action (the legislation lag)

  3. the lag between action and its effects (the implementation lag)

These delays mean that is it difficult to ascertain whether the effects of monetary policy changes in the recent past have finished taking effect.

Secondly, it is difficult to ascertain when proposed changes in monetary policy will take effect. Thirdly, feedbacks must be assessed. The magnitude of the monetary adjustment necessary to deal with the problem at hand is never obvious.

It is common for a central bank to act incrementally. The central bank makes small adjustments to monetary conditions over time as more information is available on the state of the economy and forecasts are updated.

Most discussions on monetary policy focus on the implementation lag. This lag depends on the fundamental characteristics of the economy.

A long and variable implementation lag means that it is difficult for central banks to ascertain what is happening now or forecast what will happen. Central banks may stimulate the economy after it is well on the way to recovery and tighten monetary policy when the economy is already going into a recession.

In his classic A Program for Monetary Stability, published in 1959, Milton Friedman summarised his empirical findings on length and variability of the lags on monetary policy:

on the average of 18 cycles, peaks in the rate of change in the stock of money tend to preceded peaks in general business by about 16 months and troughs in the rate of change in the stock of money to precede troughs in general business by about 12 months. For individual cycles, the recorded lead has varied between 6 and 29 months at peaks and between 4 and 22 months at troughs.

With lags as variable as those estimated by Friedman, it is difficult to see how any policy maker could know which direction to adjust his policy, much less the precise magnitude needed. Long lags greatly complicate good forecasting. A forecaster cannot know what the state of the economy will be when his policy takes effect.

Many Keynesians, Friedman notes, advocate “leaning against the wind.” By this they mean, in some sense, that the monetary (and fiscal) authorities should try to balance out the private sector’s excesses rather than passively hope that it adjusts on its own.

Friedman tested the Fed’s success at leaning “against the wind” by checking whether the rate of money growth has truly been lower during expansions and higher during contractions. He admits that this method of grading he Fed’s performance is open to criticism, but decides to go ahead and see what turns up. He finds that Fed has – for the periods surveyed – been unsuccessful.

By this criterion, for eight peacetime reference cycles from March 1919 to April 1958. Actual policy was in the ‘right’ direction in 155 months, in the ‘wrong’ direction in 226 months; so actual policy was ‘better’ than the [constant 4% rate of money growth] rule in 41% of the months.

Nor is the objection that the inter-war period biased his study is good since Friedman found that:

For the period after World War II alone, the results were only slightly more favourable to actual policy according to this criterion: policy was in the ‘right’ direction in 71 months, in the ‘wrong’ direct in 79 months, so actual policy was better than the rule in 47% of the months. [2]

One of the best ways to parry a metaphor is with another metaphor. Keynesians have a host of metaphors in their rhetorical arsenal; one frequently voiced is that a wise government should “lean against the wind” when choosing policy. Friedman counters:

We seldom know which way the economic wind is blowing until several months after the event, yet to be effective, we need to know which way the wind is going to be blowing when the measures we take now will be effective, itself a variable date that may be a half year or a year or two from now. Leaning today against next year’s wind is hardly an easy task in the present state of meteorology.

By scrutinising the practice of monetary policy over the decades, Friedman manages to produce objections that both Keynesians and non-Keynesians must take seriously. A key part of any response to Friedman rests on the ability of forecasters to do their jobs with tolerable accuracy.
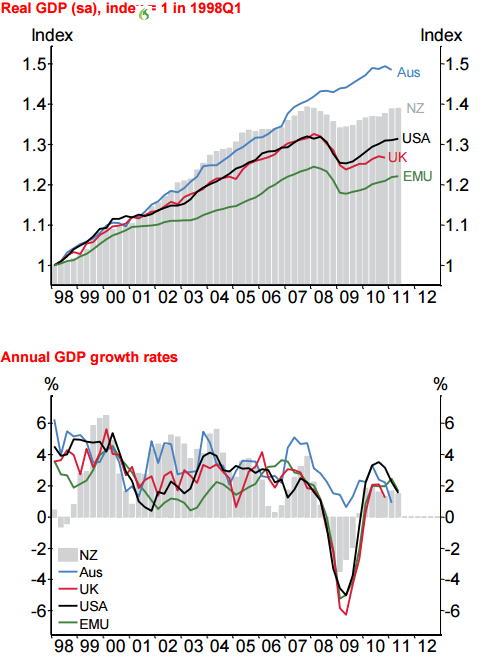
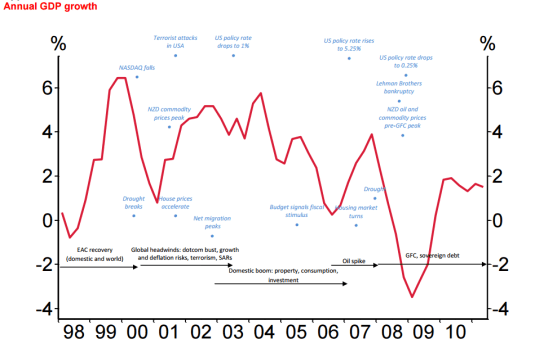
Recent New Zealand economic growth compared

Via Reserve Bank of New Zealand

Previous Older Entries Next Newer Entries

David Andolfatto

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Monetary Non-Neutrality

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Reason Magazine

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Coyote Blog

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Thoughts from the North

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Fardels Bear

A History of the Alt-Right

Vincent Geloso

Econ Prof at George Mason University, Economic Historian, Québécois

Bassett, Brash & Hide

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Truth on the Market

Scholarly commentary on law, economics, and more

The Undercover Historian

Beatrice Cherrier's blog

Matua Kahurangi

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Temple of Sociology

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Velvet Glove, Iron Fist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Why Evolution Is True

Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.

NoTricksZone

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Homepaddock

A rural perspective with a blue tint by Ele Ludemann

Kiwiblog

DPF's Kiwiblog - Fomenting Happy Mischief since 2003

The Dangerous Economist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Watts Up With That?

The world's most viewed site on global warming and climate change

The Logical Place

Tim Harding's writings on rationality, informal logic and skepticism

Doc's Books

A window into Doc Freiberger's library

The Risk-Monger

Let's examine hard decisions!

Uneasy Money

Commentary on monetary policy in the spirit of R. G. Hawtrey

Barrie Saunders

Thoughts on public policy and the media

Liberty Scott

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Point of Order

Politics and the economy

James Bowden's Blog

A blog (primarily) on Canadian and Commonwealth political history and institutions

Science Matters

Reading between the lines, and underneath the hype.

Peter Winsley

Economics, and such stuff as dreams are made on

A Venerable Puzzle

"The British constitution has always been puzzling, and always will be." --Queen Elizabeth II

The Antiplanner

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Bet On It

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

History of Sorts

WORLD WAR II, MUSIC, HISTORY, HOLOCAUST

Roger Pielke Jr.

Undisciplined scholar, recovering academic

Offsetting Behaviour

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

JONATHAN TURLEY

Res ipsa loquitur - The thing itself speaks

Conversable Economist

In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”

The Victorian Commons

Researching the House of Commons, 1832-1868

The History of Parliament

Articles and research from the History of Parliament Trust

Books & Boots

Reflections on books and art

Legal History Miscellany

Posts on the History of Law, Crime, and Justice

Sex, Drugs and Economics

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

European Royal History

Exploring the Monarchs of Europe

Tallbloke's Talkshop

Cutting edge science you can dice with

Marginal REVOLUTION

Small Steps Toward A Much Better World

NOT A LOT OF PEOPLE KNOW THAT

“We do not believe any group of men adequate enough or wise enough to operate without scrutiny or without criticism. We know that the only way to avoid error is to detect it, that the only way to detect it is to be free to inquire. We know that in secrecy error undetected will flourish and subvert”. - J Robert Oppenheimer.