There were 2,412 donations from Economists, in the last two election cycles. They gave 3 times as often to Democrats. http://t.co/c8tnQ9Vv15— Justin Wolfers (@JustinWolfers) June 03, 2015
Exactly one person identified themselves as a sociologist & gave money to Republicans (in the past 2 election cycles) http://t.co/JP9RAoRgiF— Justin Wolfers (@JustinWolfers) June 04, 2015
Bill English’s 2015 New Zealand Budget foreshadows a $1.5 billion allowance in the 2017 budget for “modest tax cuts”. Any reasonable mock-up of these tax cuts, such as in table 1 using the numbers on the Treasury website for revenue losses for small tax changes show that Prime Minster Key is planning his own fistful of dollars in the lead up to the 2017 election.
Table 1: hypothetical 2017 National Party tax cuts, $1.5 billion
Current tax rate
New tax rate
Revenue loss,
static scoring
Revenue loss,
dynamic scoring
33%
31.5%
$323m
$274m
30%
27.5%
$388m
$329.4m
17.5%
16.5%
$505m
$429.3m
Trust tax 33%
Trust tax 31.5%
$135m
$129m
Company tax rate 28%
27.5%
$113m
$90m
Total cost
$1.465b
$1251m
No serious participant in public policy debate could suggest that tax cuts of the size in table 1 will not have incentive effects that will lead to growth in incomes and business profits. There will be offsetting tax revenue increases that make a more ambitious tax package possible in 2017.
The Treasury’s website on revenue losses forecasts that a 1% increase in wages growth will increase tax revenue by $300 million. A 1% increase in the growth rate of taxable business profits will increase tax revenues by $140 million again according to the Treasury. These are big differences.
Any sensible discussion of the 2017 tax cuts should be against a background of what is called dynamic scoring to use the American parlance.
The Congressional Budget Office was recently required to use dynamic scoring when costing major tax policy proposals. New Zealand should follow this path.
Table 2 makes conservative assumptions about the behavioural effects of income tax cuts. I follow Mankiw, N. Gregory and Matthew Weinzierl “Dynamic Scoring: A Back-of-the-Envelope Guide,” Journal of Public Economics (September 2006): 1415-1433. They argue that, in the long run, about 17% of a cut in individual income taxes is recouped through higher economic growth. For a cut in company taxes, their figure is 50%. I assume 15% is recouped in this way for individuals, 20% for companies and 5% for trusts.
Table 2: hypothetical 2017 National Party tax cuts, $1.5 billion, dynamic scoring of revenue effects
Current tax rate
New tax rate
Revenue loss
static Scoring
Revenue loss
dynamic scoring
33%
31%
$430m
$366m
30%
27%
$465m
$395m
17.5%
16.5%
$505m
$429m
Trust tax 33%
Trust tax 31%
$180m
$171m
Company tax rate 28%
27%
$225m
$180m
Total cost
$1.805b
$1.541b
The $200-300 million in revenue increases from higher incomes and higher business profits incentivised by lower tax rates is not a trivial sum. It is enough on its own to cut one percentage point of the company tax rate. Spread around as in table 2, there are enough to knock another one-half of a percentage point of the top tax rate, the second top tax rate and the company tax rate. The $1.5 billion in tax cuts planned for 2017 will be neither modest in their size nor in their behavioural effects.
No budget should be published and no party in an election should assert that large changes in the tax system have no behavioural effects. Dynamic scoring makes a big difference to what scale of tax cuts are possible.
There are practical hurdles to dynamic scoring but static scoring has more important ones. The hurdles of dynamic scoring are:
Economists do not know how to accurately measure the growth effects of most policies
Dynamic scoring relies on less-than-accurate, theory-based macro models
The macro models undergirding dynamic scoring have numerous controversial and unproven built-in assumptions
The assumptions embedded in the macro models are not always carefully empirically based
Macro models exclude theoretically and empirically supported evidence of supply-side effects of public investment
Macro models exclude evidence-based effects of economic inequality
Macro models exclude evidence-based effects of numerous policies
Macro models provide different estimates of growth impacts of policy depending on guesses of how the policy may be finance
Against that is dynamic scoring removes the bias against pro-growth policies in current budgetary scoring:
[A] theoretical advantage of accurate dynamic scoring is that it is not biased against pro-growth policies compared to the current conventional scoring method. By ignoring macroeconomic effects, the conventional method overstates the true budgetary cost of pro-growth policies, such as infrastructure investments, and understates the cost of anti-growth policies.
To close on some New Zealand politics, Prime Minister Key, who is known as the smiling assassin, overtook the Labour Party and the Greens on their left In the 2015 Budget by increasing welfare benefits for the first time since 1972 in real terms, and by a large amount ($25 a week), and also increasing family tax credits.
Prime Minister Key well then pivot to the right in 2017 with a fistful of dollars to firmly camp himself over both the centre-left in the centre-right to be re-elected for a fourth term against an increasingly hapless and out-manoeuvred opposition.
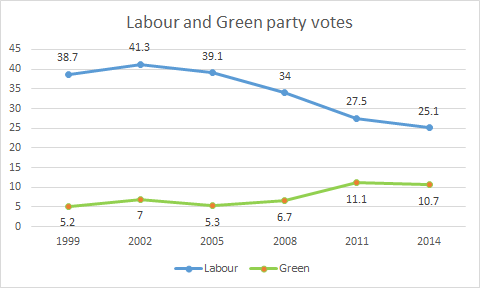
The New Zealand Greens have elected a new male co-leader. James Shaw is a first term MP who is supposed to consolidate and build the green vote from 10%. At the last election, the Greens were targeting a 15% party vote. Their vote fell from 11.1% to 10.7%.
I doubt that he can do it because much of the improvement of the Green vote since the 2005 election has been an expense of the Labour Party.
The Green vote was pretty sickly at 5-7% when the Labour Party was popular in government between 1999 and 2005. In the 2005 election, the Greens failed to reach the 5% party vote threshold necessary to win seats in Parliament on election night. It was only saved by absentee and postal votes that pushed its party vote up to 5.3%.
Maybe 30% of the Green vote, perhaps more, is made up of disgruntled Labour Party voters awaiting the call home. These disgruntled Labour voters will vote for the Labour Party again when it is fit for government.
Once there is a Labour–Green government in New Zealand, the Green vote faces the recurring theme that green parties lose a substantial part of their vote whenever they get into government such as happened federally in Australia and in Tasmania.
If the Greens go into government with about 7% of the party vote in the 2017 or 2020 New Zealand general elections, the Greens face the real prospect of of being voted out of Parliament completely in the 2023 New Zealand general election if their vote drops below 5%.
James Shaw happened to run for the Wellington Central electorate in the 2014 general election. He did not ask for the electorate vote in that election. Only the party vote.
Wellington Central has one of the highest green party votes in New Zealand. The Green party vote is 2000 more than Labour’s party vote in Wellington Central although the National Party won the party vote with 14,000 party votes.
Given the fact that the Greens may dropped below 5% by 2020, James Shaw would be wise to try to win Wellington Central in 2017 as a safety margin. If a party wins electorate seat under MMP, their party vote counts towards winning list MPs even if they win less than 5% of the party vote.
To add a twist to the tail, the deputy leader of the Labour Party, Grant Robertson, is the sitting member for Wellington Central with a margin of 8000 votes. If the current leader of the opposition fails at his job, Grant Robertson is his natural replacement.
There’s not much room at the top of the Labour Party list for defeated electoral seat candidates because of the last election Labour’s party vote was so low that it was only eligible for five list MPs. The last of these was the current leader of the opposition prove wasn’t even elected on election night but got back into Parliament on postal and absentee votes.
To complicate Grant Robinson’s golden parachute even further, the Labour Party has a policy that 50% of its caucus should be female by 2017 and the party list should be drawn up with that gender quota in mind. Grant Robertson may be a victim of this policy if he does not win Wellington Central.
More than a few careers hinge on the election of James Shaw as male co-leader of the Greens including the very survival of his party. It would be a tight race, but James Shaw could win Wellington Central.
Taylor’s basic point is economists have enough trouble working out what causes economic growth so trawling within that subset of causes to quantify the effects of rising or falling inequality inequality seems to be torturing the data to confess. The empirical literature is simply inconclusive as Taylor says:
A variety of studies have undertaken to prove a connection from inequality to slower growth, but a full reading of the available evidence is that the evidence on this connection is inconclusive.
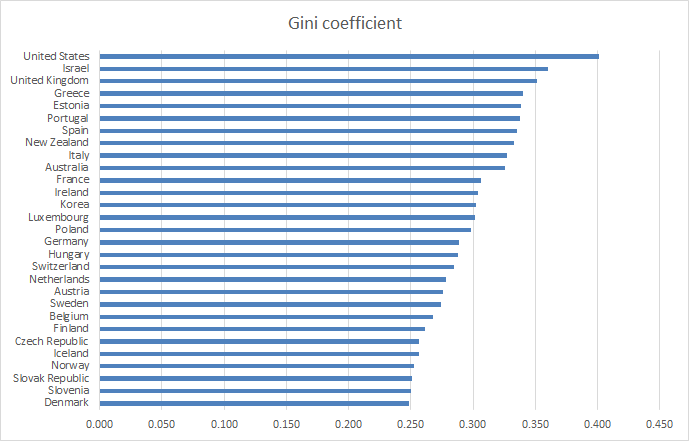
Most discussions of the link between inequality and growth are notoriously poor of theories connecting two. There are three credible theories in all listed in the OECD’s report:
The report first points out (pp. 60-61 that as a matter of theory, one can think up arguments why greater inequality might be associated with less growth, or might be associated with more growth. For example, inequality could result less growth if:
1) People become upset about rising inequality and react by demanding regulations and redistributions that slow down the ability of an economy to produce growth;
2) A high degree of persistent inequality will limit the ability and incentives of those in the lower part of the income distribution to obtain more education and job experience; or
3) It may be that development and widespread adoption of new technologies requires demand from a broad middle class, and greater inequality could limit the extent of the middle class.
About the best theoretical link between inequality and economic growth is what Taylor calls the "frustrated people killing the goose that lays the golden eggs." Excessive inequality within a society results in predatory government reactions at the behest of left-wing or right-wing populists.
Taylor refers to killing the goose that laid the golden egg as dysfunctional societal and government responses to inequality. He is right but that is not how responses to inequality based on higher taxes and more regulation are sold. Thomas Piketty is quite open about he wants a top tax rate of 83% and a global wealth tax to put an end to high incomes:
When a government taxes a certain level of income or inheritance at a rate of 70 or 80 percent, the primary goal is obviously not to raise additional revenue (because these very high brackets never yield much).
It is rather to put an end to such incomes and large estates, which lawmakers have for one reason or another come to regard as socially unacceptable and economically unproductive…
The left-wing parties don’t say let’s put up taxes and redistribute so that is not something worse and more destructive down the road. Their argument is redistribution will increase growth or at least not harm it. That assumes the Left is addressing this issue of not killing the goose that lays the golden egg at all.
Once you discuss the relationship between inequality and growth in any sensible way you must remember your John Rawls. Incentives encourage people to work, save and invest and channels them into the occupations where they make the most of their talents. Taylor explains:
In the other side, inequality could in theory be associated with faster economic growth if: 1) Higher inequality provides greater incentives for people to get educated, work harder, and take risks, which could lead to innovations that boost growth; 2) Those with high incomes tend to save more, and so an unequal distribution of income will tend to have more high savers, which in turn spurs capital accumulation in the economy.
Taylor also points out that the OECD’s report is seriously incomplete by any standards because it fails to mention that inequality initially increases in any poor country undergoing economic development:
The report doesn’t mention a third hypothesis that seems relevant in a number of developing economies, which is that fast growth may first emerge in certain regions or industries, leading to greater inequality for a time, before the gains from that growth diffuse more widely across the economy.
At a point in its report, the OECD owns up to the inconclusive connection between economic growth and rising inequality as Taylor notes:
The large empirical literature attempting to summarize the direction in which inequality affects growth is summarised in the literature review in Cingano (2014, Annex II).
That survey highlights that there is no consensus on the sign and strength of the relationship; furthermore, few works seek to identify which of the possible theoretical effects is at work. This is partly tradeable to the multiple empirical challenges facing this literature.
The OECD’s report responds to this inclusiveness by setting out an inventory of tools with which you can torture the data to confess to what you want as Taylor notes:
There’s an old saying that "absence of evidence is not evidence of absence," in other words, the fact that the existing evidence doesn’t firmly show a connection from greater inequality to slower growth is not proof that such a connection doesn’t exist.
But anyone who has looked at economic studies on the determinants of economic growth knows that the problem of finding out what influences growth is very difficult, and the solutions aren’t always obvious.
The chosen theory of the OECD about the connection between inequality and economic growth is inequality leads to less investment in human capital at the bottom part of the income distribution.
[Inequality] tends to drag down GDP growth, due to the rising distance of the lower 40% from the rest of society. Lower income people have been prevented from realising their human capital potential, which is bad for the economy as a whole
There are a few common patterns in economic growth. All high-income countries have near-universal K-12 public education to build up human capital, along with encouragement of higher education. All high-income countries have economies where most jobs are interrelated with private and public capital investment, thus leading to higher productivity and wages.
All high-income economies are relatively open to foreign trade. In addition, high-growth economies are societies that are willing to allow and even encourage a reasonable amount of disruption to existing patterns of jobs, consumption, and ownership. After all, economic growth means change.
In New Zealand, interest free student loans are available to invest in higher education as well as living allowances for those with parents on a low income. There are countries in Europe with low levels of investment in higher education but that’s because of high income taxes not because of inequality.
The OECD’s report is fundamentally flawed which is disappointing because most research from the OECD is to a good standard.
Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.
In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”
“We do not believe any group of men adequate enough or wise enough to operate without scrutiny or without criticism. We know that the only way to avoid error is to detect it, that the only way to detect it is to be free to inquire. We know that in secrecy error undetected will flourish and subvert”. - J Robert Oppenheimer.








Recent Comments