The major wars in American history
29 Jun 2015 Leave a comment
in politics - USA, war and peace Tags: war economy
Poverty rates in Canada, UK and USA since 1985
28 Jun 2015 Leave a comment
in labour economics, politics - USA, poverty and inequality, welfare reform Tags: British economy, Canada, top 1%
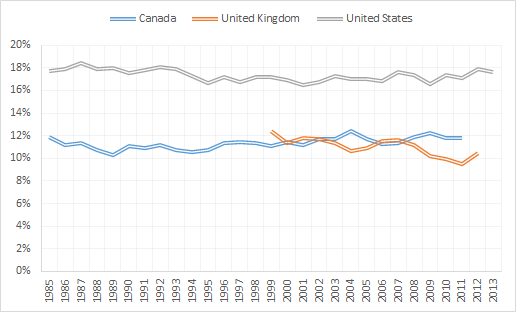
Despite 30 years of the ravages of neoliberalism, Reagan, Thatcher, and Blair, the whole lot, poverty has not gone up or down much at all.
Figure 1: relative poverty rate (% of persons living with less than 50% of equivalised disposable income), USA, UK and Canada
Source: In It Together – Why Less Inequality Benefits All – © OECD 2015
Creative destruction in house sizes
28 Jun 2015 Leave a comment
in economic history, politics - USA, urban economics Tags: creative destruction, the good old days, The Grade Enrichment
CHART: Today’s new homes are 1,000 square feet larger than in 1973, and average living space per person has doubled http://t.co/vdBTwWsygG—
Mark J. Perry (@Mark_J_Perry) June 27, 2015
A taxonomy of the Moon Landing hoax
28 Jun 2015 Leave a comment
in health economics, politics - USA Tags: conspiracy theories, conspiracy theorists, moon landing, moon landing hoax, political psychology, space
The different types of authoritarian personalities
28 Jun 2015 Leave a comment
in comparative institutional analysis, constitutional political economy, politics - Australia, politics - New Zealand, politics - USA, Public Choice Tags: antiforeign bias, antimarket bias, economics of personality traits, expressive voting, Leftover Left, makework bias, political psychology, rational ignorance, rational irrationality
How many congressmen are convicted of crimes?
27 Jun 2015 Leave a comment
in economics of crime, law and economics, occupational choice, politics - USA, Public Choice Tags: official corruption, political corruption
Donald Trump explained
27 Jun 2015 Leave a comment
in international economic law, international economics, politics - USA, Public Choice, rentseeking Tags: 2016 presidential election, antiforeign bias, antimarket bias, crony capitalism, Donald Trump, expressive voting, left-wing populists, populists, right-wing populists
All in less cash transfers average income tax rates at average wage, USA, UK, Australia and New Zealand
27 Jun 2015 Leave a comment
in labour supply, politics - Australia, politics - New Zealand, politics - USA, poverty and inequality, public economics Tags: Australia, British economy, family tax credits, family taxation, in-work tax credits, social insurance, taxation and the labour supply, welfare state
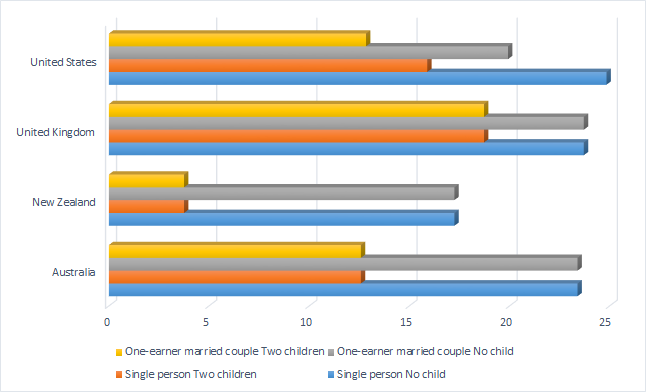
Figure 1: All in less cash transfers average income tax rates at average wage, 2014
Source: OECD tax database
The success of Indian migrants
27 Jun 2015 Leave a comment
Indians have become an extraordinarily successful minority in America. A burgeoning new elite econ.st/1cgD0GN http://t.co/XxwcclHpDJ—
The Economist (@EconEconomics) May 26, 2015
The share market speaks – Supreme Court’s Obamacare Decision Already Worth $3 Billion For Insurers
26 Jun 2015 Leave a comment
in financial economics, health economics, politics - USA Tags: events studies, Obamacare, share prices

via The Supreme Court’s Obamacare Decision Is Already Worth $3 Billion For Insurers | FiveThirtyEight.
Why is the Australian top 0.1% far less greedy than the UK, US and Canadian top 0.1%?
26 Jun 2015 Leave a comment
in economic history, entrepreneurship, human capital, labour economics, labour supply, Marxist economics, occupational choice, politics - Australia, politics - USA, poverty and inequality Tags: Australia, British economy, Canada, Leftover Left, top 0.1%, top 1%
Figure 1: top 0.1% share of gross income, Australia, UK, USA and Canada since 1946

Source: Chartbook of Economic Inequality.
The top 0.1% in Australia is earning not much more than it did in 1946. For most of the post-war period, the Australian top 0.1% earned less than what it earned in 1946. The only spike in the earnings of the Australian top 0.1% occurred after the top tax rate of 66% was reduced to 49% in 1986.
There were major cuts in the top tax rates in Australia,the USA and UK in the early 1980s. Figure 1 shows that these top tax rate cuts were matched with a spike in the earnings of the top 0.1% subsequent to those large tax cuts.
Banning Bottled Water: the Unintended Consequences.
26 Jun 2015 Leave a comment
in applied price theory, economics of regulation, health economics, politics - USA Tags: meddlesome preferences, nanny state, offsetting behaviour, The fatal conceit, The pretence to knowledge, unintended consequences
Starting in 2012, the University of Vermont began a process of requiring that all campus locations selling beverages provided 30% “healthy” beverages, and then that all locations phases out all sales of bottled water.
There were two hope: 1) reduced use of bottles, when bottled water was no longer available, and 2) that healthier beverages would be consumed.
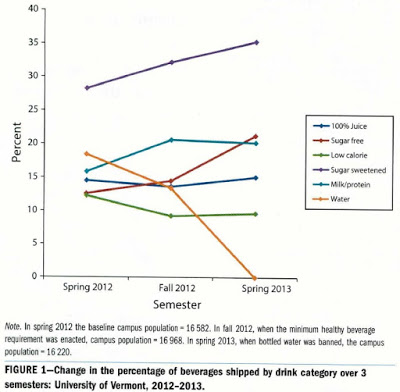
The orange line that drops to zero shows bottled water being phased out. The rising line at the top shows the rise in sugar-sweetened beverages. The red line in the middle that rises sharply shows the rise in sugar-free beverages.
via CONVERSABLE ECONOMIST: Banning Bottled Water: Unintended Consequences.
What Percentage of Your Country Smokes Marijuana?
25 Jun 2015 Leave a comment
in economics of crime, law and economics, liberalism, politics - Australia, politics - New Zealand, politics - USA Tags: marijuana decriminalisation, meddlesome preferences, nanny state
What Percentage of Your Country Smokes Marijuana?
priceonomics.com/what-percentag… http://t.co/t5ybdqNv4X—
Priceonomics (@priceonomics) April 21, 2015
"You didn’t build that" – which of sport superstars, celebrities and top CEOs earn their pay more?
25 Jun 2015 Leave a comment
in applied price theory, applied welfare economics, entrepreneurship, financial economics, industrial organisation, Marxist economics, politics - New Zealand, politics - USA, rentseeking, sports economics, survivor principle Tags: CEO pay, Leftover Left, obama, superstar wages, superstars, top 1%
Defenders have also pointed to the pay of pro ballplayers or Hollywood stars, but they do not determine their own pay (as CEOs do) and are paid based on performance. Once they begin to fail, they are dumped. By contrast, CEO pay isn’t tied to performance in any meaningful way.
It’s a big concession to say that athletes and celebrities earn their pay but top CEOs don’t. Most of all, that concession changes the case against the top 1% from inequality to just desert – a big shift in theories of distributive justice. It’s also a big risk to base the argument for greater equality and a 80% top tax rate not only on the excesses of CEOs but on the very specific and testable hypothesis that these CEOs determine their own pay.
if we are to look at CEOs, top athletes and Hollywood celebrities, it is the athletes and celebrities who benefited the most from the windfall of been able to service huge markets through the global media market.
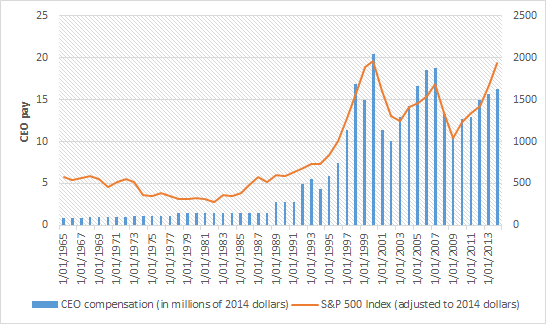
Figure 1: CEO pay and share market performance
Source: Economic Policy Institute.
CEOs actually have to run large complex companies to earn their pay, which is why their compensation tracks the share market relatively closely. Athletes and celebrities don’t do that what they do any better than in the past. They simply do it in front of a global media market. Since the late 1970s, the ratio of average pay of CEOs of large public companies to the average market value of those companies has stayed relatively constant: CEO pay grew hand in hand with corporations.
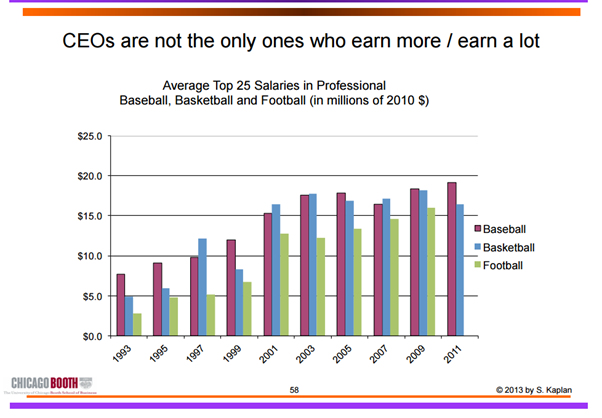
Steven Kaplan and Joshua Rauh make a number of basic points backed up by detailed evidence about CEO pay:
- While top CEO pay has increased, so has the pay of private company executives and hedge fund and private equity investors;
- ICT advances increase the pay of many – of professional athletes (technology increases their marginal product by allowing them to reach more consumers), Wall Street investors (technology allows them to acquire information and trade large amounts more easily), CEOs and technology entrepreneurs in the Forbes 400; and
- Technology allows top executives and financiers to manage larger organizations and asset pools – a loosening of social norms and a lack of independent control of CEO pacesetting does not explain similar increases in pay for private companies– technology explains it;
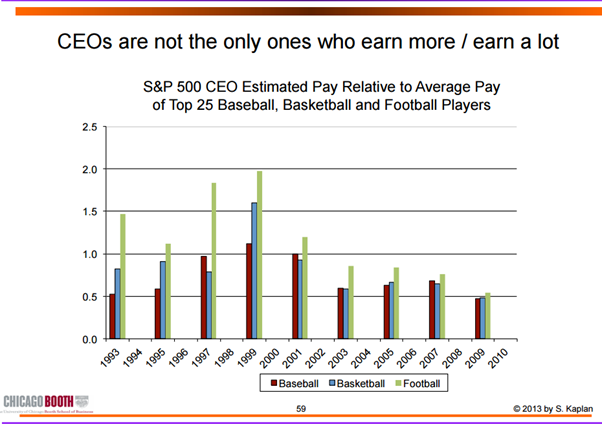
To put it simply:
If the reason for growth of incomes at the very top is, say, managerial power in publicly owned companies, then one would expect the increases in income at the top levels to be much larger for that group.
But the breadth of the occupations that have seen a rise in top income levels is much more consistent with the argument that the increase in “superstar” pay (or pay at the top) has been driven by the growth of information and communications technology, and the ways this technology allows individuals with particular skills that are in high demand to expand the scale of their performance.
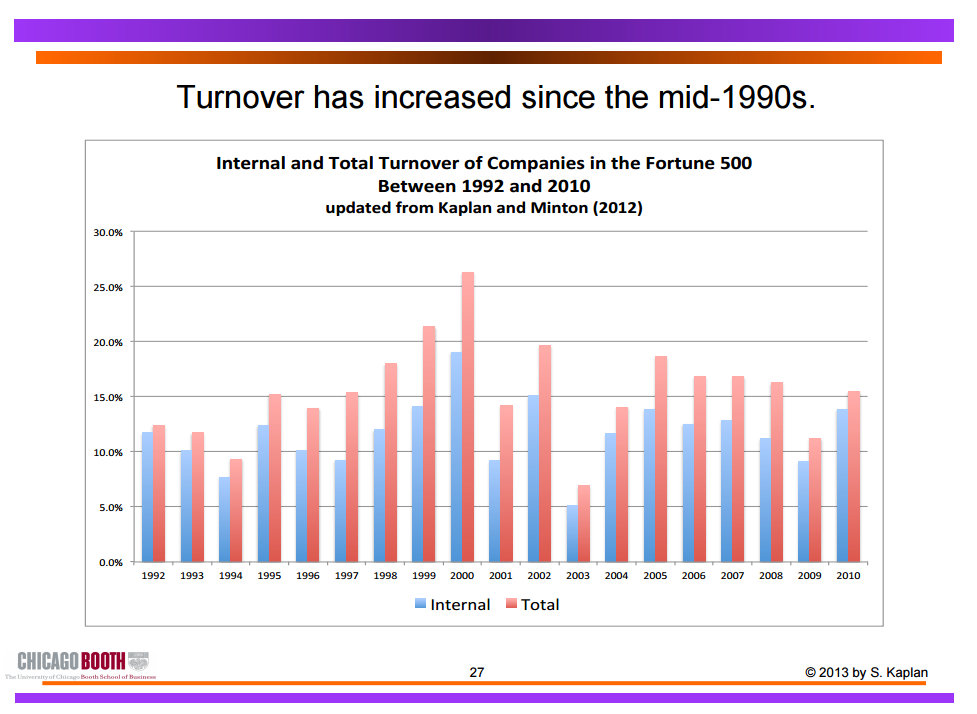
As for the turnover argument, that underperforming athletes and celebrities are dropped, prior to the GFC, CEO turnover was already on the rise:
Turnover is 14.9% from 1992 to 2005, implying an average tenure as CEO of less than seven years. In the more recent period since 1998, total CEO turnover increases to 16.5%, implying an average tenure of just over six years.
Internal turnover is significantly related to three components of firm performance – performance relative to industry, industry performance relative to the overall market, and the performance of the overall stock market.
Only 21.3% of CEOs in 1992 remained in that role in 1999; only 16.35% of CEOS on the job in 2000 were there in 2007. In any given year, one out of six Fortune 500 CEOs loses their jobs, compared to one out of 10 in the 1970s.
Dirk Jenter and Fadi Kanaan in a study of of 3,365 CEO turnovers from 1993 to 2009 found that:
CEOs are significantly more likely to be dismissed from their jobs after bad industry and, to a lesser extent, after bad market performance. A decline in industry performance from the 90th to the 10thpercentile doubles the probability of a forced CEO turnover.
In another study, Kaplan found that average CEO pay increased substantially during the 1990s, but declined by more than 30% from peak levels reached around 2000.
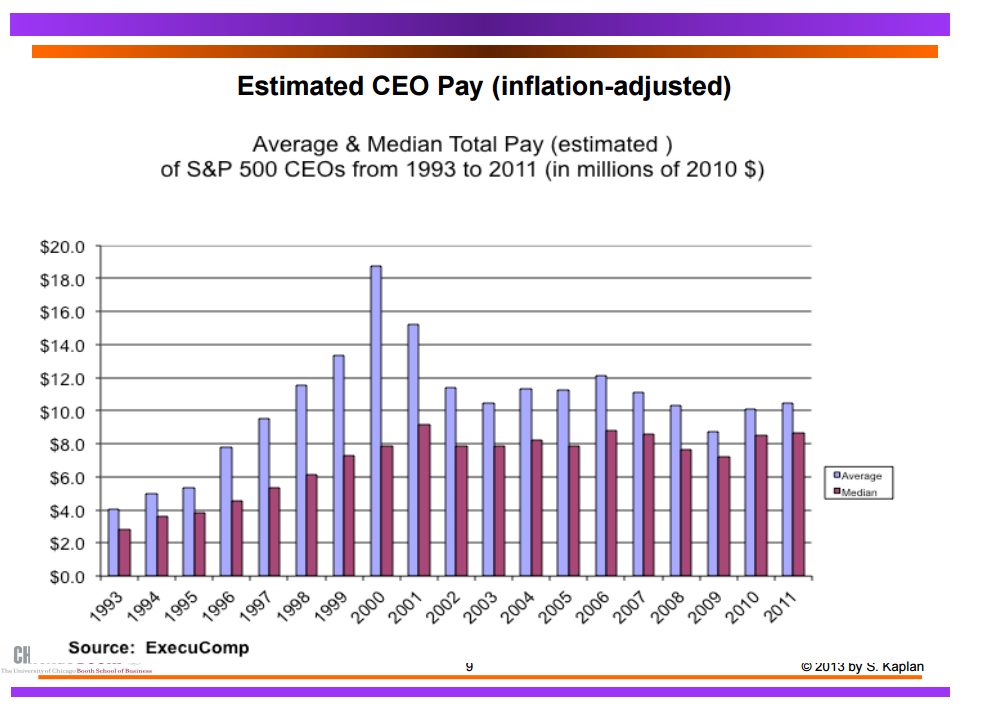
In addition, private company executives have seen their pay increase by at least as much as public companies. Private company executives with fewer agency problems have increased by more than public company executives. To close with another quote from Kaplan:
The point of these comparisons is to confirm that while public company CEOs earn a great deal, they are not unique. Other groups with similar backgrounds–private company executives, corporate lawyers, hedge fund investors, private equity investors and others—have seen significant pay increases where there is a competitive market for talent and managerial power problems are absent.
Again, if one uses evidence of higher CEO pay as evidence of managerial power or capture, one must also explain why these professional groups have had a similar or even higher growth in pay. It seems more likely that a meaningful portion of the increase in CEO pay has been driven by market forces as well.


Recent Comments