
The enormous (and, as of 2016, strangely downplayed) costs of Socialism: pic.twitter.com/VSP9UE4Ziz
— Jan Zilinsky (@janzilinsky) April 4, 2016
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
09 Apr 2016 Leave a comment
in applied price theory, applied welfare economics, development economics, economic history, growth disasters, growth miracles, law and economics, Marxist economics Tags: 2016 presidential election, British politics, collapse of communism, economics of socialism, Leftover Left
09 Apr 2016 Leave a comment
in applied price theory, applied welfare economics, development economics, growth disasters, growth miracles, industrial organisation, international economics, labour economics, labour supply, politics - USA Tags: 2016 presidential election, antiforeign bias, economics of immigration, left-wing popularism, Mexico, NAFTA, right-wing popularism, The Great Escape, trade agreements

08 Apr 2016 Leave a comment
in applied price theory, constitutional political economy, development economics, economic history, economics of bureaucracy, economics of crime, growth disasters, growth miracles, International law, law and economics, property rights, rentseeking
Tax havens and offshore financial centres are vital to the economic development of poor countries. There are plenty of countries, poor countries, where the ability to move funds offshore is fundamental to successful investment. That is missed in the reporting of the Panama Papers:
Consider the big names that have shown up so far on the list. With the notable exception of Iceland, these are not countries I would describe as “capitalist”: Russia, Pakistan, Iraq, Ukraine, Egypt. They’re countries where kleptocratic government officials amass money not through commerce, but through quasi-legal extortion, or siphoning off the till. This is an activity that has gone on long before capitalism, and probably before there was money.
Tax havens and offshore financial centres offer a way in which entrepreneurs can make an honest investment, secure a return and put it aside safely from the reach of the minister’s cousin who wants to muscle in once the business succeeded.
A major problem in poor countries is short time horizons for investment. Entrepreneurs must make their money quickly.
Many years ago there is a survey of entrepreneurs in Russia and Poland. It was in the early 1990s. Each was asked whether an investment project that doubled their money in two years was worth the risk. The Russian entrepreneurs mostly said no, the Polish entrepreneur said yes.
So insecure are the returns from investment in Russia at that time that the phenomenal returns were required before an investment was made. They would only invest if they could double the money in two years.
Many years ago, Mancur Olson wrote an insightful book about prosperity and dictatorships. He introduced the concept of rights intensive production.
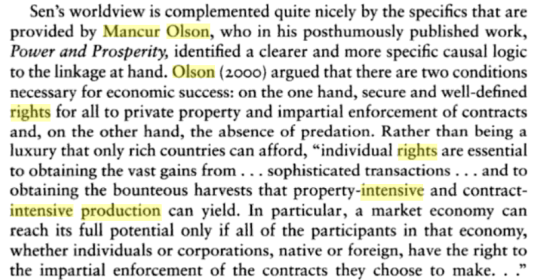
As countries become more and more developed, investment horizons lengthen and depends more and more upon the enforcement of contract and property rights in a tolerably honest way.
Instead of being the first entrepreneur to introduce the most basic technologies and profit handsomely, entrepreneurs are introducing a product upgrade or new product that is a minor improvement on current offerings. Such investments will take time to pay off.
In many developing countries, China as an example, property rights are insecure. One way to secure your investment is to take the proceeds offshore to a tax haven. If everything goes wrong, at least you got some nest egg overseas.
As many developing countries have corrupt politicians and dishonest courts, the way to secure gains from honest investments is to move some of the profits offshore. That is why tax havens are essential to poor countries growing richer.
One of the sources of Hong Kong prosperity was investors would deal with a Hong Kong-based company with the requisite political and economic links to China. They could enforce their contracts in China against their Hong Kong assets because the contract was based in Hong Kong under British law.
If the local legal system is inadequate, entrepreneurs well look overseas for mechanisms to force contracts and secure their returns on investments against confiscation.
08 Apr 2016 Leave a comment
in applied price theory, applied welfare economics, climate change, economics of regulation, environmental economics, global warming
05 Apr 2016 Leave a comment
02 Apr 2016 Leave a comment
in applied price theory, entrepreneurship, industrial organisation, managerial economics, survivor principle
31 Mar 2016 Leave a comment
in applied price theory, applied welfare economics, economics of media and culture, industrial organisation, international economics, politics - USA, Public Choice, public economics, rentseeking Tags: 2016 presidential election, antiforeign bias, antimarket bias, makework bias, pessimism bias, rational irrationality
31 Mar 2016 Leave a comment
in applied price theory, public economics Tags: capital gains tax, company tax, family tax credits, in-work tax credits, taxation and entrepreneurship, taxation and investment, taxation and labour supply
29 Mar 2016 Leave a comment
in applied price theory, applied welfare economics, labour economics, minimum wage Tags: living wage
The bleeding heart concerns of the Left for job losses from economic policy changes such as from trade liberalisation disappears as soon as they discuss the losers from a living wage increase.
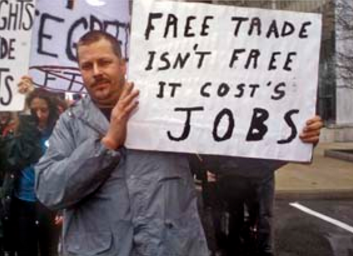
Instead of may the heavens may fall but a manufacturing job must not be lost from trade liberalisation, a brutal utilitarian calculus overtakes Noah Smith and the living wage movement about the small number of job losses that result from modest increases in the minimum wage.
Most are those who support the minimum wage shift gears their applied welfare economics in all other social context to emphasise how the losers should be given priority and greater weight when adding up the social gains and social losses of economic change.

The social cost of the minimum wage is not discussed in this way: how many jobs are lost and that these job losses are much more important than any gains to society.
All that is done is the number of jobs lost is compared with some other social metrics such as how much the wages go up for those that still have a job and that is enough to conclude that there is a socially beneficial change from a minimum wage increase.
Any low paid workers affected by the minimum wage increase are just reduced to numbers and added and subtracted with great ease and few moral compunctions about interpersonal comparisons of utility.

A minimum wage increase is not free if one worker loses their job. The Paretian Criterion states that welfare is said to increase or decrease if at least one person is made better off or worse off with no change in the positions of others.
As Rawls pointed out, a general problem that throws utilitarianism into question is some people’s interests, or even lives, can be sacrificed if doing so will maximize total satisfaction. As Rawls says:
[ utilitarianism] adopt[s] for society as a whole the principle of choice for one man… there is a sense in which classical utilitarianism fails to take seriously the distinction between persons.
Minimum wage advocates fail to take seriously that low paid workers who lose their jobs because of minimum wage increases are real living people who suffer when their interests are traded off for the greater good of their fellow low paid workers, some of whom come from much wealthier households.
It's pretty simple: Minimum Wage = Compulsory Unemployment http://t.co/6xiX6YCp9Z—
Mark J. Perry (@Mark_J_Perry) July 25, 2015
As Rawls pointed out, a general problem that throws utilitarianism into question is some people’s interests, or even lives, can be sacrificed if doing so will maximize total satisfaction. As Rawls says:
[ utilitarianism] adopt[s] for society as a whole the principle of choice for one man… there is a sense in which classical utilitarianism fails to take seriously the distinction between persons.
Minimum wage advocates fail to take seriously that low paid workers who lose their jobs because of minimum wage increases are real living people who suffer when their interests are traded off for the greater good of their fellow low paid workers, some of whom come from much wealthier households. Obviously the teenagers and adults thrown onto the scrapheap of society by an increased minimum wage don’t count in the brutal utilitarian calculus Noah Smith and the living wage movement employs.
27 Mar 2016 1 Comment
in applied price theory, financial economics, industrial organisation, managerial economics, organisational economics, survivor principle Tags: agency costs, agent principal problem, asymmetric information, dividends, entrepreneurial alertness, managerial slack
It is obvious that businesses find dividends sensible to pay because otherwise they will face disquiet from investors. Managers believe that higher dividends mean higher share prices.
Economists finds dividends to be a mysterious (Easterbrook 1984). Miller and Modigliani (1958) declared dividends to be irrelevant because investors can homebrew their own dividends by selling shares or borrowing against their share portfolios.
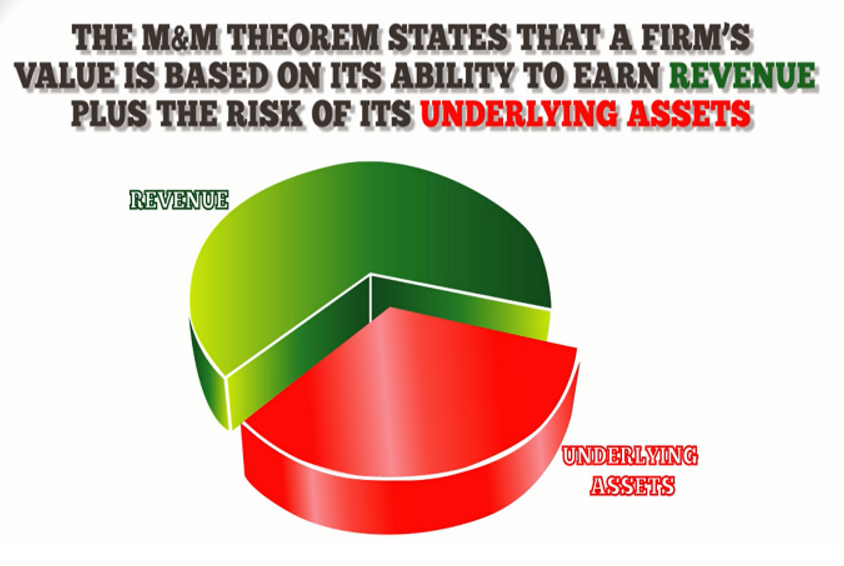
Modigliani (1980, p. xiii) explains the Miller and Modigliani Theorem as follows:
… with well-functioning markets (and neutral taxes) and rational investors, who can ‘undo’ the corporate financial structure by holding positive or negative amounts of debt, the market value of the firm – debt plus equity – depends only on the income stream generated by its assets.
It follows, in particular, that the value of the firm should not be affected by the share of debt in its financial structure or by what will be done with the returns – paid out as dividends or reinvested (profitably).
Warren Buffett has never paid a dividend. He only agreed to a stock split. Shareholders pressed him to do so. They wanted to bequeath their shares to children without having to sell them.
What is even more mysterious is a simultaneous existence of dividends and the raising of new capital, either through the share market or from borrowing (Easterbrook 1984).
Dividends are costly and ubiquitous so something causes them. Even if investors were irrational, dividends would go away if there cost exceeds their benefits.
If dividends were a bad idea, firms that pay few dividends would prosper relative to others; investors who figure out the truth would also prosper relative to others and before long dividends will be features of failing firms (Easterbrook 1984).

Dividends exist because they influence the firms financing policies. Dividends dissipate free cash and thereby induce the firm to float new shares and borrow. If the firm is constantly in the market for new capital, it must constantly prove the value of the investment to the market (Easterbrook 1984).
The interests and incentives of managers and shareholders frequently conflict over the optimal size of the firm and paying free cash flows as dividends. Jensen (1986) defines free cash flow as follows:
Free cash flow is cash flow in excess of that required to fund all of a firm’s projects that have positive net present values when discounted at the relevant cost of capital. Such free cash flow must be paid out to shareholders if the firm is to be efficient and to maximize value for shareholders (Jensen 1986, p. 323).
The problem is how to motivate managers to pay out this cash rather than invested at below the cost of the capital. By issuing debt, managers bind themselves to pay out future cash flows in a way that a future dividend policy cannot.
Creditors can take the firm into bankruptcy court if they do not repay. Investors and bankers play an important role in monitoring the firm and its proposed projects.
The control function of debt is more important in organisations with large cash flows but low growth prospects. Investors in the share market are alert to the control function of debt. Most leverage increasing transactions result in positive increases in share prices while most transactions that reduce leverage results in share price falls (Jensen 1986).
There is nothing new about using high debt leverage ratios to create greater business value through limiting managerial discretion in focusing entrepreneurial attention on the bottom line.
One of the driving forces behind management leverage buyouts in the 1980s was that they borrowed to take over a company to run it better. The high levels of debt in management buyouts made sure that there was no incentives to tolerate waste or inefficiency or underperforming divisions or product lines of the firm. Any slack with the organisation would very quickly be punished perhaps in bankruptcy. Heavy debt ratios focused the attention of managers and boards of directors.

New debt puts managers under additional scrutiny of a range of bankers and the share market, which is the principal reason for keeping firms constantly in the market for capital. Managers of firms that do not have to go into the market repeatedly and regularly for new capital have more discretion to behave in their own interest rather than those of investors (Easterbrook 1984). The function of dividends is to keep firms in the capital market.
Managers of firms with unused borrowing power and large free cash flows are more like to undertake expansions that are less profitable. The burst of takeovers and leverage buyouts in the 1980s were very much driven by opportunities to profit from reducing corporate slack and downsizing flabby corporate headquarters of large publicly listed companies (Jensen 1986).
Dividends reduce the resources under managers’ control and subjecting them to the monitoring by the capital markets that occurs when a firm must obtain new capital. Financing projects internally avoids this monitoring and the possibility that funds will be unavailable or available only at high explicit prices. Project finance replicates the disciplinary effect of paying regular dividends by borrowing a huge amount at the start of the project. High debt prevents management wasting resources on low return projects.
Dividends are paid by companies to tie the hands of management. Dividends make sure that there is less free cash about for them to spend on projects at their own discretion. When a major expansion must be undertaken, the management of a company must either go to the share market or banks for it to go forward. This means multiple set of decision-makers agree that it is a worthwhile project and provide funding.
The art of business is identifying assets in low-valued uses and devising ways to profitably move them into higher values uses (Froeb and McCann 2008). Wealth is created when entrepreneurs move assets to higher-valued uses.
Froeb and McCann (2008) argued that mistakes are made – business opportunities are missed – for one of two reasons:
1. A lack of information; or
2. Bad incentives.
Rational, self-interested actors err because either they do not have enough information to make better decisions, or they lack incentives to make the best use of information they already have.
Froeb and McCann (2008) argued that three questions arise about all business problems:
1. Who is making the bad decision?
2. Does the decision maker have enough information to make a good decision?
3. Does the decision maker have the incentives to make a good decision?
For Froeb and McCann (2008), the answers to these questions immediately suggest ways to fix them:
1. Let someone else make the decision;
2. Give more information to the decision maker; or
3. Change the decision makers’ incentives.
Dividends follow all three points in this matrix. Dividends include others in investment and expansion decisions of the company. These bankers or new share investors must be given more information on the merits of the new or enlarged project.
The project will not go ahead and any benefits to the careers of the executives championing it will not be forthcoming unless they can persuade these outside parties with plenty of other investment options of the merits of the project.
Dividend show that the market process as well alert to the risks of separating ownership from control. Counter strategies are developed to channel the efforts and align the interests of management teams towards those of investors and owners.
The ownership structure and dividend policies of firms arise out of the search for the capital structure that maximises profits. Different divisions of risk between creditors and shareholders and decision-making rights between owners, boards of directors and managers all affect the value and profitability of a firm. Dividends contribute to that search more profitable forms of organisation by restricting free cash flows in the hands of management.
24 Mar 2016 Leave a comment
in applied price theory, applied welfare economics, industrial organisation, law and economics, property rights Tags: externalities
It takes three to have an externality.
19 Mar 2016 Leave a comment
in applied price theory, applied welfare economics, economics, economics of education, human capital, labour economics, labour supply, poverty and inequality Tags: James Heckman
18 Mar 2016 Leave a comment
in applied price theory, economics, public economics Tags: tax incidence
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
A History of the Alt-Right
Econ Prof at George Mason University, Economic Historian, Québécois
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Scholarly commentary on law, economics, and more
Beatrice Cherrier's blog
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
A rural perspective with a blue tint by Ele Ludemann
DPF's Kiwiblog - Fomenting Happy Mischief since 2003
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
The world's most viewed site on global warming and climate change
Tim Harding's writings on rationality, informal logic and skepticism
A window into Doc Freiberger's library
Let's examine hard decisions!
Commentary on monetary policy in the spirit of R. G. Hawtrey
Thoughts on public policy and the media
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Politics and the economy
A blog (primarily) on Canadian and Commonwealth political history and institutions
Reading between the lines, and underneath the hype.
Economics, and such stuff as dreams are made on
"The British constitution has always been puzzling, and always will be." --Queen Elizabeth II
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
WORLD WAR II, MUSIC, HISTORY, HOLOCAUST
Undisciplined scholar, recovering academic
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Res ipsa loquitur - The thing itself speaks
In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”
Researching the House of Commons, 1832-1868
Reflections on books and art
Posts on the History of Law, Crime, and Justice
Celebrating humanity's flourishing through the spread of capitalism and the rule of law
Exploring the Monarchs of Europe
Cutting edge science you can dice with



Recent Comments