Institutional Economics: Robert Shiller, Ex-Ante and Ex-Post

In his 2009 book with George Ackerlof, Robert Shiller, who shared a Nobel  Prize in economics for his work developing behavioural finance wrote:

there has been one way, at least in the past, in which almost everyone could become at least moderately rich

… Invest it for the long term in the stock market, where the rate of return after adjustment for inflation has been 7% per year’

Shiller’s ex-post observations on stock market returns in 2009 do not sit well with his ex-ante prediction in 1996:

long run investors should stay out of the market for the next decade.

via Institutional Economics: ‘Light Reading It’s Not’ – Forbes.

The joint advice of both the efficient market advocates such as Eugene Fama and the behavioural finance theorists on how to manage your retirement and other long-term savings are the same:

Buy and hold. Diversify. Put your money in index funds.

Pay attention to the one thing you can control–costs–and keep them as low as possible.

Index-linked or passive investment funds minimise their trading of shares and do not hire research departments so their costs and fees are far lower than investments funds that trade actively in the market trying to beat the market.

About 97% of these active funds fail to beat the market. The rest may just have been lucky.

  • The average actively managed investment must underperform the indexed investment when all costs are deducted.
  • The actively managed investments that beat the indexed investments this year fail to consistently beat the index in the future.

Investors can win higher returns by shouldering more risk and all that entails, and the reward for bearing risk vary over time and across assets.

Old macroeconomic fallacies never die, they just wait for the next recession

Thomas Kuhn’s Structure of Scientific Revolutions showed that sciences do not march onwards and upwards towards the light. Kuhn found that once a central paradigm is selected, there is no testing or sifting, and tests of basic assumptions only take place after accumulated failures and anomalies in the ruling paradigm plunge the science into a crisis.

Scientists do not give up the failing paradigm until a new paradigm arrives, which resolves the failures and anomalies that caused the crisis. It takes a theory to beat a theory.

Murray Rothbard, when discussing Kuhn, pointed to economics is an example of a science which moves in a zigzag fashion, with old fallacies sometimes elbowing aside earlier but sounder paradigms.

Thomas Humphrey wrote an excellent 250-year long literature surveys of both the rules versus discretion debate and the cost-push theories of inflation in the 1998 and 1999 Richmond Fed Quarterly.

Humphrey wrote the reviews to see if economics was a progressive science in the sense that superior new ideas relentlessly supplant inferior old ones.

Humphrey showed that policy rules were popular in good times to contain inflation, and when unemployment was rising, discretionary policies returned to vogue. The policy debate keeps recycling because

  1. people forget the lessons of the past; and
  2. For better or worse, politicians and the public have tended to believe that central banks, the focus of his studies, have the power to boost output, employment, and growth permanently.

Mercantilists, with their fears of hoarding and scarcity of money together with their prescription of cheap (low interest rates) and plentiful cash as a stimulus to real activity, tend to gain the upper hand when unemployment is the dominant problem.

Classicals, chanting their mantra that inflation is always and everywhere a monetary phenomenon, tend to prevail when price stability is the chief policy concern.

Cost-push fallacies about inflation were even more resilient against repeated refutations.

There is nothing new under the sun in macroeconomics. The same issues that divided twentieth-century monetarists and non-monetarists as well as current macroeconomists were discussed by everyone from David Hume (1752) to Knut Wicksell (1898) and in the Bullionist-Anti-Bullionist and the Currency School-Banking School controversies:

  • rules v. discretion,
  • inflation as a monetary v. real cost push phenomenon,
  • direct v. inverse money-to-price causality,
  • central bank-determined v. market demand-determined money stocks,
  • exogenous v. endogenous money, and
  • backing v. supply-and-demand theories of money’s value

Current macroeconomists and monetary economists often unaware of the eighteenth and nineteenth-century origins of the ideas they employ.

Barro (1989) “New Classicals and New Keynesians, or the Good Guys and the Bad Guys”, made the point that Keynesian macroeconomics does not seek out new theoretical results for testing; rather the aim is to provide respectability for the basic viewpoints and policy stances of the old Keynesian models.

Bellante (1992) likewise, noted that the search in Keynesian economics for microeconomic foundations is to blunt criticism, rather than because it is otherwise useful. The analytical apparatus may change, but the policy conclusions remain the same.

Policy Consistency and the Growth of Nations Finn Kydland


Favourite Lucas and Sargent quotes

Lucas and Sargent from After Keynesian Macroeconomics (1979):

For policy, the central fact is that Keynesian policy recommendations have no sounder basis, in a scientific sense, than recommendations of non-Keynesian economists or, for that matter, non-economists

Thomas J. Sargent

Robert Lucas from Tobin and Monetarism: A Review Article (1981):

Keynesian theory is in deep trouble, the deepest kind of trouble in which an applied body of theory can find itself: It appears to be giving seriously wrong answers to the most basic questions of macroeconomic policy.

Proponents of a class of models which promised 3 to 4 per cent unemployment to a society willing to tolerate annual inflation rates of 4 to 5 per cent have some explaining to do after a decade such as we have just come through.

A forecast error of this magnitude and central importance to policy has consequences, as well it should.

We got the high-inflation decade, and with it as clear-cut an experimental discrimination as macroeconomics is very likely to see, and Friedman and Phelps were right.

Haberler, Jacob Viner, Robertson, Pigou and Frank Knight pointed out in their reviews of the General Theory that it lacked originality, and presented old ideas often incorrectly in confusing new vocabularies that made the book difficult to read. These reviews are worth reading today such as this by Frank Knight:

Many of Mr. Keynes’s own doctrines are, as he would proudly admit, among the notorious fallacies to combat which has been considered a main function of the teaching of economics.

Tom Sargent’s 12 lessons from economics for public policy

Tom Sargent is a life-long Democrat who is old enough to remember when Democrats were fiscal conservatives.

At a graduation speech at Berkeley, Sargent listed these lessons:

    1. Many things that are desirable are not feasible.
    2. Individuals and communities face trade-offs.
    3. Other people have more information about their abilities, their efforts, and their preferences than you do.
    4. Everyone responds to incentives, including people you want to help. That is why social safety nets don’t always end up working as intended.
    5. There are trade-offs between equality and efficiency.
    6. In an equilibrium of a game or an economy, people are satisfied with their choices. That is why it is difficult for well-meaning outsiders to change things for better or worse.
    7. In the future, you too will respond to incentives. That is why there are some promises that you’d like to make but can’t. No one will believe those promises because they know that later it will not be in your interest to deliver. The lesson here is this: before you make a promise, think about whether you will want to keep it if and when your circumstances change. This is how you earn a reputation.
    8. Governments and voters respond to incentives too. That is why governments sometimes default on loans and other promises that they have made.
    9. It is feasible for one generation to shift costs to subsequent ones. That is what national government debts and the U.S. social security system do (but not the social security system of Singapore).
    10. When a government spends, its citizens eventually pay, either today or tomorrow, either through explicit taxes or implicit ones like inflation.
    11. Most people want other people to pay for public goods and government transfers (especially transfers to themselves).
    12. Because market prices aggregate traders’ information, it is difficult to forecast stock prices and interest rates and exchange rates

Uncertainty and Ambiguity in American Fiscal and Monetary Policies – Tom Sargent

Macroeconomic forecasting has had a turbulent history

Most early discussions argued against econometric forecasting in principle:

  • Forecasting was not properly grounded in statistical theory,
  • It presupposed that causation implies predictability, and
  • The forecasts themselves were invalidated by the reactions of economic agents to them.

A long tradition argued that social relationships were too complex, too multifarious and too infected with capricious human choices to generate enduring, stable relationships that could be estimated.

These objections came before Hayek’s point that much of all social knowledge is not capable of summation in statistics or even language.
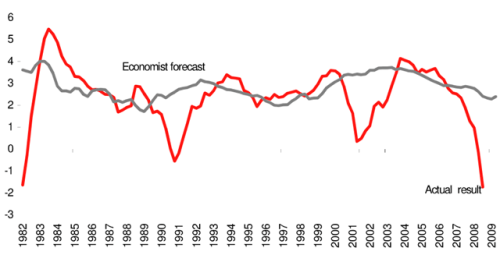
The limitations of forecasting are well-known. Forecasts are conditional on a number of variables; there are important unresolved analytical differences about the operation of the economy; and large uncertainties about the size and timing of responses to macroeconomic changes. Shocks to the output, prices, employment and other variables are partly permanent and partly transitory.

At the practical level, forecasting requires that there are regularities on which to base models, such regularities are informative about the future and these regularities are encapsulated in the selected forecasting model.

We have very little reliable information about the distribution of shocks or about how the distributions change over time. Forecast errors arise from changes in the parameters in the model, mis-specification of the model, estimation uncertainty, mis-measurement of the initial conditions and error accumulation.

In the 1980s, data mining and publications bias were so strong and statistical inferences were so fragile that Ed Leamer’s 1983 Let’s Take the Con out of Econometrics paper made up-and-coming applied economists despair for their professional field and for their own careers:

The econometric art as it is practiced at the computer terminal involves fitting many, perhaps thousands, of statistical models. One or several that the researcher finds pleasing are selected for reporting purposes.

This search for a model is often well intentioned, but there can be no doubt that such a specification search invalidates the traditional theories of inference….

[A]ll the concepts of traditional theory…utterly lose their meaning by the time an applied researcher pulls from the bramble of computer output the one thorn of a model he likes best, the one he chooses to portray as a rose.

… This is a sad and decidedly unscientific state of affairs we find ourselves in.

Hardly anyone takes data analyses seriously.

Or perhaps more accurately, hardly anyone takes anyone else’s data analyses seriously.

Like elaborately plumed birds who have long since lost the ability to procreate but not the desire, we preen and strut and display our t-values [which measure statistical significance].

Leamer still doubts the progress towards techniques that separate sturdy from fragile inferences. Economists by and large simply do not want to hear that they cannot make major conclusions from the data sets. But not that they really do, but that is for a forthcoming post.

Before the great moderation spread wide, Brunner and Meltzer found that in the 1970s and 1980s, the 95% confidence intervals on next year’s forecasts for Gross Domestic Product and the Consumer Price Index are such that government and private forecasters in the USA and Europe could not distinguish between a recession and a boom, nor say whether inflation will be zero or ten per cent.

A review this week by Ahir and Lounganishows found that recent forecasting by the private and public sector has not improved:

none of the 62 recessions in 2008–09 was predicted as the previous year was drawing to a close.

Figure 1. Number of recessions predicted by September of the previous year

Source: Ahir and Loungani 2014, “There will be growth in the spring”: How well do economists predict turning points?” http://www.voxeu.org/

A policy-maker who adjusts policy based on forecasts for the following year has little reason to be confident that he has changed policy in the right direction.

While at graduate school, I wrote what was published as Official Economic Forecasting Errors in Australia 1983-96.

Australian Treasury forecasting errors were so large relative to the mean annual rate of change in real GDP and the inflation rate that, on average, forecasters could not distinguish slow growth from a deep recession or stable prices from moderate inflation.

The biography of Paul Keating by Edwards suggested that the Government of the day was well aware of the poor value of forecasts. So much so that forecasts may not have actually played a significant role in monetary policy making in Australia in the late 1980s onwards. John Stone said this to Keating when he assumed office as Treasurer in 1983:

As you know, we (and I in particular) have never had much faith in forecasting.

Not infrequently, our forecasts turn out to be seriously wrong.

… We simply do the best we can, in as professional manner as we can — and, if it is any consolation, no one seems to be able to do any better, at least in the long haul.

We always emphasize the uncertainties that attach to the forecasts — but we cannot ensure that such qualifications are heeded and plainly they often are not

To cast my results in Milton Friedman’s nomenclature for monetary lags, the recognition lag on a forecasting based monetary policy appears to be infinite because forecasters do not know if there will be a recession or 10% inflation afoot when their monetary policy changes take hold in 18 to 24 months.
Was the global economic crisis unforeseen?

Plenty of people warned of dark days ahead. An essay anyone can read with profit is Ross Levine’s "An Autopsy of the U.S. Financial System: Accident, Suicide, or Negligent Homicide?"

The paper studies five important policies:

  • Securities and Exchange Commission (SEC) policies toward credit rating agencies,
  • Federal Reserve policies concerning bank capital and credit default swaps,
  • SEC and Federal Reserve policies about over-the-counter derivatives,
  • SEC policies toward the consolidated supervision of major investment banks, and government policies toward Fannie Mae and Freddie Mac.

Levine concludes that

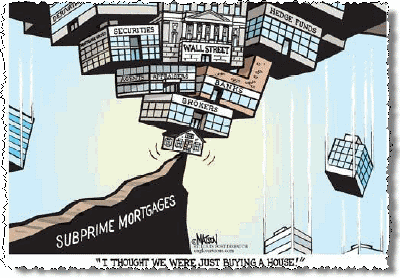
  • The evidence is inconsistent with the view that the collapse of the financial system was caused only by the popping of the housing bubble ("accident") and the herding behaviour of financiers rushing to create and market increasingly complex and questionable financial products ("suicide").
  • Rather, the evidence indicates that senior policymakers repeatedly designed, implemented, and maintained policies that destabilized the global financial system in the decade before the crisis.
  • Moreover, although the major regulatory agencies were aware of the growing fragility of the financial system due to their policies, they chose not to modify those policies, suggesting that "negligent homicide" contributed to the financial system’s collapse
  • Although influential policymakers presumed that international capital flows, euphoric traders, and insufficient regulatory power caused the crisis, the paper shows that these factors played only a partial role.
  • Current reforms represent only a partial and incomplete step in establishing a stable and well-functioning financial system.
  • Since systemic institutional failures helped cause the crisis, systemic institutional reforms must be a part of a comprehensively effective response.

The most interesting morsels are:

  • The New York Times warned in 1999 that Fannie Mae was taking on so much risk that an economic downturn could trigger a “rescue similar to that of the savings and loan industry in the 1980s,” and again emphasized this point in 2003; and
  • Alan Greenspan testified before the Senate Banking Committee in 2004 that the increasingly large and risky GSE portfolios could have enormously adverse ramifications! A rare occasion on which Greenspan did not talk in riddles.


Stern and Feldman’s Too Big to Fail in 2004 used insights gleaned from the formal economic literature to frame warnings in 2004 about the time bomb for a financial crisis set by current regulations and government promises.

The prediction of the Kareken and Wallace moral hazard model of deposit insurance is if a government sets up deposit insurance and doesn’t regulate bank portfolios to prevent them from taking too much risk, the government is setting the stage for a financial crisis. If financial intermediaries do not bear the full consequences of their actions (because they are insured) then profit maximising portfolios will be too risky. The Kareken-Wallace model makes you very cautious about lender-of-last-resort facilities and very sensitive to the risk-taking activities of banks.

Tom Sargent said that Jose Scheinkman made a list of the ten academic papers that the Reagan administration should have looked at. Number one on his list was Kareken and Wallace.

The idea that deposit insurance leads to more financial crises even troubled FDR before he signed the 1934 U.S. bill to introduce deposit insurance.

Robert Lucas and Edward Prescott discuss the future of economic growth, 2014

On 21 March, Robert E. Lucas Jr., and Edward C. Prescott participated in a roundtable on “The Wealth of Nations in the 21st Century” in Barcelona.


via Chong-En Bai, Robert Lucas, Edward Prescott discuss economic growth in Barcelona – Barcelona GSE.

The rise of the Swedish welfare state, Swedosclerosis and Director’s Law

Sweden is a common example of a generous welfare state that is compatible with a prosperous society. One interpretation of the UN Development Index is you improve your national ranking by becoming more like Sweden.

Assar Lindbeck has shown time and again in the Journal of Economic Literature and elsewhere that Sweden became a rich country before its highly generous welfare-state arrangements were created

Sweden moved toward a welfare state in the 1960s, when government spending was about equal to that in the United States – less that 30% of GDP.

Sweden could afford this at the end of the era that Lindbeck labelled ‘the period of decentralization and small government’. Sweden was one of the fastest growing countries in the world between 1870 and 1960.

Swedes had the third-highest OECD per capita income, almost equal to the USA in the late 1960s, but higher levels of income inequality than the USA.

By the late 1980s, Swedish government spending had grown from 30% of gross domestic product to more than 60% of GDP. Swedish marginal income tax rates hit 65-75% for most full-time employees as compared to about 40% in 1960.

Swedish economists named the subsequent economic stagnation Swedosclerosis:

  • Economic growth slowed to a crawl in the 1970s and 1980s.
  • Sweden dropped from near the top spot in the OECD rankings to 18th by 1998 – a drop from 120% to 90% of the OECD average inside three decades.
  • 65% of the electorate receive (nearly) all their income from the public sector—either as employees of government agencies (excluding government corporations and public utilities) or by living off transfer payments.
  • No net private sector job creation since the 1950s, by some estimates!

In 1997, Lindbeck suggested that the Swedish Experiment was unravelling.


Sweden is a classic example of Director’s Law of Public Expenditure. Once a country becomes rich because of capitalism, politicians look for ways to redistribute more of this new found wealth.

Studies starting from Sam Peltzman (1980) showed that government grew in line with the growth in the size and homogeneity of the middle class that became organised and politically articulate enough to implement a version of Director’s law. Director’s law augmented by Gary Becker’s 1983 model of competition among pressure groups for political influence explain much of modern public policy.

Government spending grew in many countries in the mid-20th century because of demographic shifts, more efficient taxes, more efficient spending, shifts in the political power from those taxed to those subsidised, shifts in political power among taxed groups, and shifts in political power among subsidised groups.

The Swedish economic reforms from after 1990 economic crisis and depression are an example of a political system converging onto more efficient modes of income redistribution as the deadweight losses of taxes on working and investing and subsidies for not working both grew. Improvements in the efficiency of taxes or spending reduce political pressure to suppress the growth of the welfare state and thus increase or prevent cuts to both total tax revenue and spending.

After the rise of Swedosclerosis, the taxed, regulated and subsidised groups had an increased incentive to converge on new lower cost modes of redistribution. More efficient taxes, more efficient spending, more efficient regulation and a more efficient state sector reduced the burden of taxes on the taxed groups. Most subsidised groups benefited as well because their needs were met in ways that provoked less political opposition.

Reforms ensued led by parties on the Left and Right, with some members of existing political groupings benefiting from joining new political coalitions.

The Nordic median voter was alive to the power of incentives and to not killing the goose that laid the golden egg. The deadweight losses of taxes, transfers and regulation limit inefficient policies and the sustainability of redistribution.

For example, while tax rates are high in Sweden and the rest of Scandinavia, hours worked in Scandinavia are significantly higher than in Continental Europe.

Richard Rogerson found in Taxation and market work: is Scandinavia an outlier? that how the government spends tax revenues imply different rates of labour supply with regard to tax rate increases.

Rogerson considered that differences in the composition of government spending can potentially account for the high rate of labour supply in Sweden and elsewhere in Scandinavia. Specifically, examining the conditions on which how tax revenue is returned to Swedes as income transfers or other conditional payments is central to understanding the labour supply effects of taxes:

  • If higher taxes fund disability payments which may only be received when not in work, the effect on hours worked is greater relative to a lump-sum transfer with no conditions; and
  • If higher taxes subsidise day care for individuals who work, then the effect on hours of work will be less than under the lump-sum transfer with no conditions.

A much higher rate of government employment and greater expenditures on child and elderly care explain the high rates of Swedish labour supply.

Swedes are taxed heavily, but key parts of this tax revenue are then given back to them conditionally if they keep working. Policies that significantly cut the total wealth available for redistribution by Swedish governments were avoided relative to the germane counter-factual, which are other even costlier modes of income redistribution.

Why do recessions cheer the Left up?

Why is it that the further to the Left that people go, the more cheerful they seem to be in recessions and economic crises? They are miserable when times are good.

The Left supported the discretionary fiscal, monetary and regulatory policies that caused the recession and then supported crisis management policies that deepen the recession. The Left always wants to tax and regulate their way out of every recession.

Most crisis management policies distort the incentives to hire and invest and reduce competition and efficiency. While different sorts of shocks lead to ordinary downturns, it is overreactions by governments to stem the crisis that prolong and deepen economic downturns, turning them into depressions.

One in three EU unemployed are Spanish because of employment protection laws. Cahuc et al. 2012 estimated that Spanish unemployment would be 45% lower if Spain adopted the less strict French laws! Differences in their employment protection laws accounted for nearly half of the dramatic rise in Spanish unemployment since 2007. Who is for and against these terrible laws?

Lee Ohanian: Hoover, Roosevelt and the Great Depression

Individual tradable birth licences – ecological economics’ finest hour?

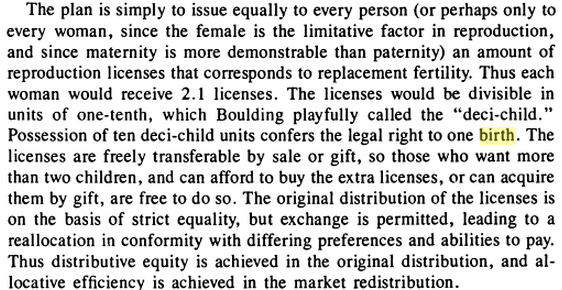
A mate suggested that I look into ecological economics. The self-appointed visionaries of ecological economics were so concerned about the population bomb that they proposed a “choice-based, marketable, birth license plan” or “birth credits” for population control. The Earth’s carrying capacity is a central issue in ecological economics.

Birth credits were promoted by urban designer and environmental activist Michael E. Arth since the 1990s and earlier by economist Kenneth Boulding (1964) and ecological economist Herman Daly (1991). I am not making this up.

Birth credits would allow any woman to have as many children as she wants, as long as she buys a license for any children beyond an average allotment that would result in zero population growth (ZPG). Birth credits are similar to individual tradable quotas for fishing.

  • If the allotment was determined to be 1.1 children, then the first child would be free, and the market would determine the cost of the license or birth credit for each additional child.
  • The units could be sold in units of 1/10th of a credit with each of us getting 1.1 credits each for free, under some proposals.

Being nice members of the middle class, the penalty proposed for an illegal baby would be community service for the parents. I am sure most parents would welcome the time out of the house and the free child care. Obviously, these nice family unfriendly educated middle class ZPG types do not seem to appreciate the seas and oceans that some with cross to have a child.

daly birth licences

Arth, Dally and his fellow prophets were smug enough to think they could see the future and a looming population bomb and food riots, but plainly they got the sign of the demographic crisis wrong.

Sub-replacement fertility is now the demographic crisis. Over half of the world’s population lives in countries with fertility rates at or below replacement level, and nearly all countries will reach low fertility levels in the next decade or two.

A larger population can, as Gary Becker has pointed out, increase the rate of technological progress by increasing the number of creative people working away at inventing new products and ideas. More people means more markets that will reach a critical mass for which people can then profitably invent new products, which further increase innovation and economic growth.

The price of these birth credits would be now lower than an EU carbon credit. You could not give them away.

HT: Steady-State Economics: Second Edition With New Essays – Herman E. Daly – Google Books.

Lee Ohanian: The Economic Crisis: A Comparison Across Time and Countries


“The Recession of 2007–?” by Robert E. Lucas

Robert Lucas in this speech noted that the implicit assumption is that the US economy will get back to old trend growth rate and the only question is how long it will take

Lucas asked whether this is really the case? He noted that:

  • We know that European economies have larger government role and 20-30% lower income level than the US; and
  • Is it possible that by imitating European policies on labor markets, welfare, and taxes U.S. has chosen a new, lower GDP trend?

If so, Lucas said that it may be that the weak recovery the USA has had so far is all the recovery it will get.

Ed Prescott also considers that tax rates are being increased in the USA. These increases lower amount of capital a firm chooses to have. The reason for low investment is not problem of getting loans – it is expected future high tax rates in the USA.

Ed Prescott also considers that investment suddenly became depressed beginning early in 2008 – because of a policy regime change. Business owners feared higher tax rates with the regime change and rationally cut investment, rationally cut employment ad rationally took more cash out of business.

Previous Older Entries Next Newer Entries

The War on Prices

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

The Bleeding Heart Libertarian

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

More Stories from the Stories I Publish!

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

In My Tribe

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Coordination Problem

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Libertarian Land

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Arin’s Substack

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

David Andolfatto

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Monetary Non-Neutrality

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Reason Magazine

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Coyote Blog

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Thoughts from the North

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Fardels Bear

A History of the Alt-Right

Vincent Geloso

Econ Prof at George Mason University, Economic Historian, Québécois

Bassett, Brash & Hide

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Truth on the Market

Scholarly commentary on law, economics, and more

The Undercover Historian

Beatrice Cherrier's blog

Matua Kahurangi

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Temple of Sociology

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Velvet Glove, Iron Fist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Why Evolution Is True

Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.

NoTricksZone

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Homepaddock

A rural perspective with a blue tint by Ele Ludemann

Kiwiblog

DPF's Kiwiblog - Fomenting Happy Mischief since 2003

The Dangerous Economist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Watts Up With That?

The world's most viewed site on global warming and climate change

The Logical Place

Tim Harding's writings on rationality, informal logic and skepticism

Doc's Books

A window into Doc Freiberger's library

The Risk-Monger

Let's examine hard decisions!

Uneasy Money

Commentary on monetary policy in the spirit of R. G. Hawtrey

Barrie Saunders

Thoughts on public policy and the media

Liberty Scott

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Point of Order

Politics and the economy

James Bowden's Blog

A blog (primarily) on Canadian and Commonwealth political history and institutions

Science Matters

Reading between the lines, and underneath the hype.

Peter Winsley

Economics, and such stuff as dreams are made on

A Venerable Puzzle

"The British constitution has always been puzzling, and always will be." --Queen Elizabeth II

The Antiplanner

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Bet On It

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

History of Sorts

WORLD WAR II, MUSIC, HISTORY, HOLOCAUST

Roger Pielke Jr.

Undisciplined scholar, recovering academic

Offsetting Behaviour

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

JONATHAN TURLEY

Res ipsa loquitur - The thing itself speaks

Conversable Economist

In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”

The Victorian Commons

Researching the House of Commons, 1832-1868

Books & Boots

Reflections on books and art