Can New Zealand blame distance for its economic woes?

Distance is common in many discussions of the relative growth performance of New Zealand. New Zealand is said to be small and remote and poorer for it. The figure below from a Productivity Commission report is an example.
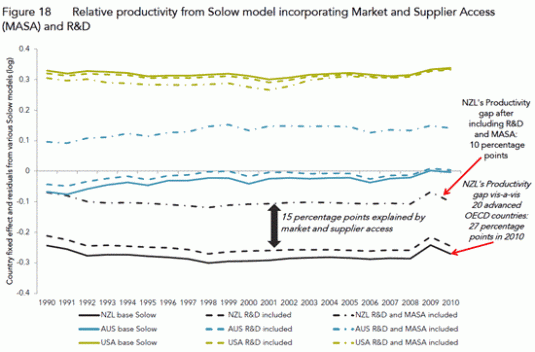
The Productivity Commission put it this way:

New Zealand firms face reduced access to large markets and limited participation in global value chains, where the transfer of advanced technologies now often occurs.

Indeed, global value chains – which can require intensive interaction and just-in-time delivery across borders – may have worsened the impact of New Zealand’s geographic isolation on trade in goods.

The Commission continues on to say that:

These limits on trade and the diffusion of new ideas into New Zealand may explain as much as 15 percentage points of the 27% productivity gap between New Zealand and the average of 20 OECD countries.

This 15 per cent claim is a daring claim. Physical location does not change over time.

New Zealand, Australia and the other European offshoots such as Canada and the USA all prospered for most to all their histories despite their distances from their mother country. Canada cannot blame distance for its weak productivity performance because it is next door to the USA.

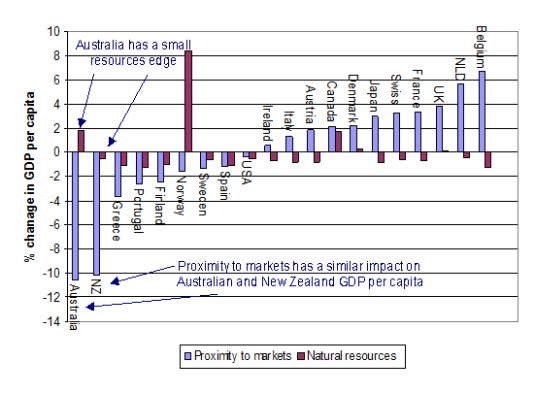
Figure 1 below using OECD data suggests that New Zealand and Australian real GDP per capita are both about 10 percentage points lower than they otherwise would be because of distance. A bounty of natural resources gives a less than a two per cent boost to Australia’s real GDP per capita, see Figure 1.

Figure 1: Estimated impact of proximity to markets and natural resources on real GDP per capita, OECD members, average for 2000-2004
Source: OECD.

The burden of geography is about distance from large agglomerations of production, consumption and supply. There is from the extra cost of exporting to distant markets and the cost penalty from ordering from major suppliers who are far way. Geography can also affect the international flow of ideas and the diffusion of new technologies.

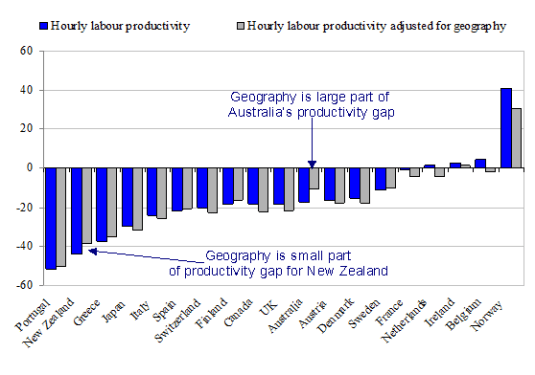
Figure 2 shows that most of the labour productivity gap of New Zealand and many others with the USA is not explained by geography – by access to major markets and any natural resource bounty.

Figure 2: Apparent and geography adjusted hourly labour productivity relative to the USA, 2006

Source: OECD (2008).

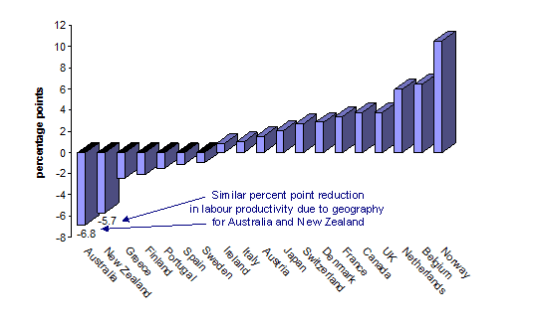
New Zealand’s apparent and geography adjusted productivity gaps with the USA are not far apart. In contrast, the OECD (2009c), geography cuts in half the gap in hourly labour productivity between the USA and Australia – see Figure 3.

Figure 3: Percentage point change in hourly labour productivity relative to the USA due to geography, 2006
Source: OECD.

The labour productivity gap of New Zealand with the USA is over four times larger than what could be reasonably attributed to geographic burdens. Other factors must account for the bulk of New Zealand’s productivity gap.

More to the point, distance and remoteness explain none of the productivity and income gaps across the Tasman and why this gap suddenly appeared in the 1970s and 1980s to NZ’s disadvantage.

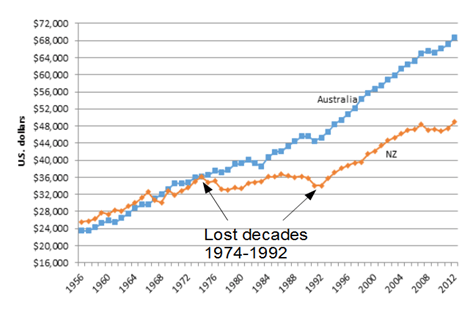
New Zealand lost almost two decades of growth between 1974 and 1992 as shown in Figure 4.

Figure 4: Real GDP per New Zealander and Australian aged 15-64, converted to 2013 price levels with updated 2005 EKS purchasing power parities, 1956-2012
Source: Computed from OECD StatExtract and The Conference Board, Total Database, January 2014.

The Trans-Tasman gap is the income and productivity gap that concerns Kiwis and is the relevant policy yardstick everyone uses or should use.

The emergence of the Trans-Tasman income gap from initial income parity in 1974 – see Figure 4 – cannot be because of distance because both NZ and Australia suffer equally from a 10% productivity burden because of distance.

This common 10% productivity burden due to distance does not explain real GDP per working age person in Australia and NZ dropping from parity in 1974 to a 35% gap inside 20 years and then suddenly stabilising.

Figure 4 showed that NZ started growing again in 1992 after the Ruth Richardson horror budget stabilised economic policy sentiments. There was to be no going back on the economic reforms.

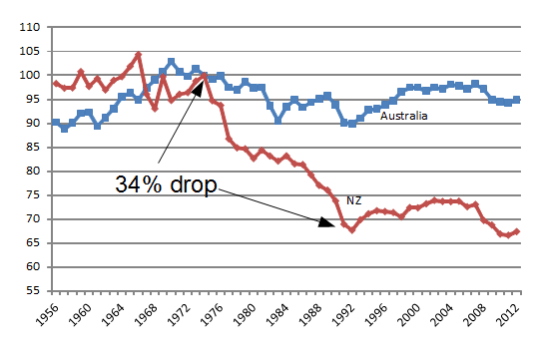
Figure 5 below shows that NZ’s labour productivity growth dropped like a stone between 1974 and 1992 then stabilised at 1.85% growth per year from 1992 to 2005. GDP per working age person in Figure 5 is based to 100 in 1974 and then detrended by 1.85% per year – the trend growth rate of the USA in the 20th century. A flat line in Figure 5 is annual growth in real GDP per working age person of 1.85%. Australia’s growth rate is pretty flat since 1970 bar the odd recession and recovery from the same.

Figure 5: Real GDP per New Zealander and Australian aged 15-64, converted to 2013 price levels with updated 2005 EKS purchasing power parities, base 100 in 1974, 1.85 per cent detrending, 1956-2012
Source: Computed from OECD StatExtract and The Conference Board, Total Database, January 2014.

This 34% productivity drop in NZ from 1974 to the mid-1980s was too rapid to be explained by distance and global value chains suddenly becoming more important than was the case for most of NZ’s history. Australian GDP growth rates was not affected in the slightest by these trends in the geography of trade and input markets.

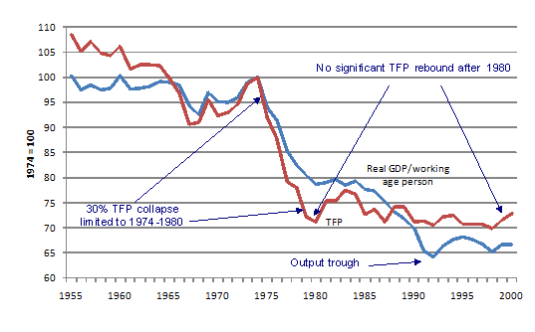
The Productivity Commission looked at the wrong data to ask the wrong questions. The data analysis undertaken on behalf of the Productivity Commission started in 1980. Figure 6 below shows at all the action and excitement regarding total factor productivity in New Zealand occurred before 1980.

Figure 6: New Zealand total factor productivity and real GDP per New Zealander aged 15-64, 2 per cent detrended, 1955-2000
Source: Kehoe and Ruhl (2003).

Kehoe and Ruhl (2003) attributed the decline in the growth of GDP per working age New Zealander after 1974 to 1992 to a sharp decline in total factor productivity from 1974 to 1980.

Figure 6 plots detrended data constructed by Kehoe and Ruhl (2003) to show that total factor productivity fell rapidly in New Zealand between 1974 and 1980, by 30 per cent in all, and then levelled out to grow again at the trend rate of two per cent.

There was no subsequent total factor productivity recovery to make up the lost ground. If this were so, Figure 4 would have had to include a strongly rising line for total factor productivity over many years after 1980 to recover the 30 per cent fall in the level of total factor productivity between 1974 and 1980.

Kehoe and Ruhl (2003) suggested that the identification of the factors that permanently reduced total factor productivity levels in New Zealand between 1974 and 1980 may have great contemporary policy relevance.

The total factor productivity drop identified by Kehoe and Ruhl (2003) occurred before the 1978 start of the Statistics New Zealand productivity data series.

The great value of the Kehoe and Ruhl (2003) data is the drawing out of the major decline in total factor productivity on the eve of the Statistics New Zealand data series.

Kehoe and Ruhl (2003) attributed the 1970s total factor productivity collapse to a massive change in trade patterns after the entry of the UK into the then European Economic Community in 1973.

All discussions of income gaps should be against Australia and any additional burden of distance that New Zealand faces in addition to Australia since 1974 when the Trans-Tasman income gap emerged.

When New Zealand catches-up with Australia in labour productivity that will be the time to start worrying about the burden of geography – a burden that holds back relative productivity equally in both countries. You cannot explain the difference between Australia’s and NZ’s relative productivity by geographic factors they have in common.

Everything’s Amazing and Nobody’s Happy | Bryan Caplan

Margaret Thatcher, Hayek & Friedman | Margaret Thatcher Foundation

Thatcher read Hayek’s Road to Serfdom as an undergraduate at Oxford. She took away two key lessons for her life: you cannot compromise with socialism, even the mild social democratic forms; and she saw her own party was doing just that, which put her deeply at odds with its leadership.

After she became Leader of the Opposition, Thatcher cut short a leftish member of her own  Conservative Party Research Department by showing him a copy of The Constitution of Liberty, slamming it down on the table declaring “this is what I believe”.

Thatcher’s relationship with Milton Friedman was different to that of Hayek and not as long standing. Friedman met Thatcher for the first time at a dinner in 1978.

After Thatcher came to office in 1979, Friedman was a critic of the monetary regime of the Thatcher government, questioning her monetary policy targets,  questioning the raising of the value added tax to finance income tax cuts,  and urging deeper spending cuts in the 1979 budget. Friedman was also a strong critic of the monetary policies of the Fed at that time as well, arguing that they lacked credibility, transparency and were very erratic.

In a letter to the Times on 3 March 1980 Friedman stated that he opposed “fine-tuning” and strongly preferred:

a steady monetary and fiscal policy announced long in advance and strictly adhered to

Hayek disagreed with Friedman about the role of gradualism in a letter to the Times on 26 March 1980:

The chief practical issue today is how fast inflation can be and ought to be stopped.

On this, I am afraid, my difference from Friedman makes me take an even more radical position.

The reason is that I believe that the artificial stimulus which inflation gives to business and employment lasts only so long as inflation accelerates, that is, so long as prices turn out to be higher than expected.

Inflation clearly cannot accelerate indefinitely, but as soon as it ceases to accelerate, all the windfalls due to prices turning out higher than expected, which kept unprofitable businesses and employment going, disappear.

Every slowing down of inflation must therefore produce temporary conditions of extensive failures and unemployment.

No inflation has yet been terminated without a “stabilization crisis”.

To advocate that inflation should be slowed down gradually over a period of years is to advocate a long period of protracted misery. No government could stand such a course.

Milton Friedman’s general views on Britain when Thatcher first came to office were clear-cut and were also stated in his letter to the Times on 3 March 1980:

…while monetary restraint is a sufficient condition for controlling inflation, it is a necessary but not sufficient condition for improving Britain’s productivity – the fundamental requirement for restoring Britain to full economic health.

That requires measures on a broader front to restore and improve incentives, promote productive investment, and give a greater scope for private enterprise and initiative.

Both Hayek and Friedman wrote privately about the Thatcher policies of the early 1980s, decrying them as gradualism. So much for the retired professors as the ring masters of neo-liberalism and Thatcher as their pawn.

Friedman and Hayek disagreed with each other, in important respects, about both gradualism in monetary policy and  macroeconomics in general.

Thatcher did not follow their conflicting policy advice to her. At best, Thatcher was a wayward disciple of squabbling prophets.

Friedman was a strong critic of Austrian macroeconomics and its supposed role in the 1930s policy response or lack of a response to the Great Depression:

I think the Austrian business-cycle theory has done the world a great deal of harm.

If you go back to the 1930s, which is a key point, here you had the Austrians sitting in London, Hayek and Lionel Robbins, and saying you just have to let the bottom drop out of the world.

You’ve just got to let it cure itself. You can’t do anything about it. You will only make it worse. You have Rothbard saying it was a great mistake not to let the whole banking system collapse.

I think by encouraging that kind of do-nothing policy both in Britain and in the United States, they did harm.

Hayek was equally critical of the macroeconomics of Milton Friedman and his methodology in general:

I do indeed regard the abandonment of the whole macroeconomics nonsense as very important, but it is for me a very delicate matter and I have for some time avoided stating my views too bluntly and would not have time to state them adequately.

The source of the difficulty is the constant danger that the Mont Pelerin society might split into a Friedmanite and a Hayekian wing.

 I have long regretted my failure to take time to criticise Friedman’s Positive Economics almost as much as my failure to return to the critique of Keynes General Theory after I had dealt with his Treatiese.

It still seems to me paradoxical that Keynes, who was rather contemptuous of econometrics, should have become the main source of the revival of macroeconomics – which incidentally was also the reason why Milton was for a time a Keynesian.

I believe a good and detailed critical analysis of macroeconomics would be very desirable.

Brad Delong pointed out in 2000 that the New Keynesian macroeconomic research program was developed in the 20th century monetarist tradition mostly in the work of Milton Friedman.

Tom Sargent argued in 1981 that Thatcher’s medium term economic strategy was gradualism, and the sustained budget deficits would result in unpleasant monetarist arithmetic:

…In order that the current British plan be viewed as credible it is necessary that the large prospective government deficits over the next several years be counterbalanced by prospective surpluses further down the line.

It is difficult to point to much either in current legislation,  or equally importantly, in the general British political climate that could objectively support such an outlook.

…Gradualism invites speculation about future reversals with U-turns in policy.

Large contemporary government deficits unaccompanied by concrete prospects for future government surpluses promote realistic doubts about whether monetary restraint must be abandoned sooner or later to help finance the deficits.

Such doubts not only call into question the likelihood that the plan can successfully permanently reduce inflation, but also can  induce high real cost in terms of depressed industry and lengthened unemployment in response to what may be viewed as only temporary downward movements in nominal aggregate demand that the monetary restraint induces.

What did Thatcher actually do?

by discrediting socialism so thoroughly, she prompted in due course the adoption by the Labour Party of free market economics, and so, as she wryly confessed in later years, “helped to make it electable”.

The archives of the Margaret Thatcher foundation has released extensive correspondence and other documents about Thatcher, Hayek and Friedman.

via MT, Hayek & Friedman | Margaret Thatcher Foundation.

Marginal tax rates and labour supply

Americans now work 50 per cent more than do the Germans, French, and Italians. This was not the case in the early 1970s, when the Western Europeans worked more than Americans.

Edward Prescott found that taxes accounted for these differences in labour supply across time and across countries; in particular, the effective marginal tax rate on labour income. The population of countries considered is the G-7 countries, which are major advanced industrial countries. Prescott concluded that

virtually all of the large differences between U.S. labour supply and those of Germany and France are due to differences in tax systems.

Prescott and many that followed him were truly puzzled by the lack of a role for employment mandates, employment protections and product market regulation in Europe’s poor economic performance

Richard Rogerson is a very sharp fellow who built on Prescott’s work. Most anything Rogerson writes is worth a look.

A non-technical note by Rogerson made these key points:

  1. Europe’s taxes punish working outside the home, so Europeans don’t work as much as they would otherwise;

  2. Dramatic differences in the overall change in hours worked per person aged 16 to 64 across countries between 1960 and 2000;

  3. at one extreme the U.S., with an increase of 10 per cent between these two dates;

  4. At the other extreme are Germany and France, with declines of more than 30 per cent;

  5. For the U.S. and France, the difference is staggering—more than 45 per cent;

  6. Richard Freeman and Ronald Schettkat (2001) studied time allocation by married couples in Germany and the United States.

  7. Their striking finding is about total time devoted to work (i.e., market work plus home production) turns out in the two countries is virtually the same.

In The Impact of Labor Taxes on Labor Supply: An International Perspective (AEI Press, 2010) Rogerson finds that:

• a 10 percentage point increase in the tax rate on labour leads to a 10 to 15 per cent decrease in hours of work.

• Even a 5 per cent decrease in hours worked would mean a decline in labour output equating to a serious recession.

• While recessions are temporary, permanent changes in government spending patterns have long-lasting repercussions.

• Although government spending provides citizens with important benefits, such benefits must be weighed against the disincentive effects of increased labour taxes.

• Policymakers who fail to account for the decrease in labour output risk expanding government programs beyond their optimal scale.

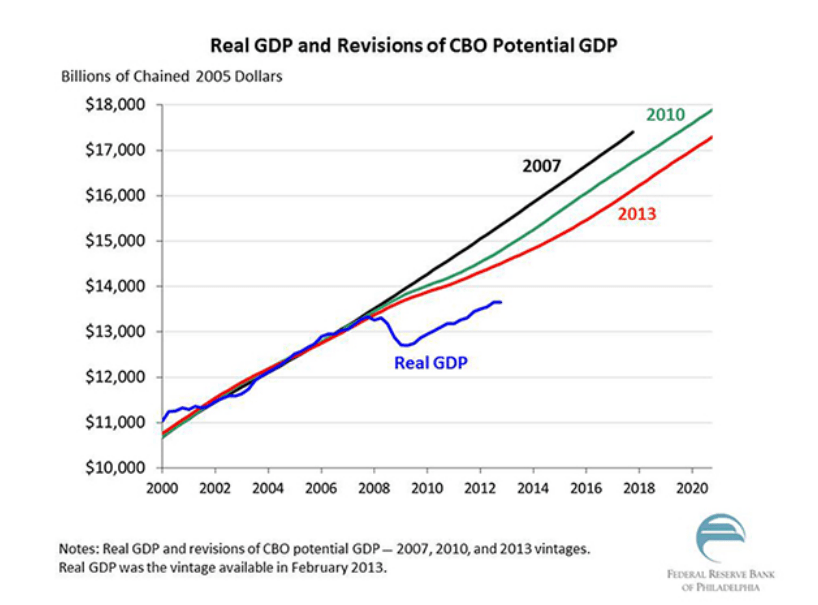
A Great Recession or a permanent move to a lower U.S. growth path?

Philadelphia Fed President Charles Plosser made this nice graph on official views of potential GDP and trends in actual GDP.

via The Grumpy Economist: Declining expectations.

Supply-Side Economics in Iceland

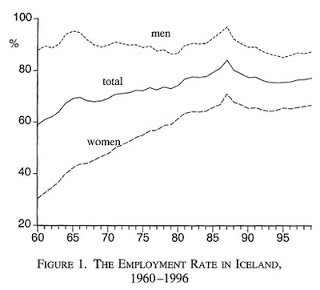
The move to a pay-as-you-earn income tax system in Iceland in 1988 made income earned in 1987 tax-free.
  • Icelandic GDP increased by 4.16% in 1987.
  • Total labour supply rose by 6.7% in 1987 over the average of 1986 and 1988.
  • This included an 8.6% increase in weeks of work supplied by those already in the labour market in 1986.
Notice in the graph the big kink in employment in 1987. A spike just for the year of no taxes. Labour supply then fell away.
Iceland in 1987 was a unique opportunity to study the labour supply response of individuals who were temporarily faced with a zero marginal-and average-income tax rate.

via Corrections: Page One: Supply-Side Economics.

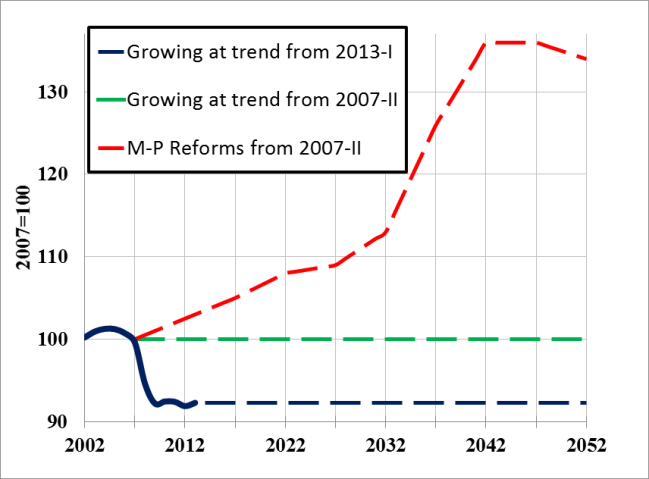
The path to higher U.S. prosperity

Suppose the USA:

  1. Had mandatory savings for retirement
  2. Eliminated capital income taxes
  3. Broadened tax base and lowered the marginal tax rate
  4. Phased in reforms so all birth-year cohorts are made better off
  5. Left welfare programs and local public good shares the same
  6. Savings not part of taxable income, saving withdrawals part of taxable income – with these changes U.S. income tax would be a consumption tax

US Detrended GDP per Capita

Source: Edward Prescott and Ellen McGrattan 2013.

The Rawlsian social justice case for super-entrepreneurs and many more billionaires

The report SuperEntrepreneurs shows that:

  • SuperEntrepreneurs founded half the largest new firms created since the end of the Second World War
  • There is a strong correlation between high rates of SuperEntrepreneurship in a country and low tax rates
  • a low regulatory burden and high rates of philanthropy both correlate strongly with high rates of SuperEntrepreneurship
  • Active government and supranational programmes to encourage entrepreneurship – such as the EU’s Lisbon Strategy – have largely failed.
  • Yet governments can encourage entrepreneurialism by lowering taxes (particularly capital gains taxes which have a particularly high impact on entrepreneurialism while raising relatively insignificant revenues); by reducing regulations; and by vigorously enforcing property rights.
  • High rates of self-employment and innovative entrepreneurship are both important for the economy.
  • Yet policy makers should recognise that they are not synonymous and should not assume policies which encourage self-employment necessarily promote entrepreneurship.
  • Policy makers should use a definition of entrepreneurship which is based on innovation.

SuperEntrepreneurs examined about 1,000 self-made men and women who have earned at least $1 billion dollars and who appeared in Forbes magazine list of the world’s richest people between 1996 and 2010.

Hong Kong has the most, with around three SuperEntrepreneurs per million inhabitants, followed by Israel, the US, Switzerland and Singapore.

The US is roughly four times more super-entrepreneurial than Western Europe and three times more super-entrepreneurial than Japan.

Super-entrepreneurs tend to be well-educated – 84% have a university degree.

Many started their own company but there is no clear relationship between self-employment and successful entrepreneurship

Steven Kaplan and Joshua Rauh’s “It’s the Market: The Broad-Based Rise in the Return to Top Talent” Journal of Economic Perspectives 2013 found that those in the Forbes 400 richest are less likely to have inherited their wealth or grown-up wealthy.

Today’s super-rich are self-made rich because they produce new and better products and services that people wanted and are willing to pay for.

John Rawls was alive to the importance of incentives in a just and prosperous society.

With his emphasis on fair distributions of income, Rawls’ initial appeal was to the Left. Left-wing thinkers then started to dislike his acceptance of capitalism and his tolerance of large discrepancies in income and wealth.

Rawls excluded envy when we are behind his veil of ignorance designed the social contract about how the society will be organised. He believed that principles of justice should not be affected by individual inclinations, which are mere accidents.

Rawls also argued that the liberties and political status of equal citizens encourage self-respect even when one is less well off than others; and background institutions (including a competitive economy) make it likely that excessive inequalities will not be the rule. He supposes that

the main psychological root of our liability to envy is a lack of self-confidence in our own worth combined with a sense of impotence

Then there is the old Russian joke that tells the story of a peasant with one cow who hates his neighbour because he has two. A sorcerer offers to grant the envious farmer a single wish any thing he wants: “Shoot my neighbour’s cow!” he demands.

via http://www.kiwiblog.co.nz/2014/04/entrepreneurship.html

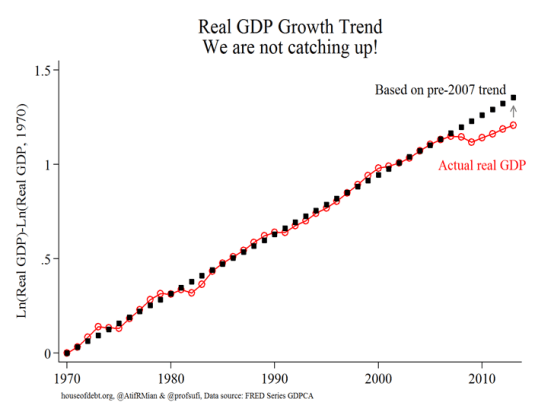
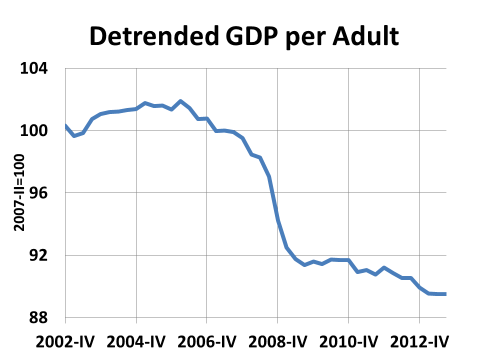
A Great Recession or dropping to a lower long-term growth path

Ed Prescott and Robert Lucas are several of many who use variations of the chart below to show that the USA has moved to a lower long-term growth path.

Source: House of Debt

The chart below for output per working age American (ages 15 to 64) is just as depressing.

Source: Edward Prescott

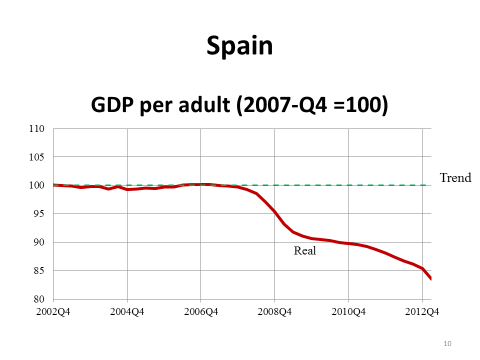
At least Spain with its 25% unemployment rate is doing a little worse.

Source: Edward Prescott

Many people are far too smart to save for their retirements

Which is better? Save for your retirement through the share market or save to own your own home and then present yourself at the local social security office to collect your taxpayer funded old-age pension?

Under this fine game of bluff, you bleed the taxpayer in your old age and pass on your debt-free home to your children.

This strategy is rational for the less well-paid. The family home is exempt from Income and asset testing for social security. If you lose you bet, sell your house and live off the capital.

For ordinary workers, this is a good bet. The middle class might prefer to live in a more luxurious retirement.

For ordinary workers, whose wages are not a lot more than their old age pension from the government, a government funded pension is a good political gamble. The old-age pension for a couple in New Zealand is set at no less that 60% of average earnings.

Compulsory savings for retirement requires the middle class to do what they can afford to do and would have done anyway.

Compulsory savings for retirement requires the working class to do what they can less afford to do.

Instead compulsory retirement savings deprives them of an old-age pension paid for by the taxes of the middle class.

In Australia, ordinary workers are required by law to save 9% of their wages for their retirements at 65 before they have had a chance to save for a car or a house or the rest of the condiments of life the middle class take for granted.

Edward Prescott argues for compulsory retirement savings account albeit with important twists because it is otherwise irrational for many to save for their retirement:

The reason we need to have mandatory retirement accounts is not because people are irrational, but precisely because they are perfectly rational — they know exactly what they are doing.

If, for example, somebody knows that they will be cared for in old age — even if they don’t save a nickel — then what is their incentive to save that nickel? Wouldn’t it be rational to spend that nickel instead?

…Without mandatory savings accounts we will not solve the time-inconsistency problem of people under-saving and becoming a welfare burden on their families and on the taxpayers. That’s exactly where we are now.

Prescott’s proposals are age specific. Those younger than 25 are not required to save anything because they are more pressing priorities such as buying cars and other consumer durables:

  • Before age 25, workers would have no mandatory government retirement savings.
  • Beginning at age 25, workers would contribute 3% vis-à-vis the current 10.6%.
  • At age 30, that rate would increase to 5.3 percent.
  • At 35, the rate would equal the full 10.6 percent.
  • Upon retirement, there would be an annuity over the remaining lives of the individual and spouse

clip_image001

Most of all, the retirement savings must go into private savings accounts. These savings remain assets of the individual and therefore the compulsory savings requirements is not a tax and does not discourage labour supply, as Prescott explains:

Any system that taxes people when they are young and gives it back when they are old will have a negative impact on labour supply. People will simply work less.

Put another way: If people are in control of their own savings, and if their retirement is funded by savings rather than transfers, they will work more.

Prescott’s Nobel Prize jointly with Finn Kydland was for showing that policies are often plagued by problems of time inconsistency. They demonstrated that society could gain from prior commitment to economic policies.

Of course, as Tyler Cowen observed, forced savings schemes are easily offset by people rearranging their affairs, and they have their entire adult life to do so:

How much can our government force people to save in the first place?

You can make them lock up funds in an account, but they can respond by borrowing more on their credit cards, taking out a bigger mortgage, and in general investing less in their future.

People do not save for their retirements not because they are short-sighted, but because they are far-sighted. They know that governments will not carry out their threats and other big talk about not providing an adequate old-age pension.

The only way that governments can commit to not bailing people out who retire with no savings is to make them save for their own retirements over their working lives.

Some will be against this compulsion. Their opposition to compulsion cannot be based on opposition to the nanny state because that is faulty reasoning.

These opponents of compulsion and everyone else in the retirement income policy debate are playing in a far more complicated, decades long dynamic political game where ordinary people time and again out-smart conceited governments who pretend they know better:

The government has strategies.

The people have counter-strategies.

Ancient Chinese proverb

Why I am not reviewing Thomas Piketty’s Capital in the Twenty-First Century – updated again

It’s 700 pages long and goes on about Marx. Some people were watching the other channel when the Berlin Wall fell.

thomas-piketty-economist-will-hutton

My 1 o’clock lecture at ANU in 1990 was next to a room rented out ironically from 12 to 1 to the Campus Trots and then to the Campus Christians for an hour of prayer to another saviour.

The Twitter summary of Piketty is this:

Karl Marx wasn’t wrong, just early. Pretty much. Sorry, capitalism. #inequalityforevah

The only Marxist I bother with is Jon Elster. He is a leading proponent of Analytical Marxism and one of the last polymaths. Brian Barry once wrote that to review one of Elster’s books one:

would either have to have taken off several years to master the many fields which fall within Elster’s purview or would be a consortium of at least twenty carefully-chosen experts.

All of Elster’s books and writings are worth reading, including

  • Ulysses and the Sirens (1979);
  • Sour Grapes: Studies in the Subversion of Rationality (1983);
  • Making Sense of Marx (1985); and
  • An Introduction to Karl Marx (1986).

As Jon Elster noted:

Marxian economics is, with a few exceptions, intellectually dead

and Marx’s labour theory of value is:

useless at best, harmful and misleading at its not infrequent worst.

To go on with my non-review, I will quote Tyler Cowen:

The crude seven-word version of Piketty’s argument is “rates of return on capital won’t diminish.”

Piketty’s reasons why rates of return on capital won’t diminish are fairly specific and restricted to only a small share of capital.

.. In any case this is pure speculation and Piketty’s entire argument depends upon it.

… Piketty converts the entrepreneur into the rentier.

To the extent capital reaps high returns, it is by assuming risk…

Yet the concept of risk hardly plays a role in the major arguments of this book.

Once you introduce risk, the long-run fate of capital returns again becomes far from certain.

In fact the entire book ought to be about risk but instead we get the rentier…

Overall, the main argument is based on two (false) claims.

First, that capital returns will be high and non-diminishing, relative to other factors.

Second, that this can happen without significant increases in real wages.

Piketty’s advocacy of a top marginal income tax rate of 80% and a an international treaty for a wealth tax are wildly impractical and destructive of economic growth and entrepreneurship. His advocacy of 60% marginal tax rates on incomes above $200,000 strike at the heart of the professional and managerial occupations that are the backbone of day-to-day capitalism. Piketty’s wealth tax would tax the homes and the retirement savings of the ordinary middle class:

  • wealth below 200,000 euros be taxed at a rate of 0.1 percent,
  • wealth between 200,000 and one million euros at 0.5 percent,
  • wealth between one million and five million euros at 1.0 percent, and
  • wealth above five million euros at 2.0 percent.

Piketty’s reason for these high top tax rates is not to bring in more revenue or to redistribute wealth to poor and the downtrodden but simply “to put an end to such incomes.” Harsanyi argues that:

Like many progressives, Piketty doesn’t really believe that most people deserve their wealth anyway, so confiscating it presents no real moral dilemma.

He also argues that we can measure a person’s productivity and the value of a worker (namely, low-skilled labourers) while arguing that other groups of workers (namely, the kind of people he doesn’t admire) are bequeathed undeserved, “arbitrary” salaries. What tangible benefit does a stockbroker or a kulak or an explanatory journalist offer society, after all?

This takes me back to Jon Elster who had this to say on socialism:

Optimism and wishful thinking have been features of socialist thought from its inception.

In Marx, for instance, two main premises appear to be that whatever is desirable is possible, and that whatever is desirable and possible is inevitable.

…It has become clear that classical socialism massively underestimated the importance of economic incentives.

Greg Mankiw is less harsh, but still to the point:

Like President Obama and others on the left, Piketty wants to spread the wealth around.

Another philosophical viewpoint is that it is the government’s job to enforce rules such as contracts and property rights and promote opportunity rather than to achieve a particular distribution of economic outcomes.

No amount of economic history will tell you that John Rawls (and Thomas Piketty) offers a better political philosophy than Robert Nozick (and Milton Friedman).

John Rawls was actually very much alive to the importance of incentives in a just and prosperous society.

Unequal incomes might turn out to be to the advantage of everyone. Work effort and entrepreneurial alertness respond to incentives; incentives channel people into the occupations and jobs where they produce more.

Rawls lent qualified support to the idea of a flat-rate consumption tax because these taxes:

impose a levy according to how much a person takes out of the common store of goods and not according to how much he contributes.

A simple way to have a progressive consumption tax is to exempt all savings from taxation.

With his emphasis on fair distributions of income, Rawls’ initial appeal was to the Left. Left-wing thinkers then started to dislike his acceptance of capitalism and his tolerance of large discrepancies in income and wealth.

It’s impossible to make the workers better off by taxing capital. The optimal rate of tax on income from capital is zero. This is why the Mirrlees Review of the UK taxation system argued for zero taxation of the returns to capital.

Robert Lucas estimated in 1990 that eliminating all taxes on income from capital would increase the U.S. capital stock by about 35% and consumption by 7%.

Hans Fehr, Sabine Jokisch, Ashwin Kambhampati, and Laurence J. Kotlikoff (2014) found that eliminating the corporate income tax completely would raise the U.S. capital stock (machines and buildings) by 23%, output by 8% and the real wages of unskilled and skilled workers each by 12%.

Book reviews serve the same purpose as film reviews. They are filters for our time. Do you agree?

I made a time management decision to not read a long book plenty of others reviewed and some even understood.

As for the growing income inequality, there is a long literature dating back 25-years arguing that skill-biased technological change is increasing the returns to investing in education as Gary Becker blogged in 2011:

Earnings inequality in the United States and many other countries has increased greatly since the late 1970s, due in large measure to globalization and technological progress that raised the productivity of more educated and more skilled individuals.

While the average American college graduate earned about a 40% premium over the average high school graduate in 1980, this premium increased to over 70% in 2000.

The good side of this higher education-based earnings inequality is that it induced more young men, and especially more young women, to go to and finish college.

The bad side is that many sufficiently able children could not take advantage of the greater returns from a college education because their parents did not prepare them to perform well in school, or they went to bad schools, or they lacked the financing to attend college.

As a result, the incomes of high school dropouts and of many high school graduates stagnated while incomes boomed for many persons who graduated college, and even more so for those with post graduate education.

There is nothing new under the sun.

Inequality as a Barrier to Growth? Invented Out of Thin Air | e21

Error 1: Use of Pre-Tax, Pre-Transfer Income to Measure Inequality. Throughout the report, the IMF uses the concept of “market income” to measure inequality. Market income is defined as income before taxes are paid to the government, and before transfers from the government to low-income individuals…

Error 2: More Inequality Leads to Lower Mobility. … Data from University of Ottawa professor Miles Corak on the United States, Canada, and Sweden suggest that more inequality is associated with higher mobility, not less mobility. Winship’s findings echo those of Harvard University economist Raj Chetty, who found little association between the share of income of the top one percent and mobility, either in the United States or between different countries…

Error 3: Tax Increases Lead to Higher Economic Growth… If transfers of income from one group to another succeeded in creating economic growth, the fastest-growing countries would be those with the highest top tax rates. As Nobel Prize-winning economist Edward Prescott has shown, the reverse is true.

via Inequality as a Barrier to Growth? Invented Out of Thin Air | e21 – Economic Policies for the 21st Century.

Tom Sargent on the Fundamentals of Currency Union Crises

Tom Sargent at Hong Kong University in April 2013 in four parts


Paul Krugman, Tom Sargent and Me

Paul Krugman seems to be implying that I am the double-secret ring-leader of a vast right-wing conspiracy.

clip_image001

Today in his blog at the New York Times, Krugman said:

…why the sudden attention to Sargent’s 2007 speech?

I think it’s fairly obvious: it’s essentially stealth anti-Keynesian propaganda, cloaked in the form of a widely respected and liked economist uttering what sound like eternal truths.

But they aren’t, and the real goal here is to undermine the case for fighting unemployment in the here and now. There are virtues to that 2007 talk, but right now is no time for 2007 Sargent.

In my reply at his blog, I said that I originally posted the link to Sargent’s speech to make a point that most economic analysis is free of politics because the average economist is a moderate Democrat. Tom Sargent is a life-long Democrat.

To add to my reply at Krugman’s blog, Krugman said earlier in his blog that:

It’s not so much that what Sargent said is wrong, although some of his principles are by no means universally agreed upon, even in normal times.

What’s so striking about Sargent’s points is that it’s hard to think of a worse time to cite them.

And the people citing that old speech clearly have ulterior motives.

I live in New Zealand. Not everything is about U.S. domestic politics.

I rather prophetical said on Marginal Revolution on the 20th that “Too many on social media such as Reddit responded by smearing Sargent as a right-winger and neo-liberal. He is a life-long Democrat.”

My conspiratorial minions span the globe to include initially Newmark’s Door and then Marginal Revolution,  Stephen Williamson, Vox.com, the American Enterprise Institute, Catallaxyfiles and the Business Insider to name but a few. There are other unindicted co-conspirators.

Karl Popper argued that conspiracy theories overlook the pervasive unintended consequences of political and social action; conspiracy theorists assume that all consequences must have been intended by someone.

Krugman agrees that Sargent’s 12-points are not that controversial in themselves. Krugman then plays the man rather than the ball:

“How to discredit an unwelcome report:

… Stage Four: Discredit the person who produced the report. Explain (off the record) that
1. He is harbouring a grudge against the Department.
2. He is a publicity seeker.
3. He is trying to get a Knighthood/Chair/Vice Chancellorship.
4. He used to be a consultant to a multinational.
5. He wants to be a consultant to a multinational.

Sir Humphrey, The Greasy Pole

Previous Older Entries Next Newer Entries

The War on Prices

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

The Bleeding Heart Libertarian

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

More Stories from the Stories I Publish!

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

In My Tribe

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Coordination Problem

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Libertarian Land

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Arin’s Substack

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

David Andolfatto

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Monetary Non-Neutrality

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Reason Magazine

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Coyote Blog

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Thoughts from the North

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Fardels Bear

A History of the Alt-Right

Vincent Geloso

Econ Prof at George Mason University, Economic Historian, Québécois

Bassett, Brash & Hide

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Truth on the Market

Scholarly commentary on law, economics, and more

The Undercover Historian

Beatrice Cherrier's blog

Matua Kahurangi

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Temple of Sociology

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Velvet Glove, Iron Fist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Why Evolution Is True

Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.

NoTricksZone

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Homepaddock

A rural perspective with a blue tint by Ele Ludemann

Kiwiblog

DPF's Kiwiblog - Fomenting Happy Mischief since 2003

The Dangerous Economist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Watts Up With That?

The world's most viewed site on global warming and climate change

The Logical Place

Tim Harding's writings on rationality, informal logic and skepticism

Doc's Books

A window into Doc Freiberger's library

The Risk-Monger

Let's examine hard decisions!

Uneasy Money

Commentary on monetary policy in the spirit of R. G. Hawtrey

Barrie Saunders

Thoughts on public policy and the media

Liberty Scott

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Point of Order

Politics and the economy

James Bowden's Blog

A blog (primarily) on Canadian and Commonwealth political history and institutions

Science Matters

Reading between the lines, and underneath the hype.

Peter Winsley

Economics, and such stuff as dreams are made on

A Venerable Puzzle

"The British constitution has always been puzzling, and always will be." --Queen Elizabeth II

The Antiplanner

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Bet On It

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

History of Sorts

WORLD WAR II, MUSIC, HISTORY, HOLOCAUST

Roger Pielke Jr.

Undisciplined scholar, recovering academic

Offsetting Behaviour

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

JONATHAN TURLEY

Res ipsa loquitur - The thing itself speaks

Conversable Economist

In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”

The Victorian Commons

Researching the House of Commons, 1832-1868

Books & Boots

Reflections on books and art