Doing Business in France, Germany and the UK – World Bank rankings compared

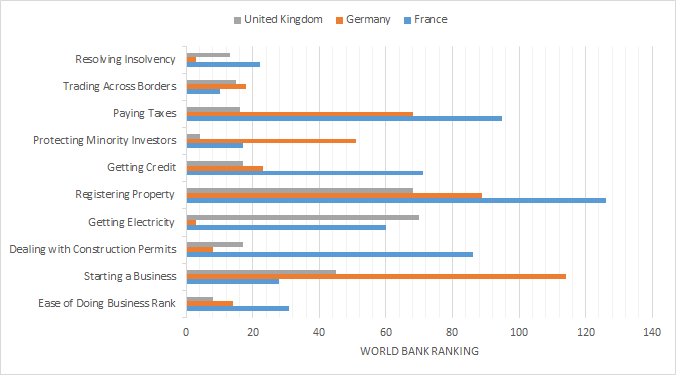
Figure 1: World Bank Doing Business rankings, France, Germany and the UK, 2014

image

Source: Doing Business – Measuring Business Regulations – World Bank Group.

Some things are decidedly harder to do in Germany and France than for businesses in the UK. On the other hand, it is surprisingly hard to register property in all three countries including the UK after 700 years of the blessings of the British common law.

Paying taxes in Germany and France are far harder than in the UK. Don’t  have anything to do with construction permits in France unless you must. It is surprisingly hard to get the electricity on in the UK and France.

The European Union must have some benefits when it comes to trading across the borders of all three countries. Only problem is in Germany where it is very difficult to start a business in the first place. Why is for a later posting.

Has NZ child poverty doubled as @MaxRashbrooke said?

Lindsay Mitchell put me onto a quote by veteran grumbler Max Rashbrooke that the child poverty rate doubled in New Zealand:

In a system where income goes disproportionately to the already well-off, ordinary workers are missing out on the rewards of their efforts, to the tune of billions of dollars a year. Welfare benefits, cut by a quarter in 1991 and increased just 8 per cent in the last budget, are far too low to meet people’s basic needs.

The result is a doubling of child poverty and the return of childhood diseases unknown in most developed countries – a national embarrassment, as one researcher described it.

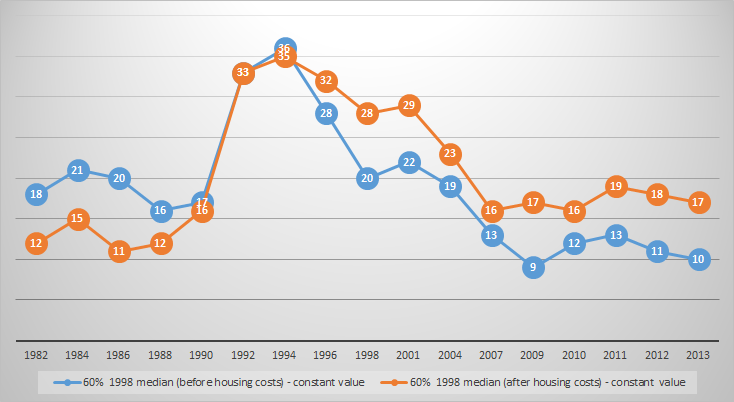
Poverty, income and inequality data is collected in loving detail by Brian Perry every year for the Ministry of Social Development.

Figure 1: % child poverty in New Zealand (before and after housing costs), 60% 1998 median constant value, 1982 – 2013

image

Source: Bryan Perry, Household incomes in New Zealand: Trends in indicators of inequality and hardship 1982 to 2013. Ministry of Social Development (July 2014), Tables F.6 and F.7.

The only thing noticeable in the downward trend in child poverty in New Zealand since its doubling with the sharp recession in 1990 with double-digit unemployment rates is child poverty stop falling shortly after in-work family tax credits were introduced in the form of Working for Families in 2005.

There was a break in trend in the long decline in child poverty as soon as in-work family tax credits were introduced in New Zealand. I’m sure this is a coincidence because, as Brian Perry said when discussing the introduction of Working for Families in 2005:

The 2004 to 2007 period was the only one in the 25 years to 2007 in which the incomes of low- to middle-income households grew more quickly than those of households above the median.

The real killer in New Zealand in terms of poverty and inequality are housing costs. Housing costs are wholly under the control of government through its control of the supply of land, which is restricted at the behest of the parties of the left.

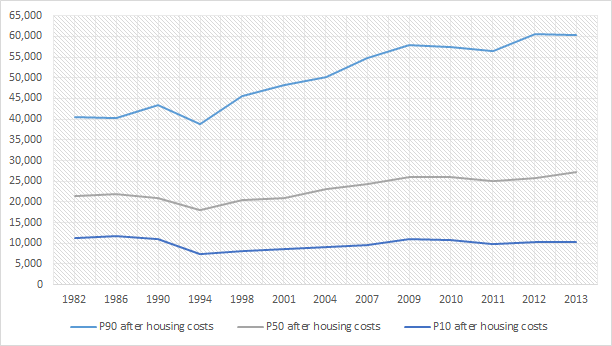
Figure 2: real equivalised household incomes (before and after housing costs): changes at the top of lowest income decile, New Zealand, 1982 to 2013

image

Source: Bryan Perry, Household incomes in New Zealand: Trends in indicators of inequality and hardship 1982 to 2013. Ministry of Social Development (July 2014), tables D.2 and D.4.

Figure 2 shows that real equivalised household income after housing costs has not grown and in fact has fallen for the bottom 10% of the income distribution in New Zealand.

It is the left-wing parties who oppose measures to reduce housing costs and and increase the supply of land through reforms to the Resource Management Act and the relaxation of the Auckland metropolitan urban limit.

Labour and the Greens are in effect keeping the poor poor to win middle-class votes.

Figure 3: real equivalised household incomes (before and after housing costs): changes at the top of the top, middle and lowest lowest income deciles, New Zealand, 1982 to 2013

image

Source: Bryan Perry, Household incomes in New Zealand: Trends in indicators of inequality and hardship 1982 to 2013. Ministry of Social Development (July 2014), tables D.2 in D.4.

Figure 3 shows that those in the middle and higher deciles, a political territory rich in swinging voters, are still doing well after housing costs. The parties of the left are collaborating with a middle-class home owning voter while betraying the working class and its aspirations from home ownership and quite simply affordable housing costs when they rent.

The increases for all groups may be understated by the inability of living standards measures to adequately account for new goods, product upgrades and rising life expectancies.

OECD starting a business rankings (New Zealand (1st) to Germany (114th)) – World Bank Doing Business rankings

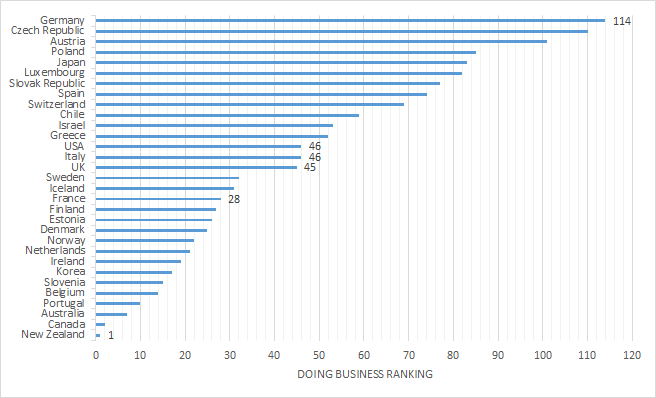
Figure 1: Starting a business rankings – World Bank Doing Business rankings, OECD countries, 2014

image

Source: Doing Business – Measuring Business Regulations – World Bank Group.

There is surprising wide range in the World Bank Doing Business ranking of the difficulty and delays in starting a business across the OECD.

Germany is ranked 114 from the world for starting a business. New Zealand is ranked first with the USA, Italy and the UK ranked in the mid 40s in the Doing Business database.

Richer is greener: environmentalists are Environmental Kuznets Curve deniers

The Kuznets environmental curve describes an empirical regularity between environmental quality and economic growth. Outdoor water, air and other pollution first worse and then improves as a country first experiences economic growth and development.

While many pollutants exhibit this pattern in the Kuznets environmental curve, peak pollution levels occur at different income levels for different pollutants, countries and time periods. John Tierney explains:

In dozens of studies, researchers identified Kuznets curves for a variety of environmental problems.

There are exceptions to the trend, especially in countries with inept governments and poor systems of property rights, but in general, richer is eventually greener.

As incomes go up, people often focus first on cleaning up their drinking water, and then later on air pollutants like sulphur dioxide.

As their wealth grows, people consume more energy, but they move to more efficient and cleaner sources — from wood to coal and oil, and then to natural gas and nuclear power, progressively emitting less carbon per unit of energy.

When I was living in Japan in the mid 1990s, they just completed a period of rapid operation of the Kuznets environmental curve. I was told by my professors at Graduate School that in the 1960s, cities and prefectures welcomed polluting industries because of the better paid jobs they offered. At that time, shipping companies used like to go to Tokyo because the pollution in Tokyo Bay was so bad that it would clean all the barnacles off their ships. That made them sail faster.

image

Japanese incomes and wages doubled over the course of the 1960s. The Japanese voter was now prepared to support stricter pollution standards and environmental controls.

In the early 1970s, the ruling LDP stole the long-standing environmental policies of their opponents in a big crack down on pollution because the country could now afforded them.

Plenty of developing countries are democracies now. Their people could demand through the ballot box higher environmental standards and clean tap water but they don’t because of its cost to economic development.

The environmental movement lives in a state of denial regarding the relationship between economic growth and environmental quality.

Doing business in Russia and Italy – World Bank rankings compared

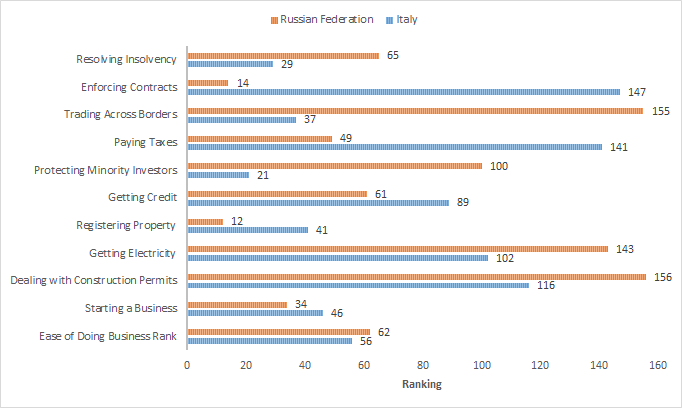
Figure 1: Doing Business rankings, Russia and Italy, 2014

image

Source: World Bank Doing Business 2015.

It is rather disturbing that it is a lot easier to register property and enforce contracts in Russia than in Italy and  far harder to pay your taxes in Italy. Once again, Italy’s saving grace is the ability to trade across borders Because of its membership of the European Union.

Legal systems and property rights in Greece and Russia – Index of Economic Freedom rankings compared

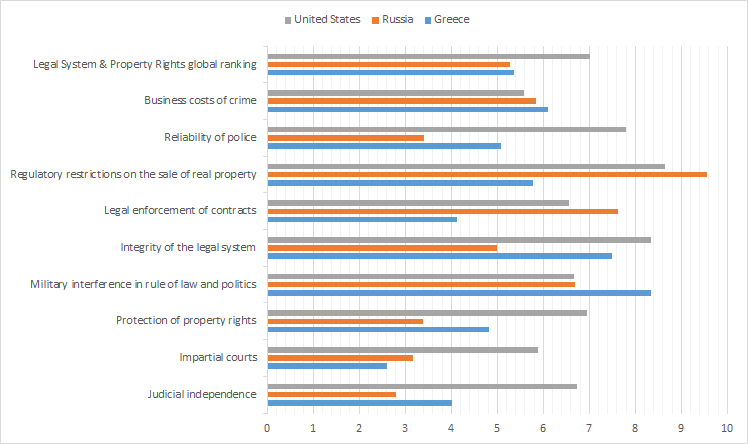
Figure 1: Index of Economic Freedom rankings for legal systems and property rights, Greece, Russia and USA, 2012

image

Source: Economic Freedom of the World – Annual Report 2014 | www.freetheworld.com.

Overall, there are not that many differences between Greece and Russia in the quality of their legal systems and property rights. Don’t go to the police in Russia and good luck trying to enforce contracts in Greece.

Doing business in the PIGS (Portugal, Italy, Greece and Spain) – World Bank rankings

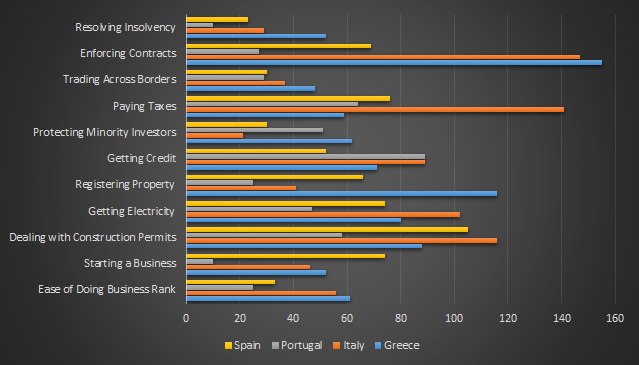
Figure 1: Doing Business rankings, PIGS, 2014

image

Source: World Bank Doing Business 2015.

All in all, Italy and Greece are a dog of a place to enforce a contract. The long-suffering taxpayer is better off paying taxes in Greece than in Italy! Not surprisingly, trading across borders is the greatest strength in doing business in the PIGS. The European Union does have some benefits.

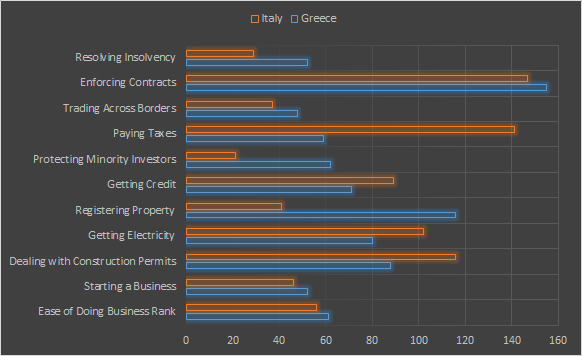
Figure 2: Doing Business rankings, Greece and Italy, 2014

image

Source: World Bank Doing Business 2015.

All in all, Italy and Greece are equally bad places to do business and Italy is much worse when it comes to taxes. About the only saving graces of Italy is the registration of property and the protection of minority interests in companies.

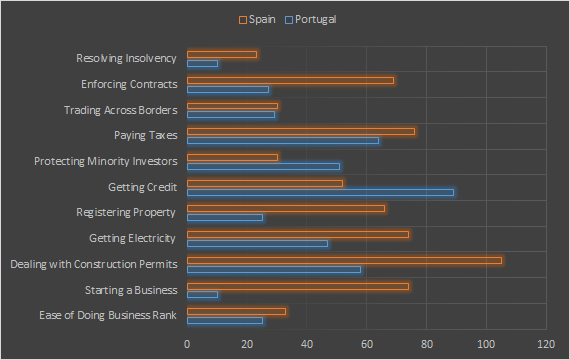
Figure 3: Doing Business rankings, Spain and Portugal, 2014

image

Source: World Bank Doing Business 2015.

Spain and in particular Portugal are much better places to do business than Italy and Greece.

Greece (61st) is ranked one above the Russia in the World Bank’s Doing Business Survey 2015

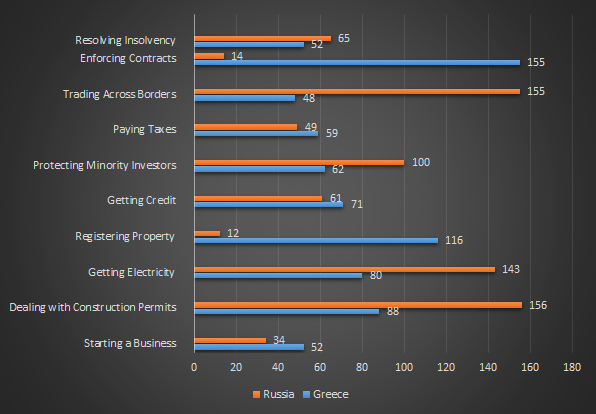
Figure 1: Greek and Russian Doing Business sub-rankings, 2015

image

Source: World Bank Doing Business 2015.

As long as you’re not in a construction or export business, and don’t mind waiting for your electricity, it’s better to do business in Russia than in Greece! The main difference between Russia and Greece is its membership of the European Union makes it easy to export?

In Russia, it’s easier to start a business, register property and enforce contracts than it is in Greece!

Is investor state dispute settlement a form of overseas development assistance?

Would objections to the Investor State Dispute Settlement provisions in the proposed Trans-Pacific Partnership wilt away if the adjudicating body was the International Court of Justice? The left-wing opponents of investor state dispute settlement genuflect at the very mention of the International Court of Justice and international law generally (unless it is international economic law).

Disputes over the provisions of European union treaties are adjudicated by the European Court of Justice. The judgements of that court brought by individuals against member states so annoy the British that it is a leading reason for many British wanting to leave the European Union and replace the Human Rights Act 1998 with a British Bill Of Rights policed by British courts rather than by the European Court of Justice and European human rights law.

It is routine for any treaty to have some provision for arbitration of disputes. This includes trade and investment treaties.

The World Trade Organisation treaty includes a dispute settlement provision with arbitrators based in Geneva. Some of the more than 400 cases heard have been motivated by discrimination against imports on the basis of a breached environmental protection policies of the importing country.

A number of countries want to ban imports that are produced in ways that upset them. Others want to include labour and environmental standards in trade agreements to impose developed country standards on developing countries in what is a new form of colonialism.

I have previously said that investor State Dispute Settlement provisions have no place in trade and investment treaties between democracies. I must now admit there are good reasons to have arbitration clauses in treaties between democracies.

The puzzle is why refer these trade and investment disputes to a little-known arbitration body adjunct to the World Bank rather than the far more prestigious International Court of Justice.

Perhaps the reason is both sides want an arbitrator who is not too strong and not too credible. It would look very bad if the International Court of Justice was to rule against you.

William Landes and Richard Posner contended that judicial independence maximises the value of legislative deals with interest groups by enhancing the durability of those deals.

Why no International Court of Commercial Law? When deciding what type in judiciary to enforce international trade bargains, the signatories may prefer a less credible adjudication and enforcement mechanism in case they want to opt out of it or chip around the decision.

The jurisdiction of the International Court of Justice is to settle, in accordance with international law, legal disputes submitted to it by special agreement and matters specifically provided for in treaties and conventions in force.

UN member states are the parties to any litigation but that doesn’t stop them raising cases on behalf of individuals. That said, organizations, private enterprises, and individuals cannot have their cases taken to the International Court, such as to appeal a national supreme court’s ruling. Only the states can bring the cases and become the defendants of the cases.

The International Court of Justice is different from the European Court of Justice because individuals cannot easily bring complaints before it. One of the causes of action before  the European Court of Adjusters is under European competition law over member states providing financial aid to industries.

Democratic countries with high levels of economic and  social integration, such as the  European union, do find it in advantage to set up a European wide Court to adjudicate disputes over rights under European law.

Why then would a democracy sign up to an investment protection treaty with a developing country? One reason is overseas development assistance.

Developing countries with corrupt and incompetent courts, politicians and bureaucracies sign international treaties as a way of assuring foreign investors and trading partners of some degree of security of their property rights and their ability to enforce contracts with suppliers and buyers.

By folding these assurances into trade treaties, the developing country has a stronger incentive to honour its promises. There will be domestic constituencies wanting to retain reciprocal export market access who will lobby for the honouring of the promises of legal protection to investors and businesses in their home country.

New Zealand signing up to the Trans-Pacific Partnership is an example of this form of overseas development assistance. Exporters and investors from the developing country who export and invest in New Zealand have another reason to support more secure property rights and better enforcement of contracts in their home country as a way of securing their treaty rights to export and invest in New Zealand.

The Left of the political spectrum should be keen on this form of overseas development considering their general belief in greatly increasing the amount spent on overseas development assistance. Rather than pay cash to the development country, the payment is in kind as reciprocal legal promises.

Trade treaties that include investor state dispute settlement are forms of governance assistance to developing countries. The reciprocal exchange of promises about investor protection and the enforcement of contracts and property rights improves the quality of governance in the developing country.

The countries most likely to be subject to investor state dispute settlement are those with weaker governance. Even in the European Union, the member states most likely to be sued are former communist countries. The most common course of action was the cancellation of a licence or permit.

Investor state dispute settlement clauses are no different from any other international treaty include environmental and human rights treaties. All these treaties require countries to give up part of their sovereignty.

Democracies give up their sovereignty in investor state dispute settlement in the hope that developing country partners to the treaty will improve the development potential of their country through better governance and more secure property rights.

That is an overseas development aid objective the Left of the political spectrum should support, but it does not. The Left of the political spectrum is happy to use trade agreements to impose developed country labour and environmental standards on poor countries desperate for access to rich country markets, but is not willing to give up anything in return.

Once were British

How many of each of the threatened species still exist?

Which countries benefit from having the common law?

via 40 maps that explain the world – The Washington Post.

Ease of doing business across the European Union is rather variable

The Rise and Rise of the Super Working Rich

The rise of the rentiers is nothing new. What is new is the degree of financial globalization and liberalization that has supercharged the fortunes of the super-wealthy even beyond robber baron levels. But it’s no mystery how to reverse this. It’s a matter of setting better rules for markets and taxing earners at the top a bit more.

In the course of a deranged rant against the entrepreneurs in society, the Atlantic collected an excellent set of information suggesting that the working rich have replaced rentiers as the super-rich. Rentiers are the idle rich.  A rentier is a person or entity receiving income derived from patents, copyrights, interest, etc.

In The Evolution of Top Incomes: A Historical and International Perspective (NBER Working Paper No. 11955), Thomas Piketty and Emmanuel Saez concluded that:

While top income shares have remained fairly stable in Continental European countries or Japan over the past three decades, they have increased enormously in the United States and other English speaking countries.

This rise in top income shares is not due to the revival of top capital incomes, but rather to the very large increases in top wages (especially top executive compensation). As a consequence, top executives (the “working rich”) have replaced top capital owners at the top of the income hierarchy over the course of the twentieth century…

The Twitter Left claim that the surge in top compensation in the United States is attributable to an increased ability of top executives to set their own pay and to extract rents at the expense of shareholders. Obviously, from the chart below the pay the top 0.1% goes up and down with the share market. Top  wages do not seem to have any independent power to dupe shareholders into overpaying them in bad times.

Xavier Gabaix and Augustin Landier found back in 2008 that what a major company’s CEO earns is directly proportional to the size of the firm that they are responsible for running. Executive compensation closely track the evolution of average firm value. During 2007 – 2009, firm value decreased by 17%, and CEO pay by 28%. During 2009-2011, firm value increased by 19% and CEO pay by 22%.

Xavier Gabaix and Augustin Landier also found that compensation for executives has risen with the market capitalization. From 1980 to 2003, the average value of the top 500 companies rose by a factor of six. Two commonly used indexes of chief executive compensation show close to a proportional six-fold matching increase.

Better executive decisions create more economic value. If the number of big companies is greater than the number of good chief executives, competitive bidding will push up executive pay to reflect the value of the talent that is available.

What happens to share prices when there is a surprise CEO resignation? Up or down? Apple went up and down in billions on news of Steve Jobs’ health.

When Hewlett Packard’s CEO Mark Hurd resigned unexpectedly, the value of HP stock dropped by about $10 billion! This makes his $30 million in annual compensation a bargain for shareholders. The fall in share price represents the difference between what the market expected from Hurd as Hewlett Packard’s CEO and what the market expects from his successor. Was Hurd under-paid?

There is an easy way to test for whether top executives cheat public shareholders. Compare the pay of large private companies, and public companies with a large or a few share holders, with public companies with diffuse share holdings. Private equity typically also pay its top executives very well, even though the capacity to dupe public shareholders are not a factor.

The burst of takeovers and leverage buyouts in the 1980s were very much driven by opportunities to profit from reducing corporate slack and downsizing flabby corporate headquarters of large publicly listed companies.

The response of the Left over Left of the day was support regulation to stop these mergers and takeovers rather than applauding them as giving lazy capitalists their comeuppance. This regulation undermined the market the corporate control rather than strengthened it as Michael Jensen explains:

This political activity is another example of special interests using the democratic political system to change the rules of the game to benefit themselves at the expense of society as a whole.

In this case, the special interests are top-level corporate managers and other groups who stand to lose from competition in the market for corporate control. The result will be a significant weakening of the corporation as an organizational form and a reduction in efficiency.

Central to the hypothesis of the Twitter Left of CEOs overpaying themselves is there is free cash within the business they pocket in pay rises, fringe benefits and lavished corporate headquarters rather than pay out in dividends or invest in profitable investments.

The interests and incentives of managers and shareholders frequently conflict over the optimal size of the firm and the payment of free cash to shareholders. What to pay the top executives is a minor manifestation of this common entrepreneurial difference of opinion the future of the business.

These conflicts in entrepreneurial judgements are severe in firms with large free cash flows–more cash than profitable investment opportunities. Jensen defines free cash flow as follows:

Free cash flow is cash flow in excess of that required to fund all of a firm’s projects that have positive net present values when discounted at the relevant cost of capital. Such free cash flow must be paid out to shareholders if the firm is to be efficient and to maximize value for shareholders.

Payment of cash to shareholders reduces the resources under managers’ control, thereby reducing managers’ power and potentially subjecting them to the monitoring by the capital markets that occurs when a firm must obtain new capital. Financing projects internally avoids this monitoring and the possibility that funds will be unavailable or available only at high explicit prices.

Michael Jensen developed a theory of mergers and takeovers based on free cash flows that explains:

  1. the benefits of debt in reducing agency costs of free cash flows,
  2. how debt can substitute for dividends,
  3. why diversification programs are more likely to generate losses than takeovers or expansion in the same line of business or liquidation-motivated takeovers,
  4. why bidders and some targets tend to perform abnormally well prior to takeover.

Michael Jensen noted that free cash flows allowed firms’ managers to finance projects earning low returns which, therefore, might not be funded by the equity or bond markets. Examining the US oil industry,  which had earned substantial free cash flows in the 1970s and the early 1980s, he wrote that:

[the] 1984 cash flows of the ten largest oil companies were $48.5 billion, 28 percent of the total cash flows of the top 200 firms in Dun’s Business Month survey.

Consistent with the agency costs of free cash flow, management did not pay out the excess resources to shareholders. Instead, the industry continued to spend heavily on [exploration and development] activity even though average returns were below the cost of capital.

Jensen also noted a negative correlation between exploration announcements and the market valuation of these firms—the opposite effect to research announcements in other industries. Not surprisingly, after a successful corporate takeover, there is major changes to realise the untapped benefits they saw in the company that the incumbent management were not seizing capturing:

Corporate control transactions and the restructurings that often accompany them can be wrenching events in the lives of those linked to the involved organizations: the managers, employees, suppliers, customers and residents of surrounding communities.

Restructurings usually involve major organizational change (such as shifts in corporate strategy) to meet new competition or market conditions, increased use of debt, and a flurry of recontracting with managers, employees, suppliers and customers.

All modern theories of the focus in part or in full on reducing opportunistic behaviour, cheating and fraud in employment and commercial relationships. The market the corporate control, and mergers and takeovers realise large benefits from displacing underperforming manager teams. Premiums in hostile takeover offers historically exceed 30 percent on average. Acquiring-firm shareholders on average earn about 4 percent in hostile takeovers and roughly zero in mergers.

In terms of corporate control, Eugene Fama divides firms into two types:  the managerial firm, and the entrepreneurial firm.

The entrepreneurial firms are owned and managed by the same people (Fama and Jensen 1983b). Mediocre personnel policies and sub-standard staff retention practices within entrepreneurial firms are disciplined by these errors in judgement by owner-managers feeding straight back into the returns on the capital that these owner-managers themselves invested. Owner-managers can learn quickly and can act faster in response the discovery of errors in judgement. The drawback of entrepreneurial firms is not every investor wants to be hands-on even if they had the skills and nor do they want to risk being undiversified.

The owners of a managerial firm advance, withdraw, and redeploy capital, carry the residual investment risks of ownership and have the ultimate decision making rights over the fate of the firm (Klein 1999; Foss and Lien 2010; Fama 1980; Fama and Jensen 1983a, 1983b; Jensen and Meckling 1976).

Owners of a managerial firm, by definition, will delegate control to expert managerial employees appointed by boards of directors elected by the shareholders (Fama and Jensen 1983a, 1983b). The owners of a managerial firm will incur costs in observing with considerable imprecision the actual efforts, due diligence, true motives and entrepreneurial shrewdness of the managers and directors they hired (Jensen and Meckling 1976; Fama and Jensen 1983b).

Owners need to uncover whether a substandard performance is due to mismanagement, high costs, paying the employees too much or paying too little, excessive staff turnover, inferior products, or random factors beyond the control of their managers (Jensen and Meckling 1976; Fama and Jensen 1983b, 1985).

Many of the shareholders in managerial firms have too small a stake to gain from monitoring managerial effort, employee performance, capital budgets, the control of costs and the stinginess or generosity of wage and employment policies (Manne 1965; Fama 1980; Fama and Jensen 1983a, 1983b; Williamson 1985; Jensen and Meckling 1976). This lack of interest by small and diversified investors does not undo the status of the firm as a competitive investment nor introduce slack in the monitoring of payments to top executives.

Large firms are run by managers hired by diversified owners because this outcome is the most profitable form of organisation to raise capital and then find the managerial talent to put this pool of capital to its most profitable uses (Fama and Jensen 1983a, 1983b, 1985; Demsetz and Lehn 1985; Alchian and Woodward 1987, 1988).

More active investors will hesitate to invest in large managerial firms whose governance structures tolerate excessive corporate waste and do not address managerial slack and  and overpaid executives. Financial entrepreneurs will win risk-free profits from being alert and being first to buy or sell shares in the better or worse governed firms that come to their notice.

The risks to dividends and capital because of manifestations of corporate waste, reduced employee effort, and managerial slack and aggrandisement in large managerial firms are risks that are well known to investors (Jensen and Meckling 1976; Fama and Jenson 1983b). Corporate waste and managerial slack also increase the chances of a decline in sales and even business failure because of product market competition (Fama 1980; Fama and Jensen 1983b).

Investors will expect an offsetting risk premium before they buy shares in more ill-governed managerial firms. This is because without this top-up on dividends, they can invest in plenty of other options that foretell a higher risk-adjusted rate of return. The discovery of monitoring or incentive systems that induce managers to act in the best interest of shareholders are entrepreneurial opportunities for pure profit (Fama and Jensen 1983b, 1985; Alchian and Woodward 1987, 1988; Demsetz 1983, 1986; Demsetz and Lehn 1985; Demsetz and Villalonga 2001).

Investors will not entrust their funds to who are virtual strangers unless they expect to profit from a specialisation and a division of labour between asset management and managerial talent and in capital supply and residual risk bearing (Fama 1980; Fama and Jensen 1983a, 1983b; Demsetz and Lehn 1985). There are other investment formats that offer more predictable, more certain rate of returns.

Competition from other firms will force the evolution of devices within the firms that survive for the efficient monitoring the performance of the entire team of employees and of individual members of those teams as well as managers (Fama 1980, Fama and Jensen 1983a, 1983b; Demsetz and Lehn 1985). These management controls must proxy as cost-effectively as they can having an owner-manager on the spot to balance the risks and rewards of innovating.

The reward for forming a well-disciplined managerial firm despite the drawbacks of diffuse ownership is the ability to raise large amounts in equity capital from investors seeking diversification and limited liability (Demsetz 1967; Jensen and Meckling 1976; Fama 1980; Fama and Jensen 1983b; Demsetz and Lehn 1985). Portfolio investors may know little about each other and only so much about the firm because diversification and limited liability makes this knowledge less important (Demsetz 1967; Jensen and Meckling 1976; Alchian and Woodward 1987, 1988).

It is unwise to suppose that portfolio investors will keep relinquishing control over part of their capital to virtual strangers who do not manage the resources entrusted to them in the best interests of the shareholders (Demsetz 1967; Williamson 1985; Fama 1980, 1983b; Alchian and Woodward 1987, 1988).

Managerial firms who are not alert enough to develop cost effective solutions to incentive conflicts and misalignments will not grow to displace rival forms of corporate organisation and methods of raising equity capital and loans, allocating legal liability, diversifying risk, organising production, replacing less able management teams, and monitoring and rewarding employees (Fama and Jensen 1983a, 1983b; Fama 1980; Alchian 1950).

Entrepreneurs will win profits from creating corporate governance structures that can credibly assure current and future investors that their interests are protected and their shares are likely to prosper (Fama 1980; Fama and Jensen 1983a, 1983b, 1985; Demsetz 1986; Demsetz and Lehn 1985). Corporate governance is the set of control devices that are developed in response to conflicts of interest in a firm (Fama and Jensen 1983b).

At bottom, the private sector is highly successful designing forms of organisation that allow large sums of money, billions of dollars to be raised in the capital market and entrusted to management teams.

via The Rise and Rise of the Super-Rich – The Atlantic and How the Richest 400 People in America Got So Rich – The Atlantic.
Senator Warren made a good case against Investor-State Dispute Settlement in the TPP

In the Washington Post a few months ago, Senator Elizabeth Warren made a balanced case against investor state dispute settlement, not only in the Trans-Pacific Partnership. But in any trade agreement.

Apart from a few rushes of blood in rhetoric to appeal to her base, she made reasoned arguments, good use of history, and put up constructive alternatives to what she was criticising. Furthermore, she put forward arguments that appealed to every point in the political spectrum. The Left over Left critics of investor state disputes settlement clauses in trade agreements in New Zealand never do that.

She echoed arguments I have made the at investor state disputes settlement clauses have no place in trade agreements between liberal democracies.

clip_image002

Liberal democracies have independent courts and honest politics where everyone gets a fair go. That means sometimes you’re on the losing side of politics, but you as free to persuade the majority that they are mistaken. That is democracy in action: sometimes you win, sometimes you lose and there is an election in a few years where you can get another go.

New Zealand has a Closer Economic Relations Agreement with Australia. One provision is a requirement that in most cases New Zealanders are treated the same as Australians under Australian law.

To explain this, some years ago, a New Zealand television production company successfully sued the Australian television regulator to have New Zealand made television shows recognised as Australian content under the 50% Australian content regulations for free-to-air television in Australia.

Note the New Zealand business sued in the Federal Court of Australia and won. They had their day in court.

Senator Warren makes the point that if a business in the USA is unhappy with a regulation, they can challenge by normal democratic and legal means, which investor state disputes settlement undermines:

If a foreign company that makes the toxic chemical opposes the law, it would normally have to challenge it in a U.S. court. But with ISDS, the company could skip the U.S. courts and go before an international panel of arbitrators. If the company won, the ruling couldn’t be challenged in U.S. courts, and the arbitration panel could require American taxpayers to cough up millions — and even billions — of dollars in damages.

Senator Warren also provides a good history of the emergence of investor state disputes settlement and the relevance of that history to contemporary developments:

But after World War II, some investors worried about plunking down their money in developing countries, where the legal systems were not as dependable. They were concerned that a corporation might build a plant one day only to watch a dictator confiscate it the next. To encourage foreign investment in countries with weak legal systems, the United States and other nations began to include ISDS in trade agreements.

Investor state disputes settlement were indeed created to protect businesses that did not have robust democracies and legal systems. Would be international investors in one of these countries were promised international redress if there was a coup, a takeover of their investments or some other unforeseen negative impact because sovereign risk.

She then asked why are these provisions in trade agreements with liberal democracies where they have no relevance:

Those justifications don’t make sense anymore, if they ever did. Countries in the TPP are hardly emerging economies with weak legal systems. Australia and Japan have well-developed, well-respected legal systems, and multinational corporations navigate those systems every day, but ISDS would pre-empt their courts too.

Senator Warren also makes a good point that investor state disputes settlement undermines competition between legal jurisdictions and the rewards for having a sound legal system:

…to the extent there are countries that are riskier politically, market competition can solve the problem. Countries that respect property rights and the rule of law — such as the United States — should be more competitive, and if a company wants to invest in a country with a weak legal system, then it should buy political-risk insurance.

Political risk is is an entrepreneurial opportunity for the insurance market. The World Bank’s Multilateral Investment Guarantee Agency provides insurance to those investing in developing countries against expropriation (including indirect expropriation), as well as acts of war and terrorism. Export Finance schemes of many governments offer political risk Insurance. Anyone who travels in the less safe countries of the world routinely buys travel insurance.

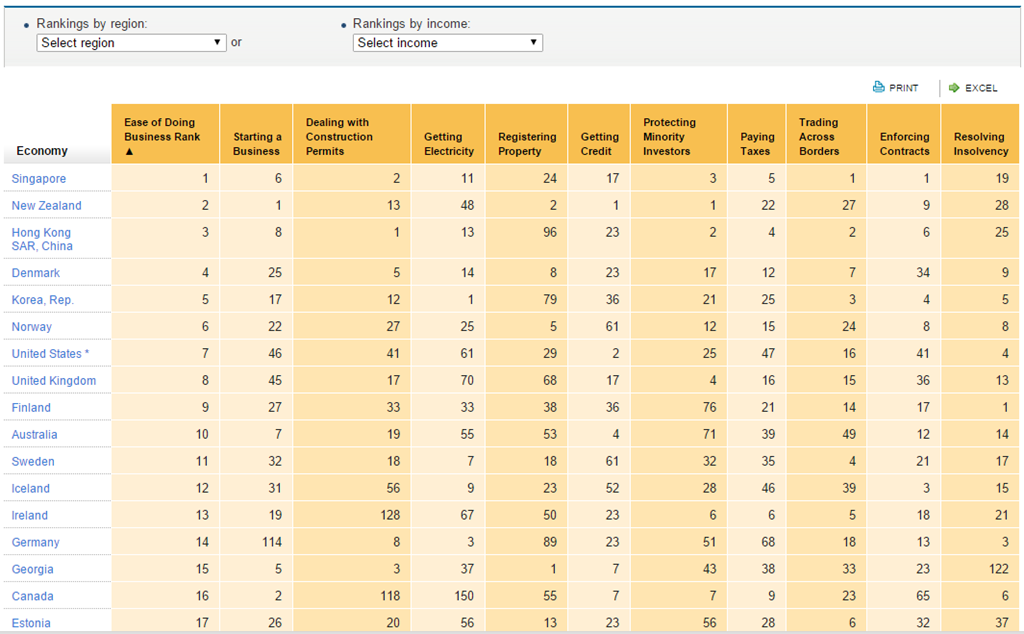
The World Bank puts out an annual index on ease of doing business in every country of the world so foreign investors can’t say they won’t warned of the risks they were taking for the profits they sought.

image

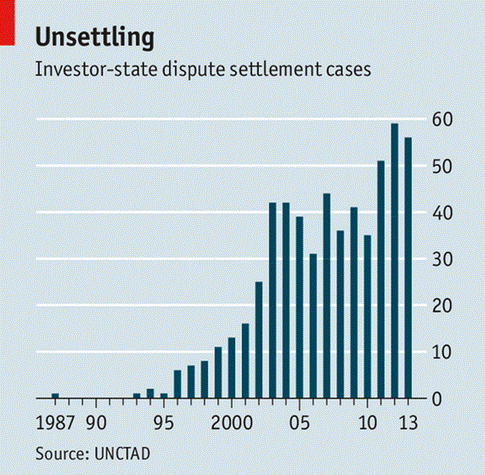
Investor state disputes that were indeed referred to international arbitration used to be rare. Now they are more common as Senator Warren explains:

From 1959 to 2002, there were fewer than 100 ISDS claims worldwide. But in 2012 alone, there were 58 cases.

Recent cases include a French company that sued Egypt because Egypt raised its minimum wage, a Swedish company that sued Germany because Germany decided to phase out nuclear power after Japan’s Fukushima disaster, and a Dutch company that sued the Czech Republic because the Czechs didn’t bail out a bank that the company partially owned. U.S. corporations have also gotten in on the action: Philip Morris is trying to use ISDS to stop Uruguay from implementing new tobacco regulations intended to cut smoking rates.

In a response to Senator Warren’s op-ed, Gary Clyde Hufbauer said:

…only 13 ISDS cases have been brought to judgment against the United States.  The United States has not lost a single case.

Why? Because the United States does not expropriate private property without compensation, and the United States does not enact arbitrary or discriminatory laws against foreign firms. Contrary to what the Senator implies, American taxpayers have not had to cough up millions and even billions of dollars in damages. They have not had to cough up anything.

The best part of Senator Warren’s op-ed is when she appeals to all points of the political spectrum based on arguments that do indeed appealed to them:

Conservatives who believe in U.S. sovereignty should be outraged that ISDS would shift power from American courts, whose authority is derived from our Constitution, to unaccountable international tribunals. Libertarians should be offended that ISDS effectively would offer a free taxpayer subsidy to countries with weak legal systems. And progressives should oppose ISDS because it would allow big multinationals to weaken labour and environmental rules.

Senator Warren did make a good case against investor state disputes settlement, particularly between liberal democracies. Foreign investors should take their chances in domestic politics and the courts like the rest of us. They’ve invested in a liberal democracy with independent courts, honest politicians and a commitment to a market economy.

Investor state disputes settlement clauses in trade agreements allow foreign investors to sue the host country for laws, policies, or court decisions they find objectionable. This gives foreign investors more rights than local investors; more influence than local citizens. That is contrary to equality before the law, which is the essence of liberalism.

The point that the Twitter Left rarely makes against investor state disputes settlement, and Senator Warren goes a way towards making is the shield offered by investor state disputes settlement clauses against predatory, corrupt governments in underdeveloped countries, many of which were socialist kleptocracies, has become a sword against regulations that arise in any liberal democracy that were sought and obtained through normal democratic means.

The Australian Productivity Commission held a public inquiry into regional and bilateral trade agreements in 2010. The commission specifically addressed investor state disputes settlement in its subsequent report:

1. There does not appear to be an underlying economic problem that necessitates the inclusion of ISDS provisions within agreements. Available evidence does not suggest that ISDS provisions have a significant impact on investment flows.

2. Experience in other countries demonstrates that there are considerable policy and financial risks arising from ISDS provisions.

The Productivity Commission concluded that investor state dispute settlement provisions are just not worth bargaining coin:

Nor, in the Commission’s assessment, is it advisable in trade negotiations for Australia to expend bargaining coin to seek such rights over foreign governments, as a means of managing investment risks inherent in investing in foreign countries. Other options are available to investors.

The Australian Productivity Commission was quite right to question the advantages of setting up a preferential legal system for anyone:

…a bilateral arrangement with Australia to provide a ‘preferential legal system’ for Australian investors is unlikely to generate the same benefits for that country than if its legal system was developed on a domestic non-preferential basis.

To the extent that secure legal systems facilitate investment in a similar way that customs and port procedures facilitate goods trade, there may be a role for developed nations to assist through legal capacity building to develop stable and transparent legal and judicial frameworks.

When the Left over Left usually argues against investor state disputes settlement provisions they get so carried away with the conspiratorial rhetoric that they overlook a much better argument.

Investor state disputes settlement provisions are bad deal from liberal democracies. Liberal democracies with the rule of law, a market economy and private property rights offer ample protections to any foreign investor.

In trade agreements with less democratic countries, the need for reciprocal promises may not be worth the price when there are other options for investment protection, such as political risk insurance.

The question must be asked as to who lobbies for these agreements considering how much is opposition they provoke, and how useful they are as a mobilisation tool for the Twitter Left in their relentless campaign against lower prices and higher living standards.

Previous Older Entries Next Newer Entries

David Andolfatto

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Monetary Non-Neutrality

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Reason Magazine

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Coyote Blog

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Thoughts from the North

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Fardels Bear

A History of the Alt-Right

Vincent Geloso

Econ Prof at George Mason University, Economic Historian, Québécois

Bassett, Brash & Hide

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Truth on the Market

Scholarly commentary on law, economics, and more

The Undercover Historian

Beatrice Cherrier's blog

Matua Kahurangi

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Temple of Sociology

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Velvet Glove, Iron Fist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Why Evolution Is True

Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.

NoTricksZone

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Homepaddock

A rural perspective with a blue tint by Ele Ludemann

Kiwiblog

DPF's Kiwiblog - Fomenting Happy Mischief since 2003

The Dangerous Economist

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Watts Up With That?

The world's most viewed site on global warming and climate change

The Logical Place

Tim Harding's writings on rationality, informal logic and skepticism

Doc's Books

A window into Doc Freiberger's library

The Risk-Monger

Let's examine hard decisions!

Uneasy Money

Commentary on monetary policy in the spirit of R. G. Hawtrey

Barrie Saunders

Thoughts on public policy and the media

Liberty Scott

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Point of Order

Politics and the economy

James Bowden's Blog

A blog (primarily) on Canadian and Commonwealth political history and institutions

Science Matters

Reading between the lines, and underneath the hype.

Peter Winsley

Economics, and such stuff as dreams are made on

A Venerable Puzzle

"The British constitution has always been puzzling, and always will be." --Queen Elizabeth II

The Antiplanner

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

Bet On It

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

History of Sorts

WORLD WAR II, MUSIC, HISTORY, HOLOCAUST

Roger Pielke Jr.

Undisciplined scholar, recovering academic

Offsetting Behaviour

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

JONATHAN TURLEY

Res ipsa loquitur - The thing itself speaks

Conversable Economist

In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”

The Victorian Commons

Researching the House of Commons, 1832-1868

The History of Parliament

Articles and research from the History of Parliament Trust

Books & Boots

Reflections on books and art

Legal History Miscellany

Posts on the History of Law, Crime, and Justice

Sex, Drugs and Economics

Celebrating humanity's flourishing through the spread of capitalism and the rule of law

European Royal History

Exploring the Monarchs of Europe

Tallbloke's Talkshop

Cutting edge science you can dice with

Marginal REVOLUTION

Small Steps Toward A Much Better World

NOT A LOT OF PEOPLE KNOW THAT

“We do not believe any group of men adequate enough or wise enough to operate without scrutiny or without criticism. We know that the only way to avoid error is to detect it, that the only way to detect it is to be free to inquire. We know that in secrecy error undetected will flourish and subvert”. - J Robert Oppenheimer.