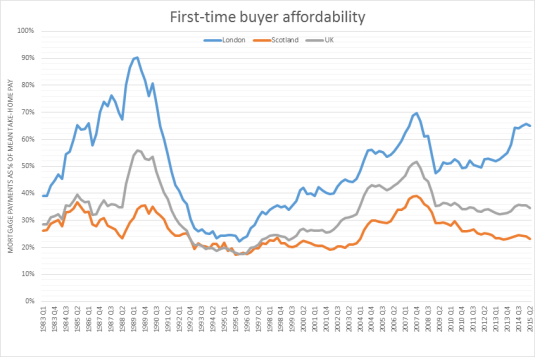
Many of the Twitter Left who voted in Jeremy Corbyn to lead the British Labour Party into what will be a self-inflicted electoral oblivion have no adult memory of paying high mortgage payments when there was high inflation.
Those who have escaped the overweening conceit of youth still have raw memories of high inflation and high mortgage payments and that was when housing was much, much cheaper.
When President Clinton appointed Alan Blinder to be deputy chair of the Fed, his big hope was to find out what Alan Greenspan really thought rather than the public facade of gobbledygook. The term Fedspeak (also known as Greenspeak) is what Alan Blinder called "a turgid dialect of English" used by Federal Reserve Board chairmen in making wordy, vague, and ambiguous statements. Greenspan described it this way:
To Blinder’s astonishment, Alan Greenspan spoke just the same as he did at monetary policy meetings of the Fed as he did in public! Blinder never disagreed fundamentally with Greenspan about monetary policy.
Two of my brothers studied economics in the early 1970s and then went on to different paths in law and computing respectively. If Greg Mankiw is right, my two older brothers could happily conduct a conversation with a modern central banker. Their 1970s macroeconomics, albeit batting for memory, would be enough for them to hold their own.
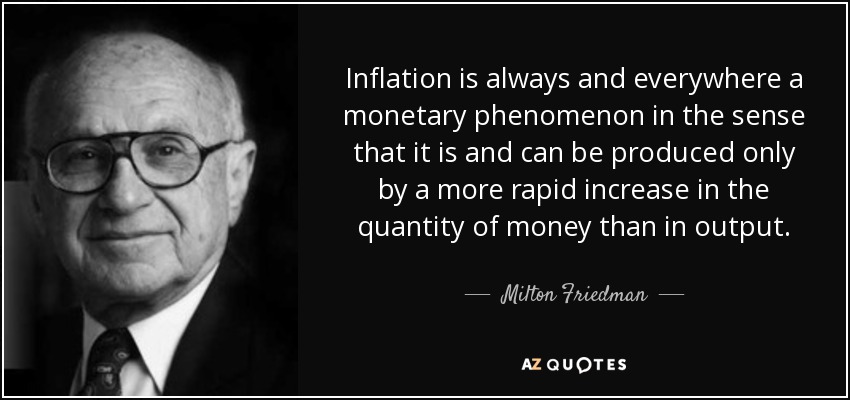
I would spend my time arguing with a central banker that Milton Friedman may be right and central banks should be replaced with a computer. The success of inflation targeting is forcing me to think more deeply about that position. In particular the rise of pension fund socialism means that most voters are very adverse to inflation because of their retirement savings and that is before you consider housing costs are much largest proportions of household budgets these days.
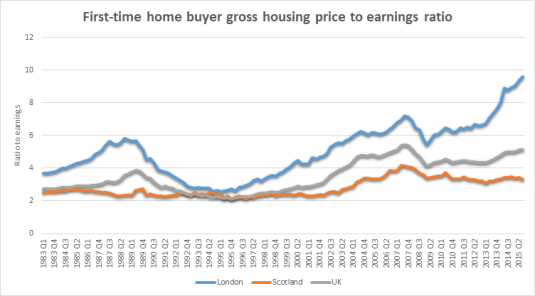
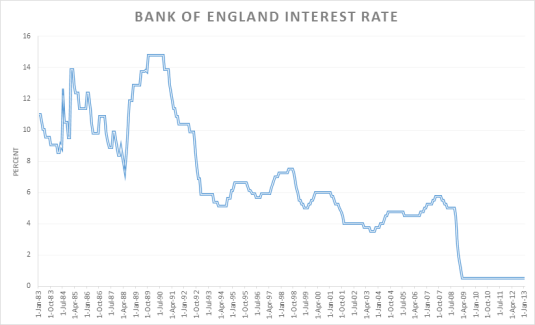
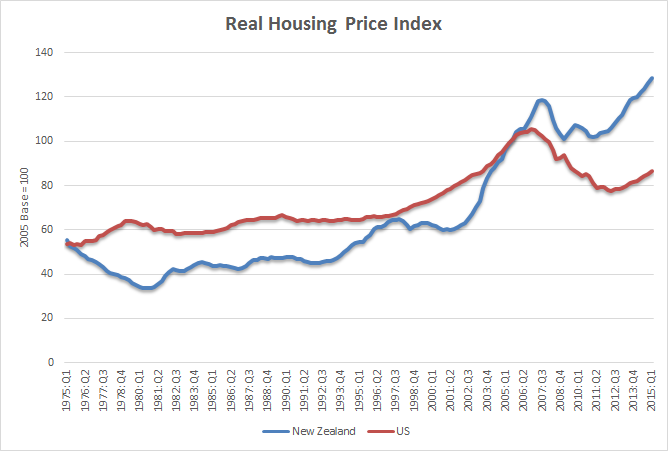
Mortgage interest rates were last in the double digits in the late 1980s and early 1990s. Since then, housing prices have exploded in New Zealand and barely paused for the recession in the wake of the Global Financial Crisis.
With house prices and mortgages several times what they used to be, the ability for any household income to absorb the sudden return of high mortgage interest rates because of a return of even moderate CPI inflation and double-digit mortgage rates is well-nigh impossible, politically.
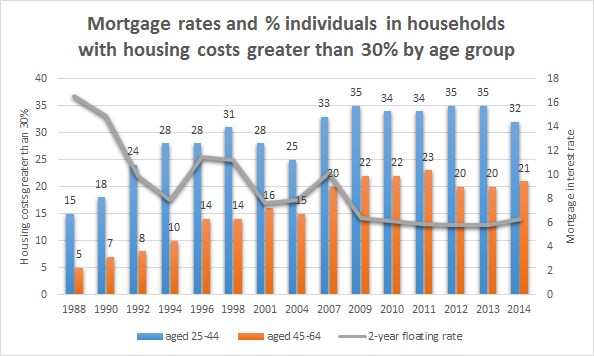
The chart above shows that the number of 25 to 44-year-olds in New Zealand who have more than 30% of their income going to housing expenses has doubled since 1988 to nearly a third of all households. The number of 45 to 64-year-olds who pay more than 30% of their income in housing expenses has quadrupled to 20%. That is a lot of voters who would be offended by mismanagement of monetary policy.
None of these households would have much left over to absorb an increasing mortgage interest rates. That is very different political arithmetic too the last time both mortgage rates and CPI inflation were in double digits, which was more than 20 years ago. Not many New Zealanders under the age of 40 or 45 have an adult memory of high inflation and high mortgage rates.
Why Evolution is True is a blog written by Jerry Coyne, centered on evolution and biology but also dealing with diverse topics like politics, culture, and cats.
In Hume’s spirit, I will attempt to serve as an ambassador from my world of economics, and help in “finding topics of conversation fit for the entertainment of rational creatures.”





Recent Comments