Human Capital, Development, and Growth | Lars Peter Hansen, Edward Glaeser, Claudia Goldin and Robert Lucas
16 Nov 2014 Leave a comment
in development economics, economic growth, Gary Becker, growth disasters, growth miracles, history of economic thought, human capital, labour economics, law and economics, property rights Tags: Claudia Goldin, Edward Glaeser, Gary Becker, Robert Lucas
Euroland and Japan compared since 2008
16 Nov 2014 Leave a comment
in budget deficits, business cycles, economic growth, global financial crisis (GFC), great recession Tags: Euroland, great recession, Japan, lost decades
The Greek great depression
15 Nov 2014 Leave a comment
in Euro crisis, global financial crisis (GFC), great depression, great recession, macroeconomics, politics Tags: euro crisis, Euroland, Greece

Europe’s dismal economy
15 Nov 2014 Leave a comment
in applied welfare economics, business cycles, Euro crisis, global financial crisis (GFC), great recession, macroeconomics Tags: Euroland, Euros crisis


If you’re so smart, why aren’t you rich: Deirdre McCloskey on economists as forecasters
10 Nov 2014 1 Comment

Policy bubble alert: R&D is an investment and like all investments, it must be cost justified
07 Nov 2014 Leave a comment

Average Marginal Income Tax Rates for New Zealand, 1907-2009 (WP 12/04) — The Treasury – New Zealand
07 Nov 2014 Leave a comment
in applied price theory, fiscal policy, politics - New Zealand Tags: Marginal tax rates, public economics, public finance

Note: Average marginal tax rate calculations exclude the impact of ACC levies, the Benefit system and the Family Tax Credit (FTC) system which, at various times since the 1970s, involved lump sum transfers to lower income families with children that were withdrawn at higher income levels at rates of up to 30c/$, thereby adding to effective MTRs.
Comment: The average marginal tax rate has been pretty stable in New Zealand since about 1990 excepting for a drop in the late 1990s and then an increase in 1999.
via http://www.treasury.govt.nz/publications/research-policy/wp/2012/12-04

Romer and Romer vs. Reinhart and Rogoff – MoneyBeat – WSJ
01 Nov 2014 Leave a comment
in business cycles, Euro crisis, global financial crisis (GFC), great depression, great recession, macroeconomics Tags: financial crises, GFC
Identifying financial crises after the fact is problematic: researchers will disagree on what their characteristics were, when they started and ended, and what actually counts as a crisis. This is particularly true of crises before World War II or involving developing economies, for which accurate data are harder to come by.
So the Romers created a measure of financial distress based on real-time accounts of developed-economy conditions prepared semiannually by the Organisation for Economic Co-Operation and Development between 1967 and 2007. And to check that the OECD wasn’t for some reason off-base on conditions, they crosschecked it with central bank annual reports and articles in The Wall Street Journal.
They then scored the severity of financial conditions from zero to 15, thus avoiding quibbles over what is and isn’t a crisis and allowing for more precise readings of economic effects.
Their finding: Declines in economic output, as measured by gross domestic product and industrial production, following crises were on average moderate and often short-lived. There was a lot of variation in outcomes, so there was nothing cut and dried about how economies respond to crises…
via Romer and Romer vs. Reinhart and Rogoff – MoneyBeat – WSJ.
Romers’ work suggests the poor performance of economies around the world in the wake of the 2008 financial crisis shouldn’t be cast as inevitable. In The Current Financial Crisis: What Should We Learn From the Great Depressions of the 20th Century? de Cordoba and Kehoe note that:
Kehoe and Prescott [2007] conclude that bad government policies are responsible for causing great depressions. In particular, they hypothesize that, while different sorts of shocks can lead to ordinary business cycle downturns, overreaction by the government can prolong and deepen the downturn, turning it into a depression.
An Open Letter to Paul Krugman | David K. Levine
31 Oct 2014 3 Comments
in budget deficits, business cycles, comparative institutional analysis, economics of religion, fiscal policy, global financial crisis (GFC), great recession, macroeconomics

Policy bubbles alert: Innovation is a market process of discovery, diffusion, learning by using, entrepreneurial experimentation and decentralised adaptation
31 Oct 2014 Leave a comment

Some graphs on the great deviation on both sides of the Atlantic
31 Oct 2014 Leave a comment
in economic growth, Euro crisis, fiscal policy, global financial crisis (GFC), great depression, macroeconomics Tags: Eurosclerosis, GFC, Great Geviation, great recession
Figure 1: Actual and potential GDP in the US

Sources: Congressional Budget Office, Bureau of Economic Analysis
Figure 2: Actual and potential GDP in the Eurozone

Sources: IMF World Economic Outlook Databases, Bloomberg
HT: Larry Summers
Friday graph: why Ireland is broke
31 Oct 2014 5 Comments
in fiscal policy, global financial crisis (GFC), macroeconomics, monetary economics Tags: GFC, Ireland
I am planning to blog on why the Irish economic crisis of recent years was caused exclusively by government, and in particular, government responses that made an ordinary recession into a depression

This is a graph courtesy of the Institute of Public Affairs in Melbourne, an impressive Australian thinktank.
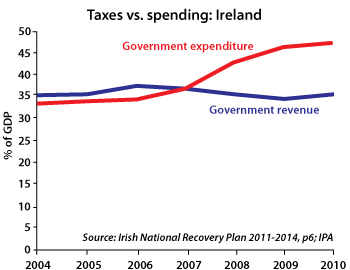
It comes from the Irish government’s own 140 page ‘National Recovery Plan‘ published last week.
It is amazing reading.
- From 2000 to 2009 average public sector salaries increased 59%
- In 2004, 34% of income earners were exempt from tax. In 2010, 45% were exempt
- In 2007 property taxes generated 6.7 billion euros. In 2010 that figure will be 1.6 billion
- In 2009 interest on government debt was 8% of tax revenues. In 2014 it will be 20%.
Naysayers try to tell you that the Celtic Tiger was a myth and that free-market policies brought the Irish economy down.
The truth is exactly the opposite. Liberalisation caused the Irish economy to surge until a return to big government crushed it. Membership of the eurozone, poor banking regulation and the government guarantee of…
View original post 34 more words
Policy bubbles alert: most innovation is not about R&D (and boffins in lab coats)
29 Oct 2014 Leave a comment
in applied price theory, applied welfare economics, economic growth, industrial organisation Tags: economic growth, innovation, R&D, The fatal conceit, The pretence to knowledge

The fire of truth: the relationship between inequality and economic prosperity in New Zealand since the 1970s
29 Oct 2014 Leave a comment
in economic growth, economics of regulation, income redistribution, politics - New Zealand, rentseeking Tags: Auckland urban limit, economic growth, Gini coefficient, green rent seeking, poverty and inequality, Resource Management Act
Figure 1: Before Housing Costs Gini coefficient, New Zealand, 1982 – 2013

closertogether.org.nz/nzs-income-inequality-problem claims that NZ income inequality increased very rapidly in the late 1980s and 1990s — faster than in any other wealthy country.
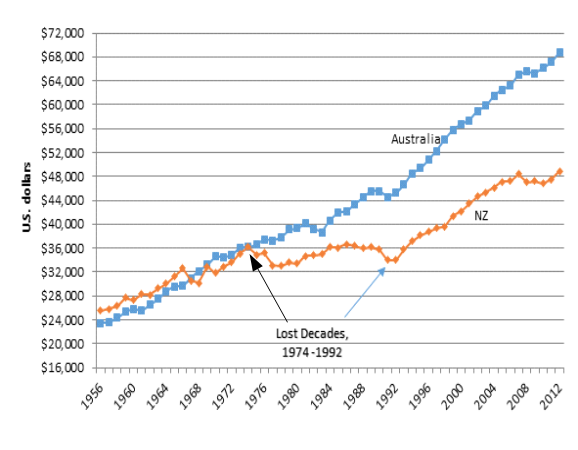
Figure 2 shows that this rapid rise in inequality coincided with the resumption of economic growth after two lost decades: next to no increase in real GDP per working age New Zealander from 1974 to 1992.
Figure 2: Real GDP per New Zealander and Australian aged 15-64, converted to 2013 price level with updated 2005 EKS purchasing power parities, 1956-2012
Source: Source: Computed from OECD Stat Extract and The Conference Board, Total Database, January 2014, http://www.conference-board.org/economics
Perry (2014) found that:
- Income inequality in New Zealand is at a similar level to Australia, Canada, Italy and Japan (Ginis of 32-33) and a little lower than the UK (34). Countries such as Denmark, Norway, Finland and Belgium have lower than average inequality (Ginis of 25-26). The US and Israel have higher scores of 39.
- The top 1% in New Zealand received around 8% of all taxable income in 2010 and 2011 (before tax), similar to Norway, Finland and Australia, lower than Ireland and Switzerland (11%) and much lower than the UK and Canada (13%) and the US (18%).
- The trend for the New Zealand share has been steady at around 8-9% since the mid 1990s, with perhaps a slight fall in the last few years. Many OECD countries saw small rises in the period, and in the USA the top 1% share continued to rise strongly, from 13% to 19%.
Perry (2014) concluded that:
Overall, there is no evidence of any sustained rise or fall in inequality in the last two decades. The level of household disposable income inequality in New Zealand is a little above the OECD median. The share of total income received by the top 1% of individuals is at the low end of the OECD rankings.
This remark by Parry that there is no evidence of any sustained rise or fall in inequality in New Zealand in the last 20 years is very much at odds with the claim of Closer Together New Zealand that income inequality inequality increased rapidly in the late 1980s and 1990s.
The increase in inequality in New Zealand was in the late 1980s and early 1990s. In the early 1990s, a long economic boom started that lasted until the global financial crisis.
Figure 3 : Income Inequality in New Zealand as Assessed by the Gini Coefficient

Source: Perry 2014 derived from Statistics NZ Household Economic Survey (HES) 1982–2012.
Figure 4: Income Inequality in New Zealand as Assessed by the P80/P20 Ratio

Source: Perry 2014 derived from Statistics NZ Household Economic Survey (HES) 1982–2012.
Figures 3 and 4 both show that after housing costs inequality in New Zealand is higher, but has been pretty stable for 20 years as measured by the Gini coefficient and by the P80/P20 ratio. (When individuals are ranked by equivalised household income and then divided into 100 equal groups, each group is called a percentile. If the ranking starts with the lowest income, then the income at the top of the 20th percentile is denoted P20; the income at the top of the 80th percentile is called P80. The ratio of the value at the top of the 80th percentile to the value at the top of the 20th percentile is called the P80/20 ratio and is often used as a measure of income inequality).
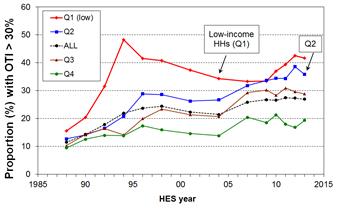
Figure 5: Proportion of HHs with housing cost outgoings to income of greater than 30%, by income quintile
Source: Perry (2014); OTI = outgoings to income
Figure 5 shows that
- for the bottom quintile (Q1), the proportion with high outgoings to income (OTI) steadily reduced from 48% in 1994 to 34% in 2004, as unemployment fell, employment and income rose, and income-related rental policies were introduced in 2000 for those in HNZC houses. From HES 2009 to HES 2013 the proportion rose strongly from 33% to 42%, the highest it has been in the last 25 years except for the peak of 48% in 1994.
- For households with incomes in the second quintile (Q2) there was a strong rise from the 1980s through to the mid 1990s, followed by a relatively flat trend to 2004. Since 2004, the proportion with high OTIs has risen strongly from 27% to 36%.
- For the third quintile (Q3) the proportion with high OTIs settled at around 30% for 2007 to 2013, up from 21% in 2004 and 10% in 1988.
Rising housing costs in New Zealand have one explanation, which is restrictions on the supply of land under the Resource Management Act.
HT: nzchildren.co.nz/income_inequality for figures 3 and 4.


Recent Comments