Was Karl Marx right? | Robert E. Lucas
21 Oct 2016 Leave a comment
in Marxist economics, Robert E. Lucas Tags: Karl Marx
Does inflation stimulate the economy? | Robert E. Lucas
19 Oct 2016 Leave a comment
in fiscal policy, macroeconomics, monetary economics, Robert E. Lucas Tags: fiscal stimulus
Current Trends in Economics – Robert E. Lucas Jr.
17 Oct 2016 Leave a comment
in applied price theory, development economics, economic growth, economic history, growth disasters, growth miracles, macroeconomics Tags: industrial revolution
Milton Friedman – Congressional House Economic Task Force (1993)
15 Oct 2016 Leave a comment
in economic history, fiscal policy, great depression, history of economic thought, macroeconomics, Milton Friedman, monetarism, monetary economics Tags: fiscal stimulus
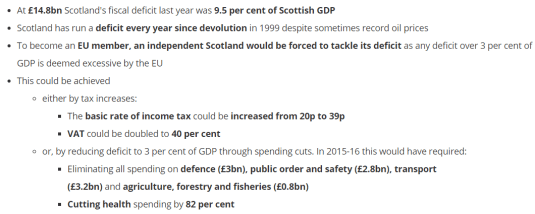
More reasons to expel Scotland from the United Kingdom
13 Oct 2016 Leave a comment
in constitutional political economy, fiscal policy
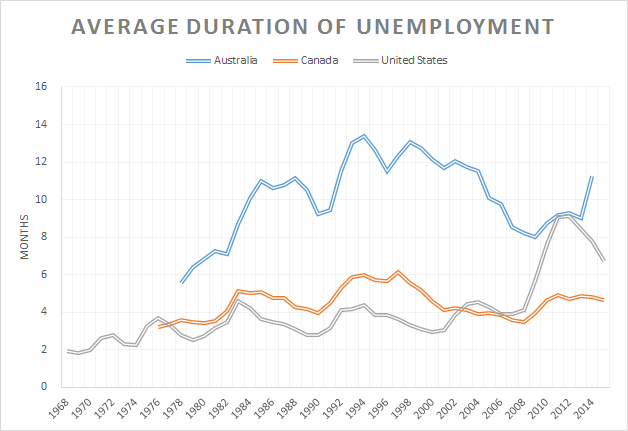
Average duration of US, Canadian and Australian unemployment since 1968
12 Oct 2016 Leave a comment
in business cycles, job search and matching, labour economics, macroeconomics, unemployment Tags: Australia, Canada, long-term unemployment, social insurance, unemployment duration
Robert Lucas on the voluntary and involuntary unemployment distinction
05 Oct 2016 Leave a comment
in job search and matching, labour economics, labour supply, macroeconomics, Robert E. Lucas, unemployment Tags: involuntary unemployment, job search, search and matching
Robert Lucas in a famous 1978 paper argued that all unemployment was voluntary because involuntary unemployment was a meaningless concept:
“The worker who loses a good job in prosperous time does not volunteer to be in this situation: he has suffered a capital loss. Similarly, the firm which loses an experienced employee in depressed times suffers an undesirable capital loss.
Nevertheless the unemployed worker at any time can always find some job at once, and a firm can always fill a vacancy instantaneously. That neither typically does so by choice is not difficult to understand given the quality of the jobs and the employees which are easiest to find.
Thus there is an involuntary element in all unemployment, in the sense that no one chooses bad luck over good; there is also a voluntary element in all unemployment, in the sense that however miserable one’s current work options, one can always choose to accept them.”
I agree that we all make choices subject to constraints. To say that a choice is involuntary because it is constrained by a scarcity of job-opportunities information is to say that choices are involuntary because there is scarcity. Alchian said there are always plenty of jobs because to suppose the contrary suggests that scarcity has been abolished.
Lucas elaborated further in 1987 in Models of Business Cycles:
A theory that does deal successfully with unemployment needs to address two quite distinct problems. One is the fact that job separations tend to take the form of unilateral decisions – a worker quits, or is laid off or fired – in which negotiations over wage rates play no explicit role.
The second is that workers who lose jobs, for whatever reason, typically pass through a period of unemployment instead of taking temporary work on the ‘spot’ labour market jobs that are readily available in any economy.
Of these, the second seems to me much the more important: it does not ‘explain’ why someone is unemployed to explain why he does not have a job with company X. After all, most employed people do not have jobs with company X either. To explain why people allocate time to a particular activity – like unemployment – we need to know why they prefer it to all other available activities: to say that I am allergic to strawberries does not ‘explain’ why I drink coffee.
Neither of these puzzles is easy to understand within a Walrasian framework, and it would be good to understand both of them better, but I suggest we begin by focusing on the second of the two.
Jeffrey Lacker on the inherent instability of the financial system
03 Oct 2016 Leave a comment
in economic history, global financial crisis (GFC)

Milton Friedman is said to have mesmerised several countries with a flying visit!?
30 Sep 2016 Leave a comment
in business cycles, economic growth, macroeconomics, Milton Friedman, monetarism, monetary economics, politics - Australia Tags: central banks, conspiracy theories, lags on monetary policy, monetary policy, rules versus discretion, The fatal conceit, The pretense to knowledge
Milton Friedman visited Australia in 1975. He spoke with government officials and appeared on the TV show Monday Conference. Apparently, that was enough for him to take over Australian monetary policy setting for the foreseeable future.
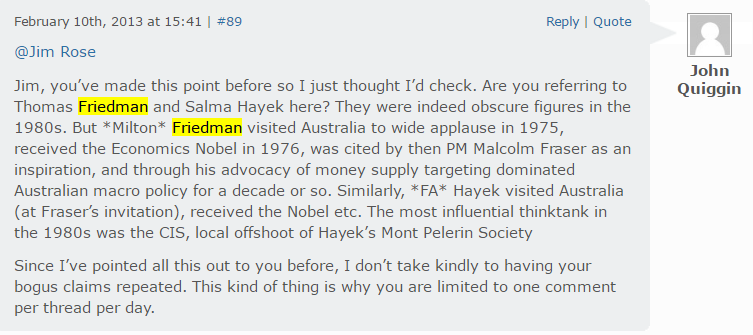
When working at the next desk to the monetary policy section in the late 1980s, I heard not a word of Friedman’s Svengali influence:
- The market determined interest rates, not the reserve bank was the mantra for several years. Joan Robinson would be proud that her 1975 visit was still holding the reins.
- Monetary policy was targeting the current account. Read Edwards’ bio of Keating and his extracts from very Keynesian treasury briefings to Keating signed by David Morgan that reminded me of macro101.
See Ed Nelson’s (2005) Monetary Policy Neglect and the Great Inflation in Canada, Australia, and New Zealand who used contemporary news reports from 1970 to the early 1990s to uncover what was and was not ruling monetary policy. For example:
“As late as 1990, the governor of the Reserve Bank rejected central-bank inflation targeting as infeasible in Australia, and cited the need for other tools such as wages policy (AFR, October 18, 1990).”
Bernie Fraser was still sufficiently deprogrammed in 1993 to say that “…I am rather wary of inflation targets.” Easy to then announce one in the same speech when inflation was already 2-3%.
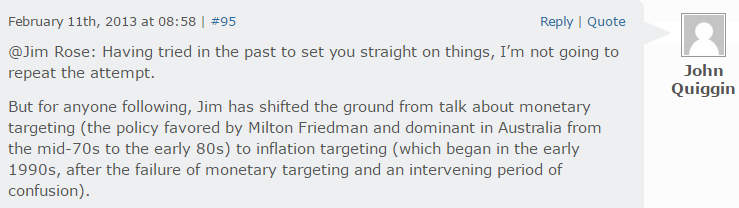
When as a commentator on a Treasury seminar paper in 1986, Peter Boxhall – fresh from the US and 1970s Chicago educated – suggested using monetary policy to reduce the inflation rate quickly to zero, David Morgan and Chris Higgins almost fell off their chairs. They had never heard of such radical ideas.
In their breathless protestations, neither were sufficiently in-tune with their Keynesian educations to remember the role of sticky wages or even the need for the monetary growth reductions to be gradual and, more importantly, credible as per Milton Freidman and as per Tom Sargent’s End of 4 big and two moderate inflations papers.
I was far too junior to point to this gap in their analytical memories about the role of sticky wages, and I was having far too much fun watching the intellectual cream of the Treasury senior management in full flight. At a much later meeting, another high flying deputy secretary was mystified as to why 18% mortgage rates were not reining in the current account in 1989.
Friedman’s Svengali influence did not extend to brainwashing in the monetarist creed that the lags on monetary policy were long and variable. The 1988 or 1989 budget papers put the lag on monetary policy at 1 year, which is short and rapier, if you ask me.
Graduate numbers quadruple! Zero economic growth premium?
29 Sep 2016 Leave a comment
in economic growth, economic history, economics of education, human capital, labour economics, macroeconomics Tags: education premium, endogenous growth theory, graduate premium
Some people get quite excited about the growth benefits and externalities from investing in more human capital such as more young people going to university. In New Zealand, the number of graduates quadrupled over the last 30 years but the trend GDP growth rate is unchanged. Please explain?
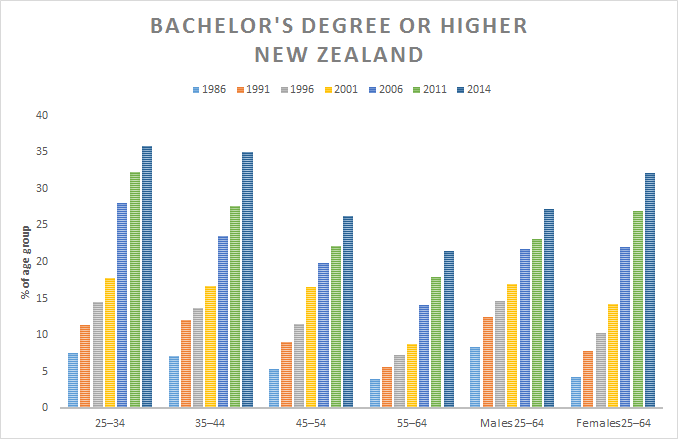
Source: Educational attainment of the adult population: The Social Report 2016 – Te pūrongo oranga tangata.
Wealth, Poverty, and Politics | Thomas Sowell on the Importance of human capital
28 Sep 2016 Leave a comment
in applied price theory, development economics, economic growth, economic history, economics of education, human capital, labour economics, macroeconomics Tags: Thomas Sowell
When did Canberra policy makers accept that inflation was a monetary phenomenon?
27 Sep 2016 3 Comments
in business cycles, economic history, macroeconomics, monetarism, monetary economics, politics - Australia Tags: central banks, monetary policy, The Great Inflation
Australian policymakers from at least 1971 viewed inflation as not a consequence of their monetary policy decisions. There were repeated references by them to wage-price spirals and both unsuccessful (1977) and successful attempts (1981) at wage freezes.
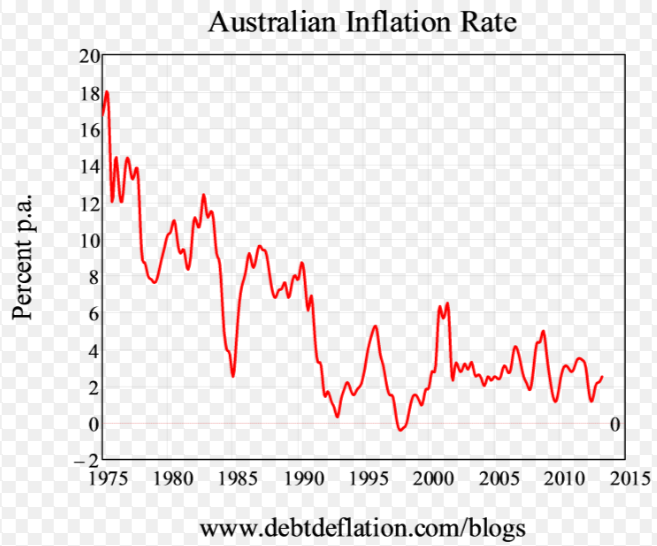
The prices and incomes accord from 1983 onwards was just another 1970s wage tax trade-off. An Incomes policy attributes inflation to non-monetary factors, as did Fraser and Lynch regularly.
• It was not until 1980 that the Fraser government’s monetary policy became genuinely anti-inflationary. With a lag, these changes halved inflation to the mid-single digits by 1983. The implementation lag on the 1975 Monday conference programme must have been long and variable and lasted for a three year window!? Three years out of 20 is hardly a monetarist hegemony!
• Australia had lower CPI inflation in the 1980s than the 1970s, but this was marred by rebounds in 1985–86 and 1988–90 to near 9%.
The monetary policy regime change in the late 1980s was triggered by factors besides rising inflation: a demonic view of currant account.
After several years of high interest rates, the budget papers forecasted a moderate slowing:
• The budget GDP forecast for 1990-91 was 2% with an actual of minus 0.4%; for inflation the actual and forecast were 5.3% versus 6.5%; 1989-90 inflation rate was 8% with GDP growth of 3.3%.
• In 1991-92, the budget GDP forecast was 1.5% with an actual of 2.1%; for inflation the actual and forecast were 1.9% versus 3.8%.
• In 1992-93, the budget papers forecast for inflation 3% for an actual of 1%.
• In 1993-94, the budget forecast for inflation 3.5% for an actual of 1.8%.
The monetarists in the Treasury, entranced as they were by Friedman’s 1975 visit, still had not clicked to the link between a tight monetary policy and low inflation as late as 1993. Australia pursued a stop-go monetary policy from 1971 to the early 1990s.
I worked in the next desk to the monetary policy section in the Prime Minister’s Department in the 1980s. They were determined that market set interest rates, not monetary policy.
I suggest you read the biography of keating by john edwards(?) – his economic advisor in the late 1980s.
Edwards quotes from numerous Treasury briefings to Keating. the Treasury remembered their Keynesian educations well, as did those at DPMC. the prices and incomes accord was very Keynesian: inflation as a non-monetary phenomenon
Mentioning Friedman’s name in the 1980s at job interviews would have been extremely career limiting. Not much better in the early 1990s. Back in the late 1980s, Friedman was graduating from ‘a wild man in the wings’ to just a suspicious character in policy circles.
If you name dropped Hayek in the 1980s and 1990s, any sign of name recognition would have indicated that you were been interviewed by people who were very widely read.
Did @AnnPettifor correctly predict the global financial crisis in 2003?
21 Sep 2016 1 Comment
in economic history, global financial crisis (GFC), macroeconomics, monetary economics
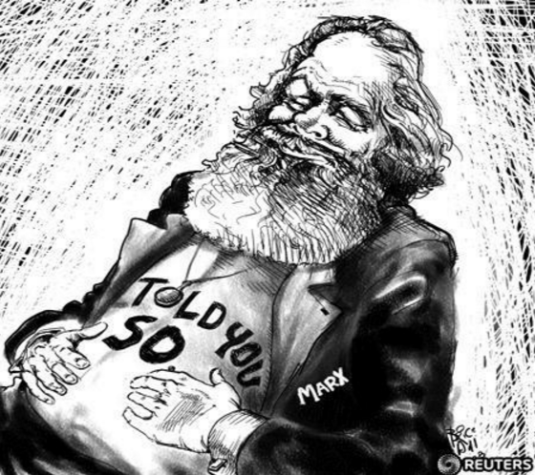
You are not much of a leftover Marxist if you are not predicting a crisis in capitalism is on the horizon.
https://twitter.com/PolicyObsAUT/status/778456702655995904
Capitalism is supposed to collapse under its own inner contradictions.

Professional stock market tipsters are notorious from specialising in predicting doom as well and they still get listened too despite terrible forecasting records.
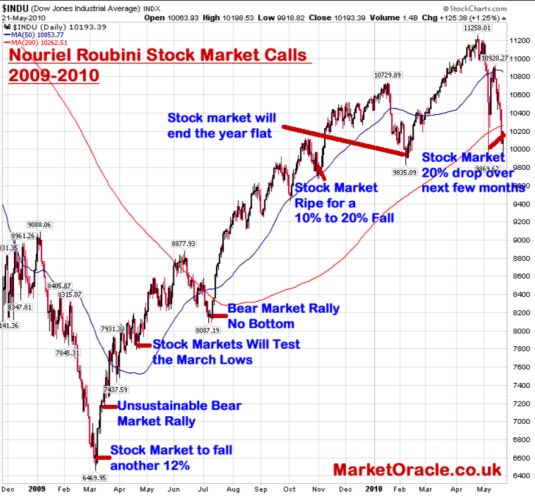
Plenty of people warned of dark days ahead in the lead up to the global financial crisis. An essay anyone can read with profit is Ross Levine’s An Autopsy of the U.S. Financial System: Accident, Suicide, or Negligent Homicide? His abstract says
The evidence is inconsistent with the view that the collapse of the financial system was caused only by the popping of the housing bubble (“accident”) and the herding behavior of financiers rushing to create and market increasingly complex and questionable financial products (“suicide”).
Rather, the evidence indicates that senior policymakers repeatedly designed, implemented, and maintained policies that destabilized the global financial system in the decade before the crisis. Moreover, although the major regulatory agencies were aware of the growing fragility of the financial system due to their policies, they chose not to modify those policies, suggesting that “negligent homicide” contributed to the financial system’s collapse.
The New York Times warned in 1999 that Fannie Mae was taking on so much risk that an economic downturn could trigger a “rescue similar to that of the savings and loan industry in the 1980s,” and emphasised this point again in 2003. Greenspan testified before a Senate committee in 2004 that the increasingly large and risky Fannie Mae and Freddie Mac portfolios could have enormously adverse ramifications.
You predict a financial crisis by pointing to adjustments in your share portfolio to take advantage of shorting the market and then showing how big a profit you made afterwards.
The movie The Big Short highlights that its protagonists had skin in the game. They were investing in mortgages or shorting the same in the expectation of the crash they were predicting. Much of the drama in the film is about how long their foretelling of a crash took to come true.
There were no windbags and armchair critics in The Big Short talking gloom and doom on the horizon without investing their own money to profit from their forecasts.


Recent Comments