06 Jul 2015
by Jim Rose
in applied price theory, applied welfare economics, budget deficits, business cycles, comparative institutional analysis, constitutional political economy, currency unions, economic growth, economic history, Euro crisis, fiscal policy, fisheries economics, global financial crisis (GFC), international economics, macroeconomics, Public Choice, rentseeking
Tags: Euro sclerosis, Greece, insurance attacks, sovereign defaults, speculative attacks
The roots of Greece’s crisis are simple. Before Greece joined the Eurozone, investors treated it as a middle-income country with poor governance — which is to say, a credit risk.
After Greece joined the Eurozone, investors thought that Greece was no longer a credit risk — they figured, if push came to shove, other Eurozone members like Germany would bail Greece out. They were wrong.

Michael Dooley put forward a theory of speculative attacks on currencies as insurance attacks on currencies for emerging markets after the East Asian financial crisis:
First generation models of speculative attacks show that apparently random speculative attacks on policy regimes can be fully consistent with rational and well-informed speculative behaviour.
Unfortunately, models driven by a conflict between exchange rate policy and other macroeconomic objectives do not seem consistent with important empirical regularities surrounding recent crises in emerging markets. This has generated considerable interest in models that associate crises with self-fulfilling shifts in private expectations.
In this paper we develop a first generation model based on an alternative policy conflict. Credit constrained governments accumulate reserve assets in order to self-insure against shocks to national consumption. Governments also insure poorly regulated domestic financial markets.
Given this policy regime, a variety of internal and external shocks generate capital inflows to emerging markets followed by successful and anticipated speculative attacks.
We argue that a common external shock generated capital inflows to emerging markets in Asia and Latin America after 1989. Country specific factors determined the timing of speculative attacks. Lending policies of industrial country governments and international organizations account for contagion, that is, a bunching of attacks over time.
His model was not within the context of a currency union but his basic theory is correct.
There are speculative attacks on a currency or a bank run after foreign markets revises their estimates of the available central bank reserves and international lines of credit to bail out the banking systems and/or foreign debt.
Michael Dooley was dealing with the emerging economies of Southeast Asia and their official lines of credit that insure their foreign exchange liabilities and domestic banking system. Greece is about lines of credit for similar purposes to other European union member states.
via 12 charts and maps that explain the Greek crisis – Vox and The Most Important Graphs of 2011 – The Atlantic.
06 Jul 2015
by Jim Rose
in budget deficits, business cycles, currency unions, economic growth, Euro crisis, financial economics, fiscal policy, global financial crisis (GFC), macroeconomics
Tags: bank runs, banking panics, Eurosclerosis, Germany, Greece, sovereign defaults
Greece is a tiny part of the European economies so it doesn’t matter that much to the rest of the European Union what happens to Greece. The only people will notice the sovereign default of Greece once the breathless journalism has died down are Greeks themselves as they rebuild their banking and monetary system against a background of a government run by coffee shop Marxists.

06 Jul 2015
by Jim Rose
in budget deficits, business cycles, currency unions, economic growth, Euro crisis, fiscal policy, labour economics, labour supply, macroeconomics, unemployment
Tags: Eurosclerosis, Greece
13 Jun 2015
by Jim Rose
in budget deficits, currency unions, economic growth, Euro crisis, fiscal policy, labour economics, labour supply, macroeconomics
Tags: ageing society, early retirement, Eurosclerosis, Greece, labour force participation, old age pensions, older workers, social insurance, taxation and the labour supply, welfare state
A country that spends nearly a fifth of its GDP on old-age pensions with surprisingly few people over the age of 55 working should not be surprised when it finds itself in financial difficulty.
19 Mar 2015
by Jim Rose
in budget deficits, business cycles, economic growth, fiscal policy, inflation targeting, macroeconomics, Milton Friedman, monetarism, monetary economics
Tags: fiscal policy, monetary policy, Paul Samuelson, rules versus discretion, stabilisation policy
25 Feb 2015
by Jim Rose
in budget deficits, business cycles, economic growth, F.A. Hayek, fiscal policy, global financial crisis (GFC), great recession, macroeconomics, monetary economics
Tags: Austrian real business cycle theory, Edmund Phelps, FA Hayek, Keynes in macroeconomic policy
31 Jan 2015
by Jim Rose
in budget deficits, business cycles, economic growth, Euro crisis, great depression, great recession, macroeconomics, monetary economics, politics - Australia, politics - New Zealand, politics - USA
Tags: deflation, fiscal policy, liquidity traps, monetary policy, stabilisation policy
Deflation has a bad reputation. People blame deflation for causing the great depression in the 1930s. What worse reputation can you get as a self-respecting macroeconomic phenomena?
The inconvenient truth for this urban legend is empirical evidence of deflation leading to a depression is rather weak.
The most obvious is confounding evidence, is up until the great depression, deflation was commonplace. In the late 19th century, deflation coincided with strong growth, growth so strong that it was called the Industrial Revolution.
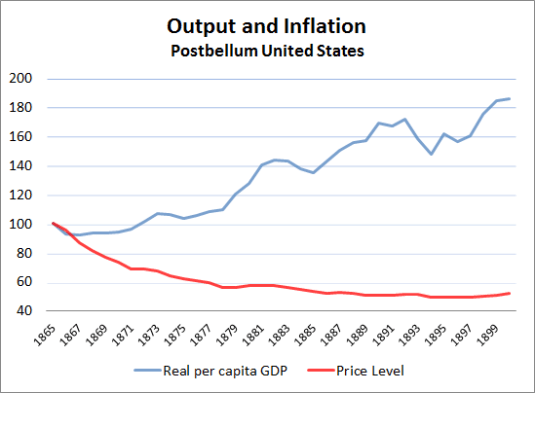
For deflation to be a depressing force, something must have happened in the lead up to the Great Depression to change the impact of deflation on economic growth.
Atkeson and Kehoe in the AER looked into the relationship between deflation and depressions and came up empty-handed.
Deflation and depression do seem to have been linked during the 1930s. But in the rest of the data for 17 countries and more than 100 years, there is virtually no evidence of such a link.
 Analyse Economique
Deflation and Depression: Is There an Empirical Link?
Andrew Atkeson, and Patrick J. Kehoe, 2004.
Are deflation and depression empirically linked? No, concludes a broad historical study of inflation and real output growth rates. Deflation and depression do seem to have been linked during the 1930s. But in the rest of the data for 17 countries and more than 100 years, there is virtually no evidence of such a link.
View original post 1,842 more words
27 Jan 2015
by Jim Rose
in budget deficits, currency unions, development economics, economic growth, economic history, Euro crisis, fiscal policy, global financial crisis (GFC), growth disasters, law and economics, macroeconomics, poverty and inequality
Tags: currency unions, Euroland, Greece, optimal currency area, sovereign default
17 Dec 2014
by Jim Rose
in budget deficits, business cycles, economic growth, fiscal policy, global financial crisis (GFC), great depression, great recession, macroeconomics, monetarism, monetary economics
Tags: bank runs, GFC, great depression, great recession, Robert E. Lucas
Previous Older Entries Next Newer Entries


Recent Comments