Forget avoidance outrage: public’s real attitude to tax is revealed by their actions @JordNZ
21 Apr 2016 Leave a comment
in applied price theory, constitutional political economy, economic history, economics of media and culture, politics - Australia, politics - New Zealand, politics - USA, Public Choice, public economics Tags: British economy, British politics, expressive voting, growth of government, rational irrationality, revealed preference, size of government, voter demographics
McDonald’s Workers Just Lovin’ Their #ZeroHoursContracts @suemoroney @IainLG @FairnessNZ
19 Apr 2016 Leave a comment
in labour economics, labour supply, managerial economics, market efficiency, organisational economics, personnel economics, politics - New Zealand Tags: British economy, British politics, employment law, employment regulation, fixed costs of working, part-time work, The fatal conceit, The pretense to knowledge, zero hours contracts
Revealed preference rules. Not only do about half of unemployed turned down offers of zero hour contract jobs, those that switch from a zero hours contract to minimum hours are not much different from the number of people in these type of jobs who would be quitting to another job anyway.
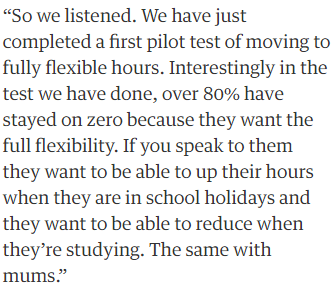
Source: McDonald’s Workers Are Just Lovin’ Their Zero Hours Contracts – Forbes and McDonald’s offer staff the chance to get off zero-hours contracts | UK news | The Guardian.
#Morganfoundation discovers that #Ukraine is a dodgy place to buy credence goods
19 Apr 2016 Leave a comment
in economics of climate change, economics of crime, economics of information, environmental economics, global warming, industrial organisation, international economic law, international economics, International law, law and economics, politics - New Zealand, survivor principle Tags: adverse selection, asymmetric information, carbon trading, climate alarmism, climate alarmists, credence goods, experience goods, inspection goods
Morgan Foundation yesterday put out a report pointing out that many of the carbon credits purchased from the Ukraine under the carbon trading scheme are fraudulent.
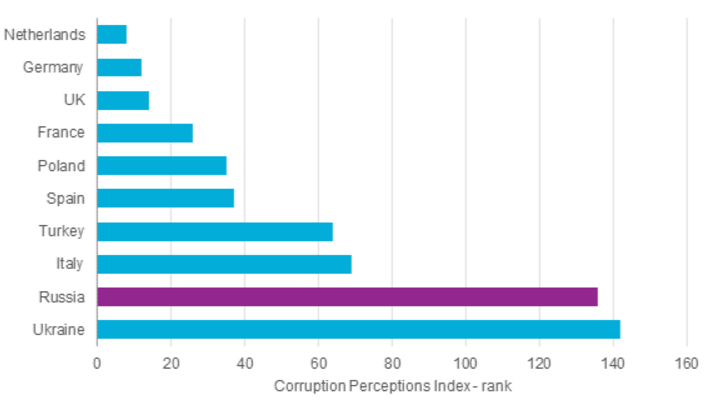
That comes with no surprise to anyone vaguely familiar with business conditions and the level of official corruption in the former Soviet Union. Russia is a more honest place to do business.
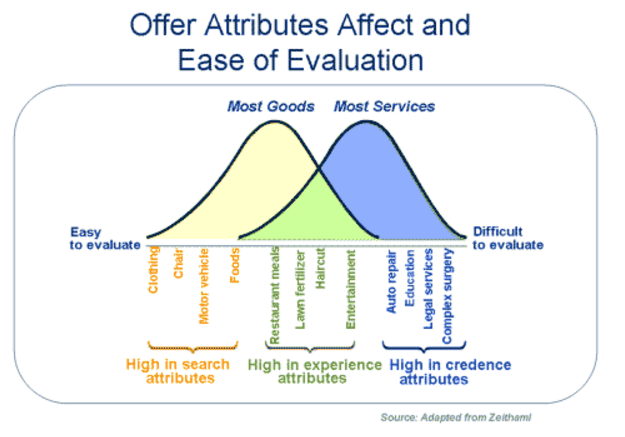
Carbon traders who buy from the Ukraine are not buying an inspection good. An inspection good is a good whose quality you can ascertain before purchase.

They are not buying an experience good. An experience good is a good whose quality is ascertained after purchase in the course of consumption.

Source: Russia, Ukraine dodgy carbon offsets cost the climate – study | Climate Home – climate change news.
What these carbon traders in New Zealand are doing is buying credence goods from the Ukraine. The credence goods are the carbon credits, which the Morgan Foundation and others have found often to be fraudulent.
A credence good is a good whose value is difficult or impossible for the consumer to ascertain. A classic example of a credence good is motor vehicle repairs.
You must trust the seller and their advice as to how much you need to buy of a credence good. Many forms of medical treatment also require you to trust the seller as to how much you need.
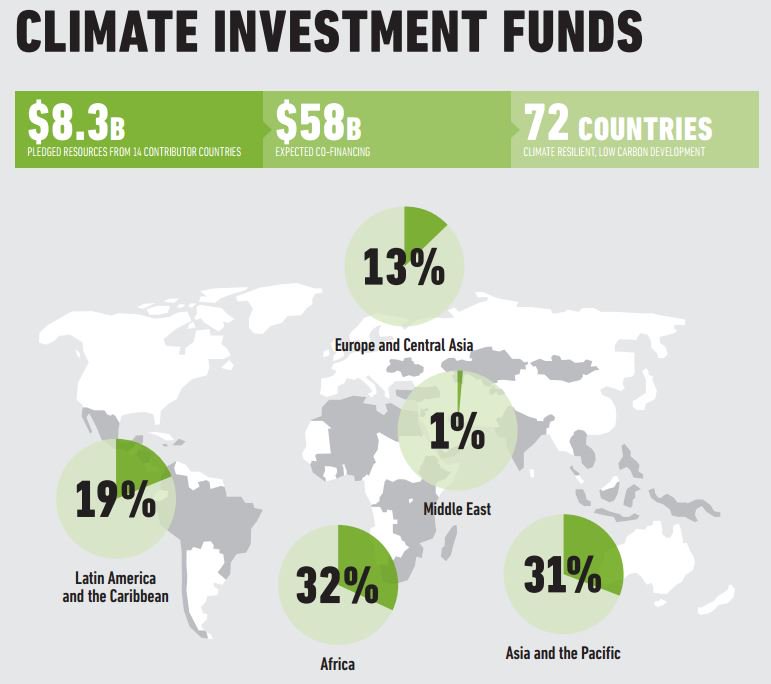
Carbon credits are such a credence good. You know there is corruption in the Ukraine and many other countries that supply them. You may never know at any reasonable cost whether the specific carbon credits you buy were legitimate.
The reason why carbon credits are purchased from such an unreliable source is expressive voting. As is common with expressive politics, what matters is whether the voters cheer or boo the policy. The fact whether it works or not does not matter too much.
The Greens are upset about this corruption in carbon trading. They did not mention the corruption in international carbon trading and climate aid when they welcomed the recent Paris treaty on global warming but that is for another day.
https://twitter.com/kadhimshubber/status/721831502372302849
Co-ordinated international action on global warming is rather pointless if some of the key countries with carbon emission caps are corrupt, which they are.
As Geoff Brennan has argued, CO2 reduction actions will be limited to modest unilateral reductions of a largely token character. There are many expressive voting concerns that politicians must balance to stay in office and the environment is but one of these.

Once climate change policies start to actually become costly to swinging voters, expressive voting support for these policies will fall away, and it has.
Networked Carbon Markets

Source: World Bank Networked Carbon Markets.
One way to stem that fading support is to buy carbon credits on the cheap and there is plenty of disreputable suppliers of cheap carbon credits. Buying dodgy carbon credits as a way of doing something on global warming without it costing more than expressive voters will pay.
One of the predictions of the adverse selection literature is that if consumers cannot differentiate good and bad goods from each other, such as with used cars, the market will contract sharply or even collapse because buyers cannot trust what is on offer. This risk of adverse selection undermining a market applies with clarity to carbon trading.

Source: How Can Your Vote Shape a Low Carbon Future? It Starts with Carbon Pricing.
@garethmorgannz is getting a little techie about debating optimal tax theory
17 Apr 2016 1 Comment
in politics - New Zealand, public economics Tags: optimal tax theory, taxation and entrepreneurship, taxation and investment, taxation and labour supply, taxation of capital
All I said was “optimal tax theory including that pioneered by Stiglitz and Merrlees, economists of impeccable left-wing credentials, show that taxes on the income from capital should be low because the deadweight social costs of taxes on capital are very high”.
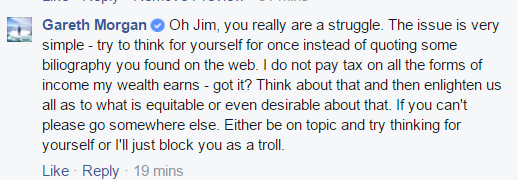
@garethmorgannz gives optimal tax theory a pass once again @JordNZ
17 Apr 2016 Leave a comment
in applied price theory, entrepreneurship, fiscal policy, macroeconomics, politics - New Zealand, public economics Tags: company tax, Gareth Morgan, rational irrationality, taxation and entrepreneurship, taxation and investment, taxation and labour supply, taxation of capital income
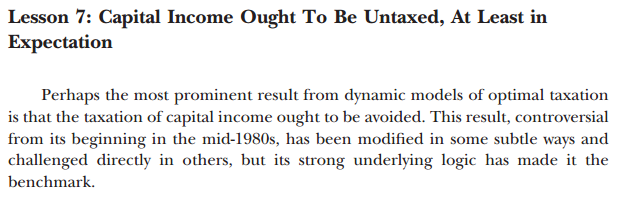
The Morgan Foundation gave optimal tax theory a pass in yesterday’s publication about taxes on land and capital. Gareth Morgan is keen on a comprehensive capital tax.
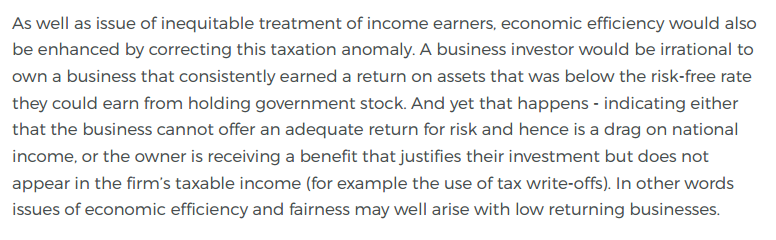
Source: Taxing Wealth & Property – What Works? A Morgan Foundation Report.
This failure to refer to optimal tax theory is despite the Foundation’s strong commitment to evidence-based policy. Any discussion of tax policy that is evidence-based must refer optimal tax theory.
Source: Morgan Foundation, Public Policy Education.
<p>
Picking winners and @stevenljoyce’s repayable grants to 11 more tech start-ups @JordNZ
13 Apr 2016 Leave a comment
in applied price theory, entrepreneurship, industrial organisation, politics - New Zealand, Public Choice, rentseeking, survivor principle Tags: corporate welfare, creative destruction, entrepreneurial alertness, Hollywood economics, industry policy, picking losers, picking winners
 Minister for Science and Innovation Steven Joyce picked a few more winners today. Eleven more start-up technology companies are to be funded $450,000 each in repayable loans to commercialise their technology. The loans are from Callaghan Innovation’s incubator network.
To cut a long diatribe short, I find these sums of money rather piddling. I have encountered this corporate welfare program before at a presentation.
My reaction then as is now: by handing out such small grants, some will succeed, some will fail. Importantly, there will never be one big disaster to bring the whole show down. There is political safety in diversification.

This is not the case with, for example, film subsidies. If Sir Peter Jackson and others finally produce a box office bomb, it will be all too glaring that the taxpayers backed a Hollywood loser with hundreds of millions of dollars. $500 million in subsidies in the case of Avatar.

By peppering small sums of money across the economy, there is no similar risk from this repayable grant scheme for the commercialisation of products.

@FairnessNZ NZ leads world in closing the gender pay gap #equalpayday @greencatherine
13 Apr 2016 Leave a comment
in discrimination, economic history, gender, human capital, labour economics, labour supply, politics - Australia, politics - New Zealand, politics - USA, poverty and inequality Tags: Australia, British economy, gender wage gap

4 Lessons for Morgan Foundation on How to Sell the #UBI @JordNZ
13 Apr 2016 Leave a comment
in applied welfare economics, labour economics, labour supply, politics - New Zealand, welfare reform Tags: expressive voting, rational irrationality, universal basic income

Source: Morgan Foundation (12 April 2016) Four Lessons for Labour on How to Sell the UBI.
I will contract out to Geoff Simmons of the Morgan Foundation my reply to the claim yesterday by the Morgan Foundation’s Susan Guthrie that there are no negatives from a Universal Basic income. Simmons said:
With an unconditional basic income, most beneficiaries would be no better off than they are now (in fact sole parents would almost certainly receive a lower benefit).
Single parents are $150 a week worse off and retirees are $50 worse off per week if their current income support were replaced by a Universal Basic Income of $11,000 per adult.
Both were entitled to much more under the current welfare benefit system and New Zealand Superannuation respectively. Unemployment, sickness and invalid beneficiaries are about 5% better off under a Universal Basic Income.
Labour’s background paper described a Universal Basic Income of $11,000 as not enough. Guthrie is even franker yesterday about how inadequate a Universal Basic Income is for the poor:
A basic income policy would provide everyone aged 18 and over with an unconditional, tax free survival-level of income each and every year.
I will contract out to Gareth Morgan (2011) why a Universal Basic Income that provides a “survival-level of income” is not good enough:
Rather than decreeing a minimum wage and discovering the consequences for jobs and top-up payments, let’s agree on what is a minimum income every adult should have in order to live a dignified life and then see what flows from that.
We begin by specifying the income level below which we are not prepared to see anyone having to live.
A survival-level of income and a minimum income on which every adult can live a dignified life are not the same thing.
Gareth Morgan’s universal basic income of $11,000 for adults makes most better off except those for whom the modern welfare state was established to protect.
Most of the evidence against the Universal Basic Income comes from examining the numbers put forward by its proponents such as the Morgan Foundation and its excellent online tool. Brian Easton (2015) put it well when he said:
Many advocates put the UMI forward without doing the sums.
Those who do, find that the required tax rates are horrendous or the minimum income is so low that it is not a viable means of eliminating poverty. Among the latter are New Zealanders Douglas, Gareth Morgan and Keith Rankin.
How to tell if you are a modern progressive – a two-part test by Scott Sumner
13 Apr 2016 Leave a comment
in international economics, labour economics, minimum wage, politics - New Zealand, politics - USA Tags: antiforeign bias, antimarket bias, expressive voting, Leftover Left, living wage, makework bias, rational irrationality

What undergrads and @stevenljoyce need to know about trade @GreenCatherine
12 Apr 2016 Leave a comment
in applied price theory, applied welfare economics, development economics, international economics, job search and matching, labour economics, labour supply, macroeconomics, politics - New Zealand Tags: antiforeign bias, free trade, makework bias, Paul Krugman, protectionism, tariffs, trade policy
Minister for everything Stephen Joyce wrote some nonsense in the paper today about how trade agreements and more exports will mean more jobs:
I would like to make the point that trade access is hugely important for a small country like New Zealand.
Without fair and equal trade access we can’t sell as much of our goods and we get less for them. And that means fewer jobs.
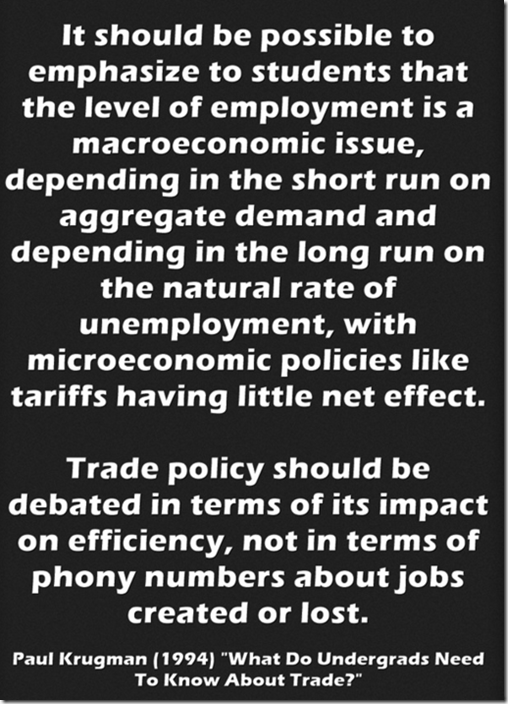
This make-work bias is as bad as those who oppose trade agreements on the grounds of an anti-foreign bias. Trade affects the composition of employment, not the number of jobs. Paul Krugman spent a good part of the 1990s trying to explain that to the general public and public intellectuals.
1992 Camille Paglia trashes Gloria Steinem wing of feminism
10 Apr 2016 Leave a comment
in discrimination, economics of love and marriage, economics of media and culture, gender, labour economics, law and economics, politics - Australia, politics - New Zealand, politics - USA, television Tags: feminism
Is Kiwibank profitable enough to take on the big banks?
09 Apr 2016 Leave a comment
in applied price theory, economic history, entrepreneurship, financial economics, George Stigler, industrial organisation, law and economics, politics - New Zealand, survivor principle Tags: anti-trust economics, antimarket bias, competition law, economics of banking, New Zealand Greens
if Kiwibank is part of the competitive fringe of an oligopoly made up of the 4 Australian banks, it is not very profitable for a competitive fringe of a cartel as the chart below shows. The other New Zealand owned small banks in that competitive fringe are not that profitable at all. Undercutting an oligopoly and its high prices and above-average cost and above marginal cost pricing is not what it used to be for the competitive fringe in New Zealand banking, if there ever was a cartel.

Source: G1 Summary information for locally incorporated banks – Reserve Bank of New Zealand.
Bank customers can choose between four major banks and a competitive fringe. If those major banks are indeed overcharging because of price-fixing by a cartel or an oligopoly, that competitive fringe which includes Kiwibank has a real opportunity to expand profitably and with little risk.
The prospect of expansion by the competitive fringe that includes Kiwibank only increases the incentives on each of the four big banks to cheat on the cartel price. The first bank to cheat on the cartel will profit the most; the other banks who are colluding know this. As George Stigler concluded in his 1964 paper “The Theory of Oligopoly” as Peltzman and Carlton explain:
…once a price is somehow agreed upon, there will be incentives for individual rivals to cheat on the [collusive] agreement. Whether cheating occurs depends on weighing the profits from not cheating against the profits from cheating and then being detected and having competition break out…
any agreement among sellers cannot ignore the incentives to cheat provided by lags in detection. So understanding when a price elevated above the competitive level can be an equilibrium requires an analysis of the dynamic consequences of cheating versus not cheating…
Collusion over retail banking services and prices faces major hurdles that will lead to most attempts at price-fixing having a short life. These barriers to successful collusion include:
- numerous competitors,
- expansion by the smaller banks were not part of the cartel or cheat on the cartel
- the entry and expansion of new banks,
- the lack of a standard product, and
- a rapidly changing business environment.
Implicit understandings among the colluding banks may break down owing to conflicts over the most suitable price, the complexities of co-ordinating pricing across a diverse range of banking products, or the simple presence of a maverick bank.
As time passes, destabilising pressures within a banking cartel or oligopoly will build due to long-run substitution and the threat or actuality of entry by new banks and expansion by banks In the competitive fringe, which includes Kiwibank.
The first firm in any market may charge a high price relative to costs, but the entry of one or two more firms usually results in effective competition. Once there are three to five suppliers in a market, an additional entrant has little impact on prices because pricing is already as competitive as it can be.
When ANZ sought to acquire the National Bank of New Zealand in 2003, the Commerce Commission did not oppose this merger. The Commission did not consider that a substantial lessening of competition would follow this merger. The Commission said:
…the merger is unlikely to increase the likelihood of co-ordinated market power in the supply of transaction accounts because the fringe players are likely to provide some competition, the banks have different strengths and weaknesses and in particular ASB is unlikely to have the incentive to participate in co-ordinated power at the expense of its recent growth and customer satisfaction levels.
This analysis of co-ordinated market power applies to each of the relevant markets. Therefore the Commission concludes that the merger is unlikely to result in a substantial lessening of competition in the supply of transaction accounts.
In the supply of mortgages, savings accounts and credit cards the merger is unlikely to lead to a substantial lessening of competition, as in each of these markets, ASB, Westpac and BNZ are likely to provide sufficient competition to the combined entity.
An important driver of a competition in the mortgage market in 2003 was a high incidence of fixed-rate mortgages and the tendency of these fixed rate mortgagees to reconsider all their options at the end of each fixed rate term.
The Commission Commission noted that there was a large re-mortgaging market in New Zealand. Banks offer to do all the work for customers wishing to switch over bank accounts and direct debit arrangements.
In a very atypical move for a purported cartel, in 2010 the bank owned Payments New Zealand agreed to change over direct debits over automatically when a customer switched banks, which made switching banks even more easier.
At the time of the ANZ and National Bank merger, the Commerce Commission noted that Kiwibank was offering lower rates on its mortgages as a way of gaining a foothold in the market.
The Commerce Commission could not have been more right about the vigour in competition in retail banking with regard to re-mortgaging and switching between fixed and floating mortgages in New Zealand.
As the chart below of fixed and floating mortgage shares a New Zealand bank balance sheets shows, there is a rapid exodus from fixed rate mortgages at the time of the Global Financial Crisis.

Source: S8 Banks: Mortgage lending ($m) – Reserve Bank of New Zealand.
I cannot see how any cartel or oligopoly could sustain price-fixing against such dynamic changes in market shares and product switching.
Cartels are is much more difficult to agree when there are many products about which to fix prices and market shares. At a minimum, this rapid movement of customers between mortgage products will sow suspicions that one or more rival banks is stealing customers thereby cheating on the cartel agreement. Not surprisingly, the history of cartels is a history of double-crossing. Banking is no exception.
@GarethMP @jamespeshaw need message discipline on @NZGreens as honest brokers
08 Apr 2016 Leave a comment
in economics of media and culture, industrial organisation, politics - New Zealand, survivor principle Tags: anti-trust economics, cartel theory, competition law, conspiracy theories, economics of banking, New Zealand Greens, privatisation, state owned enterprises
Yesterday morning, Green MP Gareth Hughes posted a British Greens’ video about how other politicians are a bunch of squabbling children but the Greens are above that. It’s only the Greens who offer a “true alternative to the establishment parties” and their “same childish Punch & Judy politics”.
Later that same day Greens co-leader James Shaw posted a video that shaded the truth about the history of dividends from Kiwibank as a way of scoring points of the National Party led government.
Shaw claimed that the government is extracting more and more dividends from Kiwibank rather than letting it keep those profits as capital on which the government owned bank can be a more aggressive competitor.
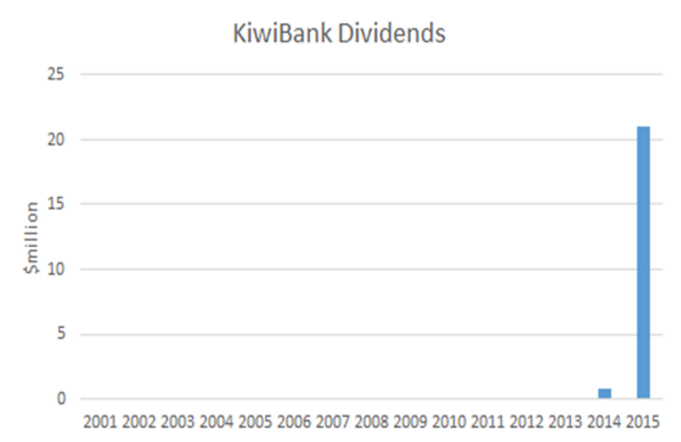
Source: Kiwibank pays its first dividend of $21 million to Government | Stuff.co.nz.
Shaw is vaguely correct in that it is dividends plural when referring to Kiwibank’s dividends. Kiwibank paid dividends of $21 million last year; and $750,000 the year before. Kiwibank has paid two dividends to New Zealand Post in its entire history since 2002.
It shades the truth to say that the government is extracting more and more dividends from Kiwibank when when it has only paid one dividend worth mentioning, which was last year.
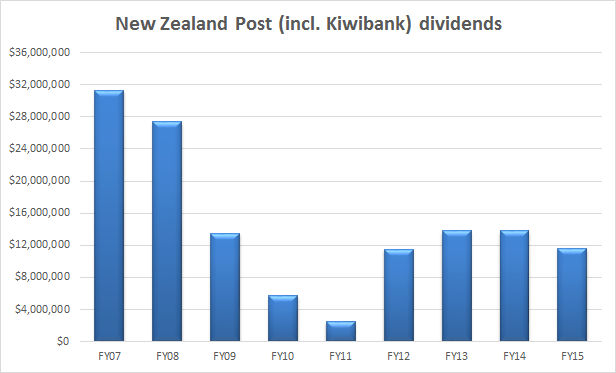
Source: New Zealand Treasury – data released under the Official Information Act.
As for James Shaw’s claim that the entry of Kiwibank made banking in New Zealand much more competitive, Michael Reddell disposed of that by linking to a 2013 Treasury assessment of competition in retail banking.
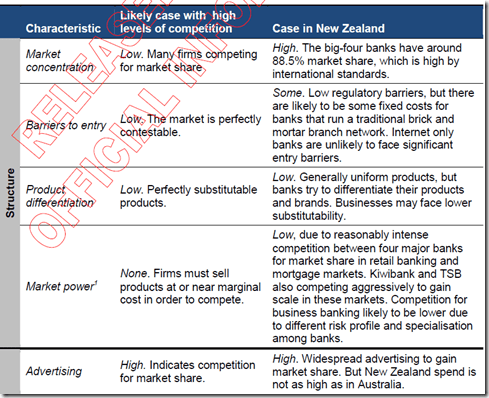
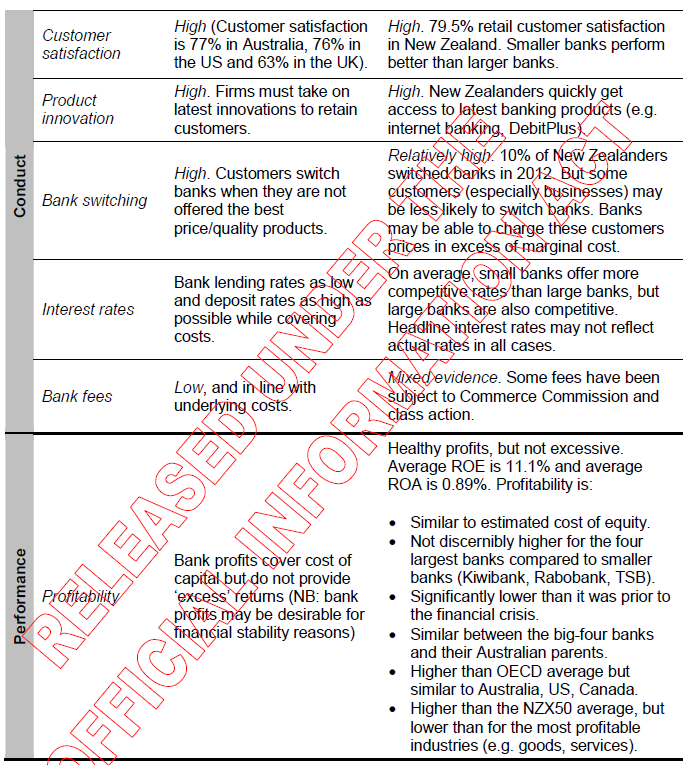
Source: New Zealand Treasury Official Information Act Releases.
There are no excess profits in the New Zealand banking market for Kiwibank to undercut. Entry barriers are low, banking products are easy substitutes for each other between the competing banks, and the banks compete for market share by advertising of, for example, special packages to switch banks.

Adding to the analysis of the Treasury, Posner and Easterbrook suggest that these industry behaviours together are suspicious.
- Fixed relative market shares among top firms over time.
- Declining absolute market shares of the industry leaders.
- Persistent price discrimination.
- Certain types of exchanges of price information.
- Regional price variations.
- Identical sealed bids for tenders.
- Price, output, and capacity changes at the time of the suspected initiation of collusion.
- Industry-wide resale price maintenance or non-price vertical restraints.
- Relatively infrequent price changes; smaller price reactions as a result of known cost changes.
- Demand is highly responsive to price changes at market price.
- Level and pattern of profits relatively favourable to smaller firms.
- Particular pricing and marketing strategies.
As the Treasury noted in its analysis, there are several small banks offering competitive rates that would allow them to expand if they offered value for money over the existing offerings. Returns on equity of the big banks are not discernibly higher than for the smaller ones.
To add again to the Treasury analysis, it is not easy to organize a cartel. There are markets to divide, prices to set, and production quotas to assign. The best place to be in a cartel is outside of it undercutting the higher price and selling as much as you can before the cartel inevitably collapses. Brozen and Posner suggest the following pre-conditions to collusion:
- market concentration on the supply side;
- no fringe of small sellers;
- high transport costs from neighbouring markets;
- small variations in production costs between firms;
- readily available information on prices;
- inelastic demand at the competitive price;
- low pre-collusion industry profits;
- long lags on new entry;
- many buyers (otherwise selective discounting to big buyers will be too tempting while monitoring adherence to the agreement will be difficult);
- no significant product differentiation;
- large suppliers selling at the same level in the distribution chain;
- a simple price, credit and distribution structure;
- price competition is more important than other forms of competition;
- demand is static or declining over time; and
- stagnant technological innovation and product redesign.
Stable collusive arrangements are thus likely to be rare because the absence of any of the above conditions will tend to undermine the potential for successful collusion.
Successful cartel operation is even harder than its initial formation. Members of the cartel must continue to believe that they enjoy net profits from participating in the collusion.
The more profitable the collusive price fixing, the greater the incentive for outsiders to seek entry to compete. In cartel theory, these new entrants are known as interlopers.
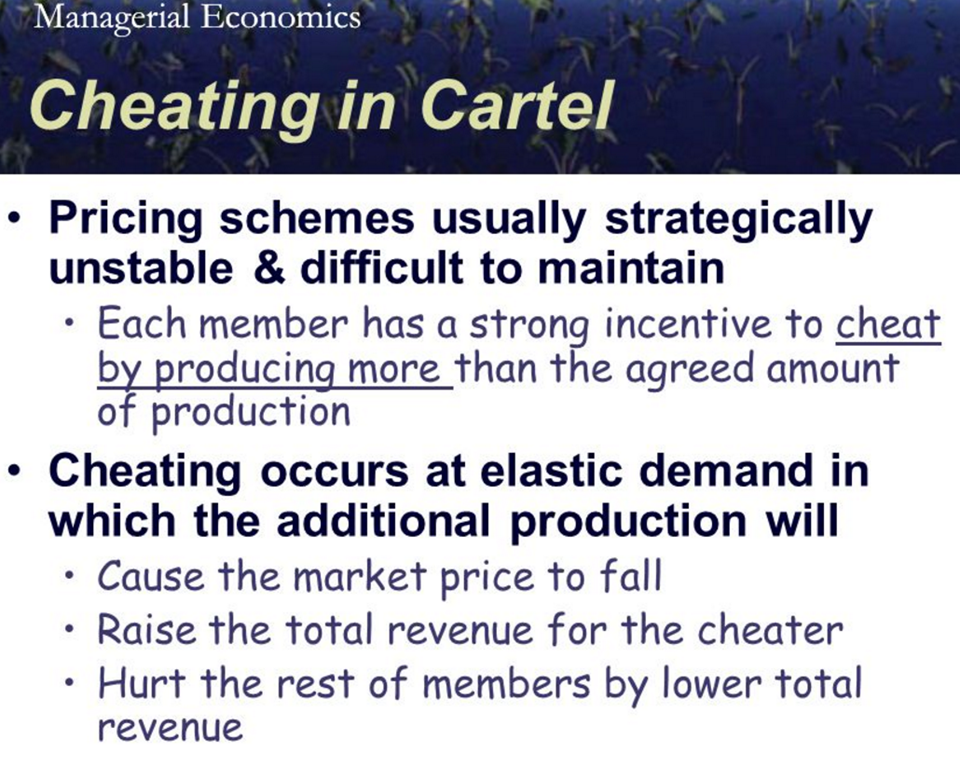
The more numerous the participants in the cartel and the more lucrative the collusion, the greater the temptation for individual members to cheat and the greater the fear of each that some other member will cheat first.
Cartel members that cheat early profit the most from the cartel price before it collapses. That is why the history of cartels is a history of double-crossing. Long-term survival of the cartel has two fundamental requirements:
- cheating by a member on the cartel prices, outputs and market shares must be detectable; and
-
detected cheating must be adequately punishable without breaking-up of the cartel.
If banking was a cartel, you would not see advertising on the TV every night inducing customers to switch but you do. That advertising is cheating on the banking cartel the New Zealand Greens want to break up.
There is an infallible rule in competition law enforcement. It arises mostly crisply in merger law enforcement. If competitors oppose a merger, the merger must be pro-consumer. If the merger is anti-competitive, that merger will increase prices. The competing firms can follow those prices up and profit from the weakening of competition subsequent to the merger.
@BernieSanders @GrantRobertson1 why does anyone bother to work in #Denmark?
06 Apr 2016 Leave a comment


Recent Comments